Author: Adam ONeill

  • Can You Roll an Inherited IRA into a Gold IRA? IRS Rules Explained

    Can You Roll an Inherited IRA into a Gold IRA? IRS Rules Explained

    Can You Roll an Inherited IRA into a Gold IRA? IRS Rules Explained
    Can You Roll an Inherited IRA into a Gold IRA? IRS Rules Explained

    Quick Summary

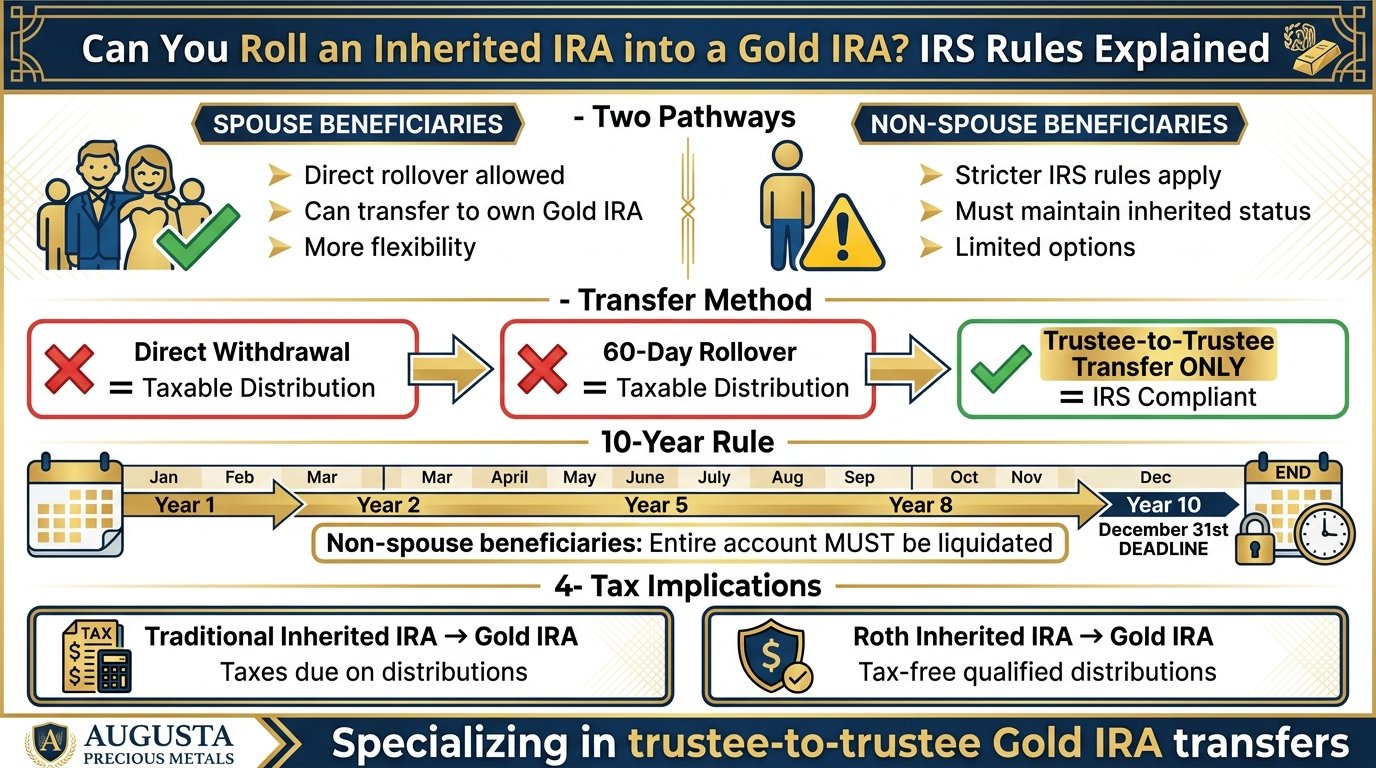
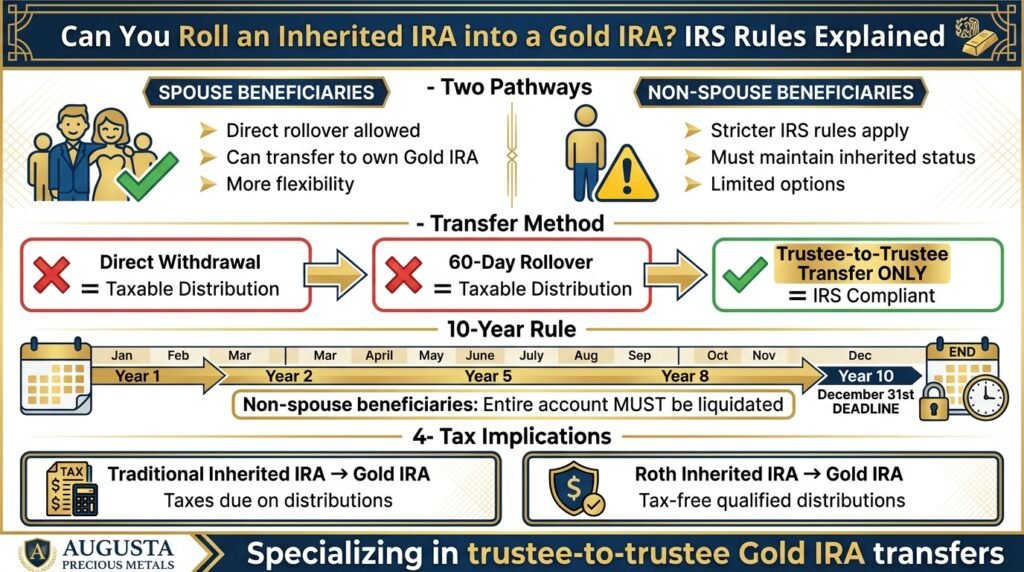
    1. Spouse beneficiaries can roll an inherited IRA directly into their own Gold IRA, while non-spouse beneficiaries must follow a stricter set of IRS transfer rules.
    2. The only IRS-compliant way to move inherited IRA funds is through a direct trustee-to-trustee transfer — doing it any other way risks treating the funds as a taxable distribution.
    3. Most non-spouse beneficiaries are locked into the 10-year rule, meaning the entire inherited account must be liquidated by December 31st of the 10th year after the original owner’s death.
    4. Augusta Precious Metals specializes in self-directed IRAs and can help beneficiaries navigate trustee-to-trustee transfers into alternative assets like gold.
    5. There’s a critical difference between what a traditional inherited IRA and a Roth inherited IRA mean for your tax bill when converting to a Gold IRA — and getting it wrong is expensive.

    Inheriting an IRA and wanting to move it into gold is absolutely possible — but the rules are strict, and one wrong move can trigger a full taxable distribution.

    When someone passes away and leaves you an IRA, what you’re allowed to do with those funds depends almost entirely on your relationship to the deceased and your classification as a beneficiary.

    The IRS doesn’t treat all heirs the same, and the path to a Gold IRA rollover is very different depending on which category you fall into. Understanding these distinctions before you make any moves isn’t just smart — it’s essential for protecting the tax-advantaged status of the funds you’ve inherited.

    Table of Contents

    1. Quick Summary
    2. Not Every Inherited IRA Can Be Rolled into a Gold IRA
    3. What a Gold IRA Actually Is
    4. The Only Legal Way to Move Inherited IRA Funds
    5. Required Minimum Distributions Still Apply to Inherited Gold IRAs
    6. Step-by-Step: How to Roll an Inherited IRA into a Gold IRA
    7. The Bottom Line on Inherited IRA to Gold IRA Rollovers
    8. Frequently Asked Questions
    Not Every Inherited IRA Can Be Rolled into a Gold IRA
    Not Every Inherited IRA Can Be Rolled into a Gold IRA

    Not Every Inherited IRA Can Be Rolled into a Gold IRA

    The foundational rule of inherited IRAs is simple but often misunderstood: you cannot treat an inherited IRA as your own unless you are the surviving spouse.

    For every other beneficiary — children, siblings, non-married partners, trusts, or estates — the inherited funds must remain in a properly titled inherited IRA and cannot be commingled with your existing retirement accounts. This distinction shapes every decision you’ll make about transferring those funds into a Gold IRA. For people beginning their gold investment research, professional guidance is necessary to take the initial steps.

    Why Spouse Beneficiaries Have the Most Options

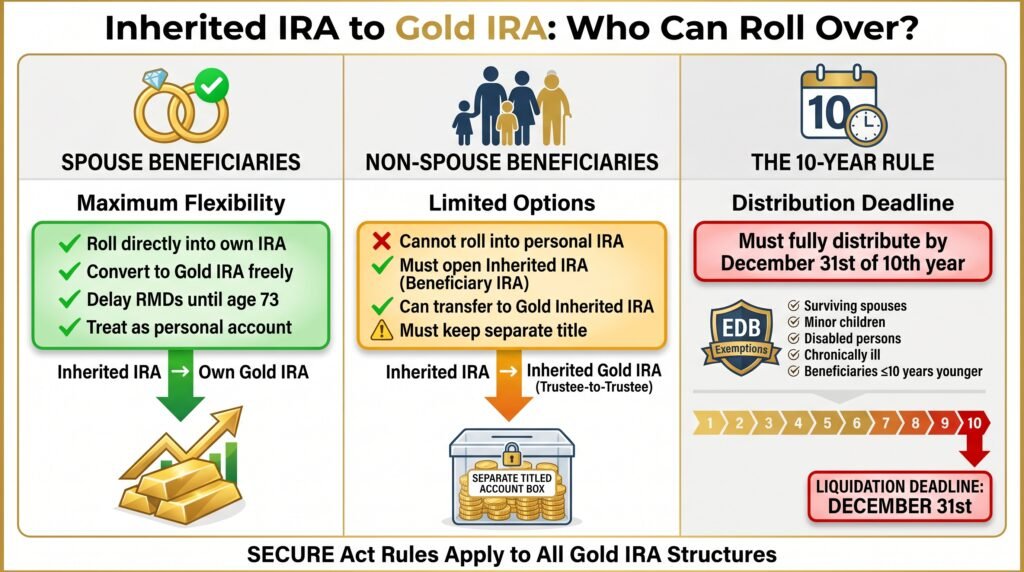
    A surviving spouse has a unique privilege under IRS rules — they can roll the inherited IRA directly into their own IRA, including a self-directed Gold IRA. This means the surviving spouse can delay required minimum distributions (RMDs) until they reach age 73, continue growing the assets tax-deferred, and treat the account exactly as if they had contributed to it themselves.

    No other beneficiary category gets this level of flexibility. For a spouse, converting a traditional inherited IRA into a self-directed Gold IRA follows essentially the same process as any standard IRA rollover.

    What Non-Spouse Beneficiaries Can and Cannot Do

    Non-spouse beneficiaries — which includes adult children, siblings, and most other heirs — cannot roll the inherited IRA into their own personal IRA. What they can do is open an inherited IRA (sometimes called a Beneficiary IRA) titled in the deceased’s name for their benefit, and then initiate a trustee-to-trustee transfer of those funds to a self-directed inherited IRA that holds gold and other IRS-approved precious metals. The account must always remain titled as an inherited IRA, never merged with personal retirement funds.

    The 10-Year Rule That Affects Most Beneficiaries

    The SECURE Act fundamentally changed the distribution landscape for most non-spouse beneficiaries. Unless you fall into the category of an Eligible Designated Beneficiary (EDB) — which includes surviving spouses, minor children of the deceased, disabled individuals, chronically ill individuals, and beneficiaries not more than 10 years younger than the deceased — you are subject to the 10-year rule.

    This means the entire inherited IRA balance must be fully distributed by December 31st of the 10th year following the original account holder’s death. Even within a Gold IRA structure, this liquidation deadline still applies.

    What a Gold IRA Actually Is

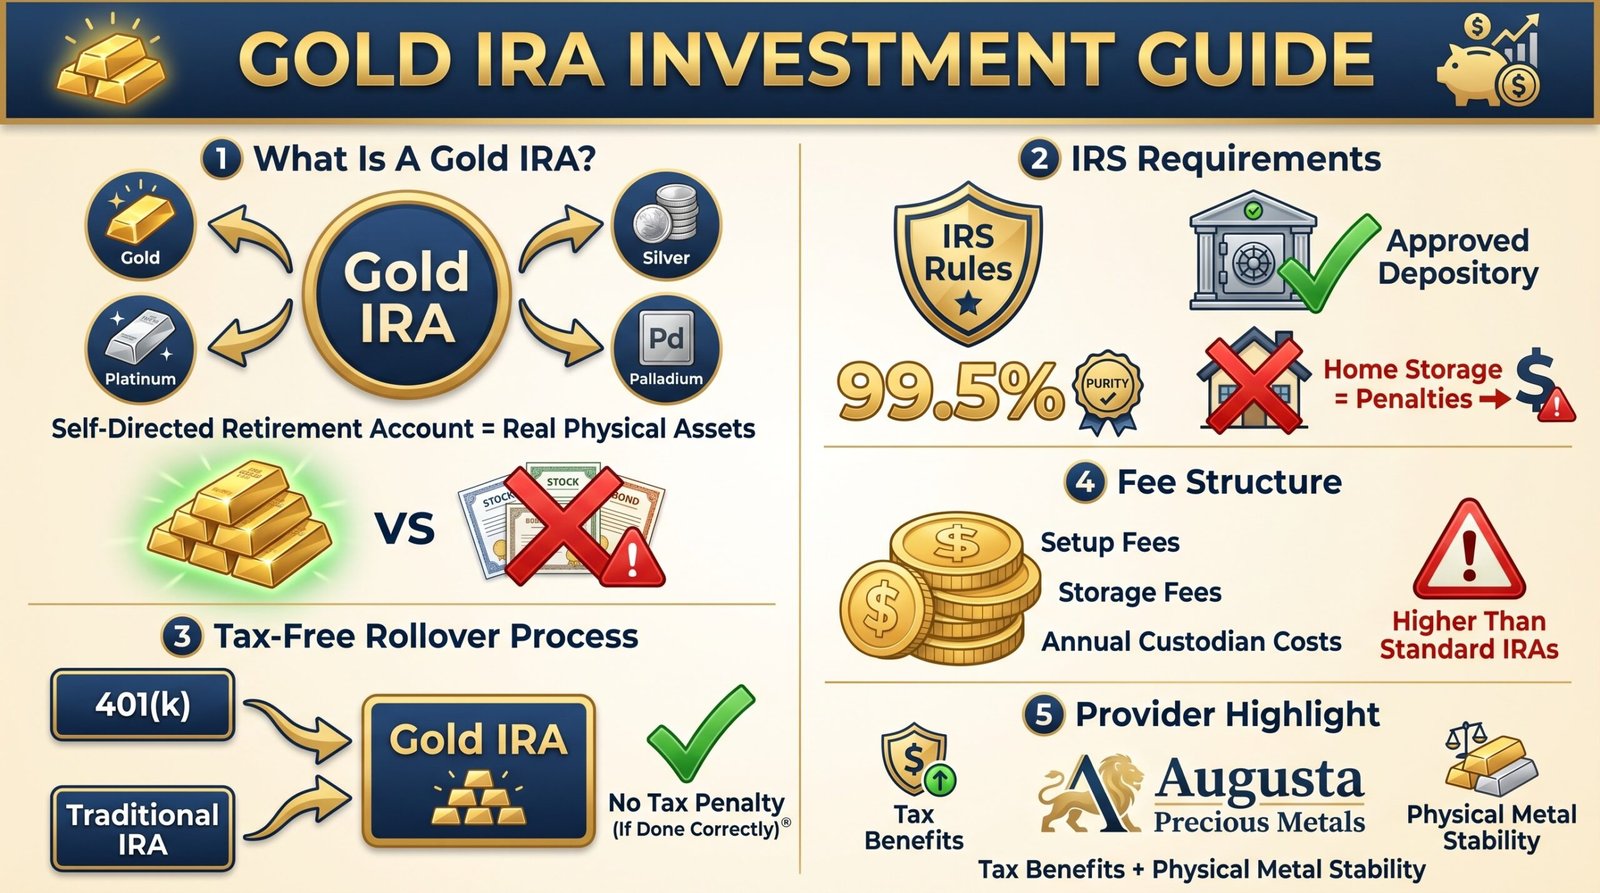
    A Gold IRA is a self-directed individual retirement account that holds physical precious metals instead of — or in addition to — traditional paper assets like stocks and bonds.

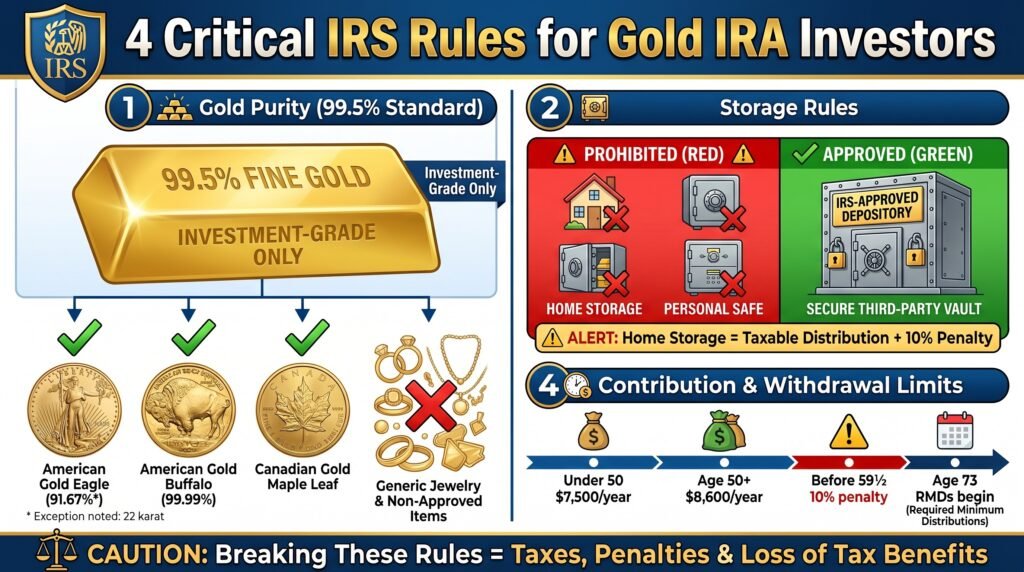
    The IRS permits certain gold, silver, platinum, and palladium products to be held within these accounts, but the metals must meet strict purity standards and be stored in an IRS-approved depository. You cannot take personal possession of the metals while they remain inside the IRA without triggering a distribution event.

    The appeal of a Gold IRA as a destination for inherited retirement funds comes down to diversification and inflation protection. Physical gold has historically held value during periods of economic uncertainty, making it an attractive option for beneficiaries who want to preserve inherited wealth over time rather than liquidate it into cash immediately.

    How a Self-Directed IRA Makes Gold Ownership Possible

    Standard IRA custodians — the major banks and brokerage firms — typically only offer stocks, bonds, mutual funds, and ETFs. To hold physical gold inside an IRA, you need a self-directed IRA (SDIRA) with a custodian that specializes in alternative assets.

    The custodian handles compliance, reporting, and coordinates with an IRS-approved depository where the physical metals are stored on your behalf. This three-party structure — you, the custodian, and the depository — is what keeps the account IRS-compliant.

    Choose a Reputable Gold IRA Custodian

    This is the most important decision in the entire process. Your Gold IRA custodian is the IRS-approved entity that will hold your account, coordinate the transfer, and facilitate metal purchases. Look for custodians with verifiable track records, transparent fee structures, and experience specifically working with federal employees on TSP rollovers.

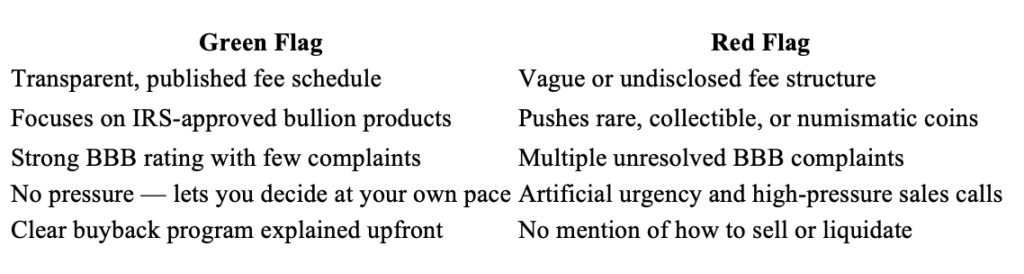
    Be cautious of any company that pressures you to act fast, pushes numismatic or collectible coins with inflated markups, or is vague about storage arrangements and fees. Legitimate custodians never need to rush you. Avoid companies that suggest storing your Gold IRA metals at home; home storage of IRA-owned gold is not IRS-compliant and can result in full account disqualification.

    Augusta Precious Metals is a leading and established gold IRA company that helps investors navigate the Gold IRA process, providing a combination of an ethics-centered approach to empower the customer, the best prices, superb customer service, and expert educational resources.

    Visit Augusta’s official site and receive a free gold IRA company integrity checklist by clicking the banner below. Fill out their short form to get started.
    The Only Legal Way to Move Inherited IRA Funds

    This is where many beneficiaries make costly mistakes. Because an inherited IRA operates under different rules than a standard IRA, the methods for moving those funds are more limited and must be executed precisely. Getting this step wrong doesn’t result in a warning — it results in the entire distribution being treated as taxable income in the year it occurs.

    There are technically two ways funds can move from one IRA to another: a direct trustee-to-trustee transfer and an indirect rollover. For inherited IRAs held by non-spouse beneficiaries, only one of these options is truly safe.

    Why a Trustee-to-Trustee Transfer Is the Safest Move

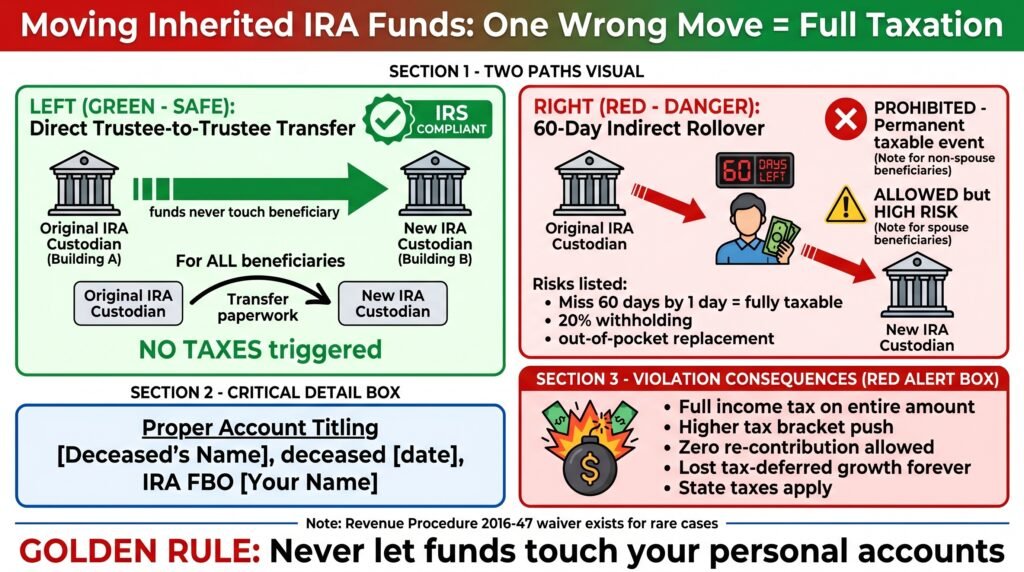
    A direct trustee-to-trustee transfer means the funds move directly from the existing IRA custodian to the new Gold IRA company that works with a trusted custodian without the money ever passing through your hands. You initiate the transfer paperwork, the two parties coordinate the movement of assets, and the funds land in the new account without triggering a taxable event. For non-spouse beneficiaries especially, this is the only reliably IRS-compliant method.

    The key detail is the account titling. The inherited IRA at the receiving custodian must be titled correctly — typically formatted as: “[Deceased’s Name], deceased [date of death], IRA FBO [Beneficiary’s Name].” If the account is titled incorrectly or the funds are deposited into a personal IRA instead of an inherited IRA, the IRS can treat the entire amount as a distribution subject to income tax.

    Working with a gold IRA company experienced in inherited IRA transfers — rather than a standard retail brokerage — dramatically reduces the risk of titling errors or procedural missteps during this process.

    The 60-Day Indirect Rollover Rule and Its Risks

    An indirect rollover is when you take a distribution from the IRA and then re-deposit those funds into another IRA within 60 days. For surviving spouses rolling an inherited IRA into their own IRA, this is technically permitted. However, for non-spouse beneficiaries, the IRS explicitly prohibits indirect rollovers of inherited IRA funds. If a non-spouse beneficiary receives a distribution from an inherited IRA, that money cannot be recontributed to any IRA — it is a permanent taxable event.

    Even for spouses using the indirect rollover method, the risks are significant. Missing the 60-day window by even one day results in the distribution being fully taxable in that year. Additionally, if the inherited IRA was a traditional IRA, the distributing custodian may withhold 20% for federal taxes — meaning you’d have to make up that withheld amount out of pocket to complete a full rollover within the 60-day window, then wait to receive the withholding back as a tax refund.

    The bottom line: unless you are a surviving spouse with a very clear reason to use the indirect method, a direct trustee-to-trustee transfer is the only move that makes practical and financial sense.

    What Happens If You Violate IRS Transfer Rules

    The IRS does not offer a grace period or a second chance when inherited IRA transfer rules are violated. The moment funds from an inherited IRA are distributed incorrectly — whether by being deposited into a personal IRA, withdrawn without proper rollover procedures, or handled through an indirect rollover as a non-spouse beneficiary — the IRS treats the entire amount as an ordinary distribution. That means the full value of the distribution is added to your taxable income for that year.

    • Full income tax liability on the distributed amount in the year the violation occurs
    • Potential to push you into a higher tax bracket if the inherited balance is substantial
    • No ability to re-contribute the funds to any IRA once they’ve been improperly distributed
    • Loss of all future tax-deferred growth on the distributed amount
    • State income taxes may also apply on top of federal liability, depending on your state of residence

    There is one narrow exception worth knowing. The IRS does have a self-certification waiver process under Revenue Procedure 2016-47 that may allow beneficiaries to claim a missed 60-day rollover deadline was due to a qualifying reason — such as a financial institution error or a serious illness. But this is not a guaranteed escape hatch, and it applies only in limited circumstances.

    The simplest way to avoid all of this is to never let the funds touch your personal accounts. Instruct the custodians directly, confirm the transfer method in writing, and verify the account titling before any assets move.

    Make sure you comply with all IRS rules concerning rollovers by accessing Augusta Precious Metals’ free gold IRA guide.

    Visit Augusta Precious Metal’s official site and fill out their short contact form to get started today by clicking the banner below.
    Free gold IRA guide
    Free gold IRA guide

    Required Minimum Distributions Still Apply to Inherited Gold IRAs

    Moving an inherited IRA into a Gold IRA does not exempt you from required minimum distribution rules. The account structure changes, but the IRS distribution requirements follow the assets regardless of what they’re invested in. Whether your inherited IRA holds physical gold bars or index funds, the same RMD deadlines and calculations apply.

    RMD Rules for Eligible Designated Beneficiaries

    Eligible Designated Beneficiaries (EDBs) — surviving spouses, minor children of the account owner, disabled individuals, chronically ill individuals, and beneficiaries within 10 years of the deceased’s age — have more flexibility in how they take distributions. Surviving spouses who roll the inherited IRA into their own IRA can delay RMDs until they reach age 73. Other EDBs can generally stretch distributions over their own life expectancy, using IRS Single Life

    Expectancy tables to calculate annual RMD amounts. This “stretch IRA” strategy allows the bulk of the account to remain invested — and in a Gold IRA context, to remain in physical metals — for a longer period.

    RMD Rules for Non-Eligible Designated Beneficiaries

    For most adult children and other non-EDB beneficiaries, the 10-year rule governs everything. The entire inherited Gold IRA balance must be fully distributed by December 31st of the 10th year after the original owner’s death. If the original account owner had already begun taking RMDs before death, the beneficiary must also take annual RMDs during years one through nine of the 10-year window — not just wait until year ten to withdraw everything.

    This annual RMD requirement during the 10 years is a detail that catches many beneficiaries off guard, particularly because the IRS issued confusing guidance on this point in the years following the SECURE Act.

    The penalty for missing an RMD is a 25% excise tax on the amount that should have been distributed — reduced to 10% if corrected within the correction window. In a Gold IRA, this means you’d need to liquidate a portion of your physical metal holdings each year to satisfy the distribution requirement, which adds a layer of planning complexity.

    Step-by-Step: How to Roll an Inherited IRA Into a Gold IRA

    The process of moving inherited IRA funds into a Gold IRA involves several distinct stages, each with its own compliance requirements. Skipping steps or rushing the process is how costly errors happen. Here’s exactly how it works from start to finish.

    Before initiating anything, gather the original account holder’s death certificate, the IRA account statements, and any beneficiary designation documents on file with the current custodian. These will be required at multiple points in the transfer process.

    1. Confirm Your Beneficiary Status and Eligibility

    Your first step is confirming how you are classified under IRS rules — spouse, Eligible Designated Beneficiary, or non-eligible designated beneficiary. This classification determines which transfer methods are available to you, what the titling of your new inherited IRA must look like, and what distribution timeline you’re locked into. Contact the current custodian of the inherited IRA to confirm the account details and your designated beneficiary status on file.

    If the estate or a trust is named as beneficiary rather than an individual, the rules become even more complex. Trust beneficiaries generally cannot roll over inherited IRA assets at all — funds must remain in the inherited IRA and can only be moved via trustee-to-trustee transfer to another custodian. A tax attorney or financial advisor with specific inherited IRA expertise is essential in these situations.

    2. Find an IRS-Approved Gold IRA Custodian

    What to look for in a Gold IRA custodian:
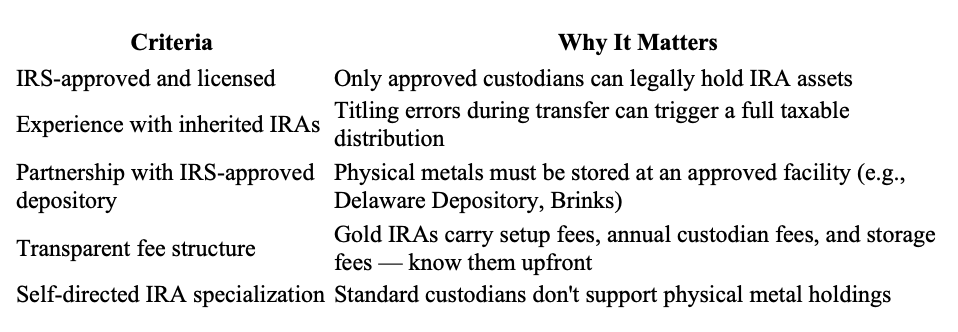
    Not all gold IRA companies are created equal when it comes to inherited IRAs specifically. A custodian that handles standard IRA rollovers regularly may have little experience with the specific titling and transfer requirements that inherited accounts demand. Ask directly: “Have you processed trustee-to-trustee transfers for inherited IRAs into self-directed Gold IRAs before?”

    Fees vary significantly across Gold IRA custodians. Setup fees typically range from $50 to $300, annual custodial fees from $75 to $300, and storage fees from $100 to $300 per year depending on whether you choose segregated or commingled storage at the depository. Segregated storage means your specific metals are stored separately from other clients’ holdings — this typically costs more but provides greater clarity on exactly what you own.

    3. Open a Self-Directed IRA in Your Name

    Once you’ve selected your Gold IRA company, you’ll open a new self-directed IRA account. These gold companies, such as Augusta Precious Metals, Birch Gold Group, National Gold Group, and others, work directly with custodians and facilitate the gold IRA rollover and storage process.

    If you’re a non-spouse beneficiary, this account must be titled as an inherited IRA — not a standard IRA in your name. The typical titling format is: “[Deceased’s Full Name], IRA (deceased [date of death]), for the benefit of [Your Full Name].” Your new custodian should guide you through this titling precisely, but confirm it matches IRS requirements before signing anything.

    You’ll complete new account paperwork with the Gold IRA company, provide identification, and designate your own beneficiaries for the inherited account. Once the account is officially open and titled correctly, you’re ready to initiate the transfer.

    To get started obtaining more information, visit Augusta Precious Metals’ site to receive a free gold and silver IRA information kit by clicking the banner below.
    gold_silver_kit
    Click Here to Receive Augusta Precious Metals’ Latest Gold and Silver Information Kit

    4. Initiate a Direct Trustee-to-Trustee Transfer

    Contact the current custodian of the inherited IRA — the institution where the original account owner held the funds — and request a direct trustee-to-trustee transfer to your new self-directed inherited Gold IRA. Provide them with the new custodian’s account details, the exact account title, and any transfer authorization forms required. Most custodians require a medallion signature guarantee or notarized authorization for inherited IRA transfers, so confirm the documentation requirements early to avoid delays.

    Do not request a distribution check made payable to you. Even if you intend to deposit it into the new Gold IRA, any check made payable to you personally is treated as a distribution the moment it’s issued, regardless of what you do with it afterward. The check — or wire transfer — must go directly from the original custodian to the new Gold IRA custodian.

    5. Select Your IRS-Approved Gold Assets

    Once the funds arrive at your new self-directed inherited Gold IRA custodian, you’ll work with them — and potentially a precious metals dealer they work with — to select which IRS-approved gold products to purchase.

    Common choices include the American Gold Eagle (1 oz, ½ oz, ¼ oz, and 1/10 oz denominations), the American Gold Buffalo (99.99% pure), Canadian Gold Maple Leaf coins, and gold bars from approved refiners like PAMP Suisse or Credit Suisse in sizes ranging from 1 gram to 400 troy ounces. The custodian will coordinate delivery of the physical metals to the IRS-approved depository, where they’ll be held in your account’s name until you take a distribution.

    Learn more about the IRA tax rules in more depth here

    The Bottom Line on Inherited IRA to Gold IRA Rollovers

    An inherited IRA can absolutely be moved into a Gold IRA — but only if you follow the IRS rules precisely, use a direct trustee-to-trustee transfer, choose a custodian experienced with inherited accounts, and maintain the correct account titling throughout the process.

    Spouse beneficiaries have the most flexibility; non-spouse beneficiaries are bound by the 10-year rule in most cases, and the tax treatment of every distribution depends on whether the original account was traditional or Roth. The physical gold strategy can be a powerful way to preserve and grow inherited wealth — but only when executed correctly from the very first step.
    Augusta Precious Metals provides step-by-step guidance on rollovers, custodian selection, and IRS-compliant precious metals investing tailored specifically for government workers and uniformed service members.

    Investment Minimums – Personal Considerations

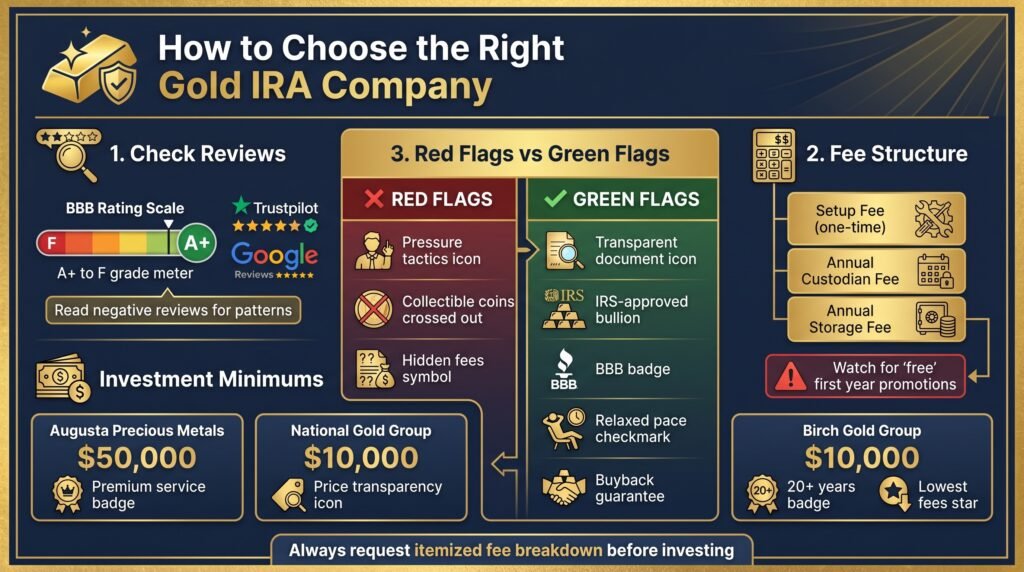
    Certain IRA companies have higher investment minimums than others. If you are a serious investor with a minimum of $50,000, you can take advantage of Augusta Precious Metals’ higher competitive prices, lifelong customer service, and educational resources.

    If you require a lower barrier to entry, both National Gold Group and Birch Gold Group are trustworthy companies that provide a $10,000 investment minimum.

    National Gold Group provides exceptional price transparency and reliable buyback commitment. Birch Gold Group is one of the most established and trusted gold IRA companies, spanning over 20 years, and provides some of the lowest fees in the industry.

    Decide which gold IRA company works for you by clicking the banners below and accessing their free gold IRA guide. Fill out their short contact form to get started.
    Birch Gold Group: Best Gold IRA for Established Trust & Low Fees
    National Gold Group Review

    National Gold Group: Best Gold IRA for Transparency & Buyback

    Frequently Asked Questions

    Here are the most common questions beneficiaries have when considering moving inherited IRA funds into a Gold IRA.

    If you’re ready to explore your options for an inherited IRA to Gold IRA transfer, visit Augusta’s official site and receive a free gold IRA company integrity checklist by clicking the banner below.

    Can a non-spouse beneficiary roll an inherited IRA into a Gold IRA?

    Yes — but with important restrictions. A non-spouse beneficiary cannot roll inherited IRA funds into their own personal IRA. Instead, they must open a properly titled inherited IRA (also called a Beneficiary IRA) with a self-directed custodian that supports gold holdings, and transfer the funds via a direct trustee-to-trustee transfer.

    The account must always remain titled as an inherited IRA in the deceased’s name for the benefit of the beneficiary, and the 10-year liquidation rule still applies. The funds can be invested in IRS-approved physical gold within that inherited IRA structure for the duration of the distribution period.

    Is there a penalty for missing the 60-day rollover window?

    Yes — and it’s severe. If a surviving spouse uses the indirect rollover method and misses the 60-day redeposit deadline, the entire distributed amount is treated as ordinary income for that tax year. There is no partial forgiveness.

    The IRS does have a narrow self-certification process under Revenue Procedure 2016-47 that may apply if the missed deadline was caused by a qualifying event — such as a financial institution error, a serious illness, or a natural disaster — but this is not guaranteed relief. For non-spouse beneficiaries, the 60-day indirect rollover option doesn’t exist at all — any distribution from an inherited IRA by a non-spouse is permanently taxable and cannot be re-contributed to any IRA, period.

    Do I still have to take RMDs from an inherited Gold IRA?

    Yes. Transferring an inherited IRA into a Gold IRA does not change or suspend your RMD obligations. The type and timing of RMDs depend on your beneficiary classification. Eligible Designated Beneficiaries, including surviving spouses and certain other qualifying individuals, can take distributions over their life expectancy.

    Most other beneficiaries — including adult children — are subject to the 10-year rule, which requires full liquidation of the account by December 31st of the 10th year after the original owner’s death.

    If the original owner had already begun taking RMDs before death, non-EDB beneficiaries must also take annual RMDs during years one through nine of the 10-year window. Missing an RMD triggers a 25% excise tax on the amount that should have been distributed, reduced to 10% if corrected within the IRS correction window.

    Sources:

    Gold IRA Rules and Regulations: LendEDU

    Gold IRA storage rules: IRS requirements for storing precious metals: Yahoo!Finance

    Investments in collectibles in individually directed qualified plan accounts: IRS.gov: Retirement plans FAQs regarding IRAs: IRS.gov

    Transform Your TSP into a Secure Gold Investment – FedPilot

    Gold IRA storage rules: IRS requirements for storing precious metals: Yahoo!Finance
  • TSP to Gold IRA Rollover for Federal Employees (Complete Guide)

    TSP to Gold IRA Rollover for Federal Employees (Complete Guide)

    How to Roll Your 401(k) Into Gold Without Paying Penalties

    Quick Summary

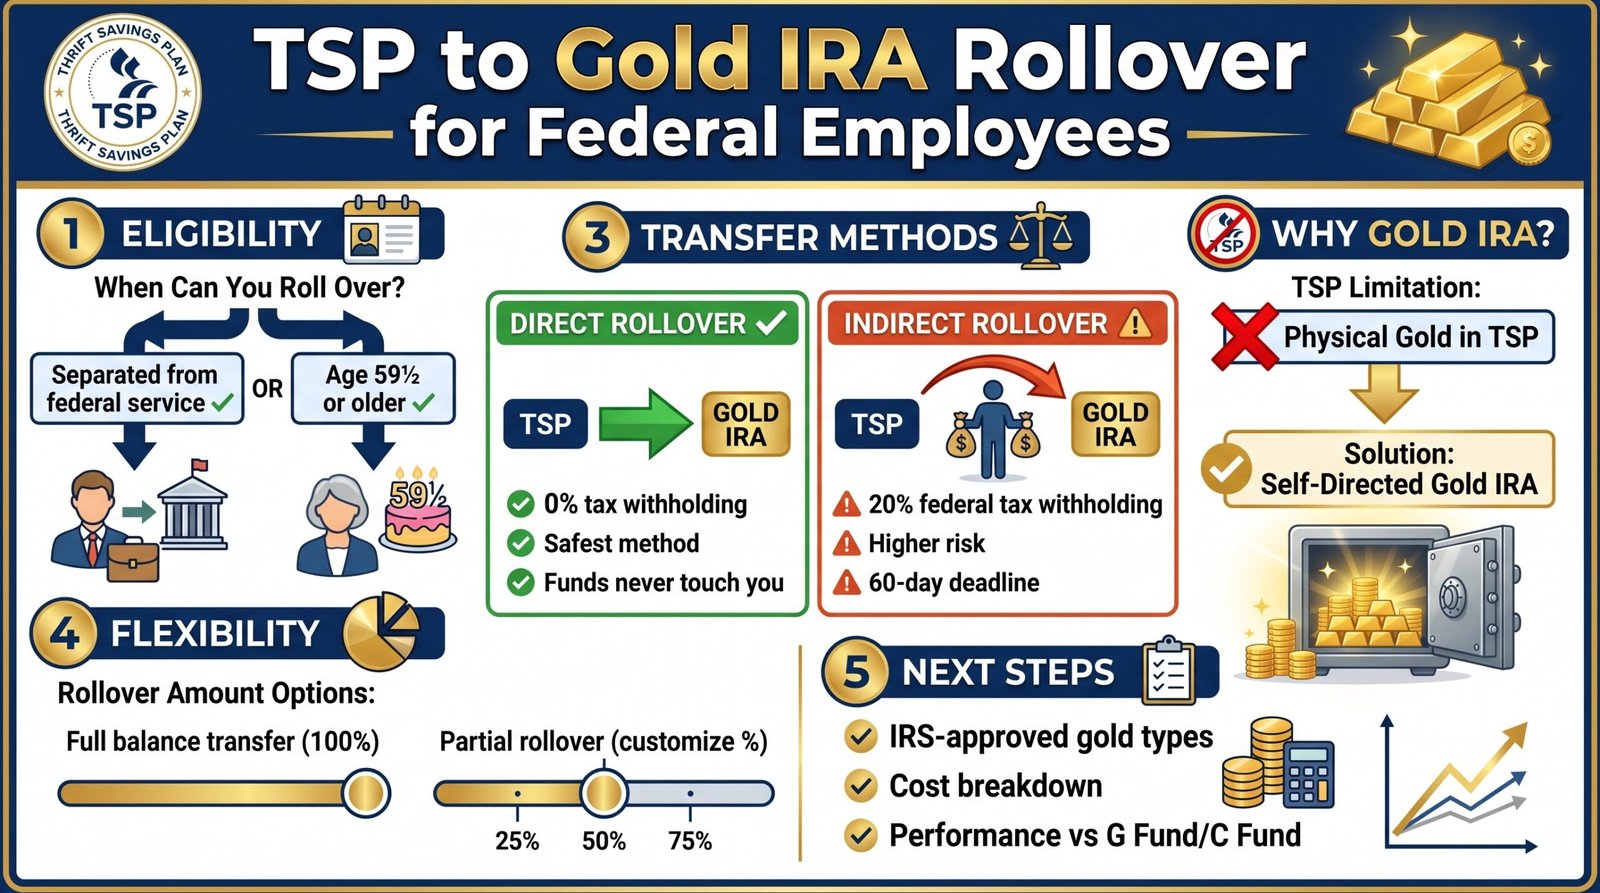
    1. Federal employees and uniformed service members can roll over TSP funds into a Gold IRA, but only after separating from service or reaching age 59½.
    2. The TSP does not allow direct investment in physical gold; a self-directed IRA is the only way to hold precious metals in a federally tax-advantaged retirement account.
    3. A direct rollover is the safest transfer method, avoiding the 20% federal tax withholding that hits indirect rollovers.
    4. You don’t have to move your entire TSP balance; partial rollovers are allowed, giving you flexibility to diversify without going all in.
    5. Keep reading to find out which IRS-approved gold coins and bars qualify, how much a Gold IRA costs, and how gold stacks up against the TSP’s G Fund and C Fund.

    Table of Contents

    1. Quick Summary
    2. Federal Employees Can Move TSP Funds to Gold: Here’s What You Need to Know First
    3. TSP Rollover vs. TSP Transfer: The Difference Matters
    4. How to Convert Your TSP to a Gold IRA in 5 Steps
    5. Costs Involved in a TSP to Gold IRA Transfer
    6. Tax Implications of Rolling Over a TSP to a Gold IRA
    7. Your TSP Retirement Savings Deserve More Than One Option
    8. Frequently Asked Questions

    Federal Employees Can Move TSP Funds to

    Your TSP has been quietly growing for years, but it only offers a handful of fund options, none of which include physical gold. For federal employees looking to hedge against inflation or diversify beyond stock and bond funds, a TSP-to-Gold IRA transfer opens a door most government workers don’t even know exists.

    For people beginning their gold investment research, professional guidance is necessary to take the initial steps.

    Augusta Precious Metals specializes in helping federal employees navigate this exact process, breaking down the rules, costs, and steps involved in moving TSP funds into IRS-compliant precious metals accounts.

    Who Is Eligible to Roll Over a TSP to a Gold IRA

    Not every federal employee can initiate a TSP rollover at will. Eligibility hinges on two key conditions: you must have either separated from federal service or reached age 59½ while still employed. Once either condition is met, you’re eligible to roll over all or part of your TSP balance into a self-directed Gold IRA.

    Members of the uniformed services follow the same rules. If you’re still actively employed and under 59½, an in-service withdrawal may be limited, so timing your rollover matters.

    Why the TSP Cannot Hold Physical Gold Directly

    The Thrift Savings Plan is a government-sponsored defined contribution plan with a fixed menu of investment funds: the G, F, C, S, I, and L Funds. Physical commodities like gold bullion are simply not on that menu. Even indirect exposure through gold mining company stocks is not permitted within TSP fund structures. The TSP is built for simplicity, not alternative assets.

    What a Self-Directed Gold IRA Actually Is

    A self-directed IRA (SDIRA) is a type of individual retirement account that allows you to hold alternative assets, including physical gold, silver, platinum, and palladium, that standard IRAs won’t touch. The IRS permits this structure under specific rules, and it requires a specialized custodian who is approved to manage these asset types.

    Unlike a brokerage IRA where the custodian controls your investment options, an SDIRA puts the investment decisions in your hands, within IRS guidelines. That means you choose which IRS-approved metals to buy, and those metals are stored in an IRS-approved depository, not your home.

    • Holds physical gold, silver, platinum, and palladium
    • Requires an IRS-approved custodian to manage the account
    • Metals must be stored at an approved third-party depository
    • Follows all traditional IRA contribution and distribution rules

    TSP funds can be rolled into this structure tax-free via a direct rollover.

    TSP Rollover vs. TSP Transfer: The Difference Matters

    The terms “rollover” and “transfer” get used interchangeably, but they describe two different processes with very different tax consequences. Understanding the distinction before you move a single dollar out of your TSP can save you from an unexpected tax bill.

    Direct Rollover: The Safest Way to Move TSP Funds

    In a direct rollover, your TSP funds move directly from the TSP to your new Gold IRA custodian; you never touch the money. Because the funds go institution to institution, the IRS does not treat this as a taxable distribution. No withholding, no penalties, no 60-day clock. This is the method most Gold IRA companies will recommend, and for good reason.

    The paperwork involved is straightforward. You’ll work with your Gold IRA custodian to complete the transfer request, and the custodian coordinates with the TSP on your behalf. The entire process typically takes up to two weeks from initiation to when your Gold IRA is funded and ready for metal purchases.

    Indirect Rollover: The 60-Day Rule and Tax Risks

    An indirect rollover means the TSP sends the funds directly to you, and you then have 60 days to deposit them into your Gold IRA. The problem is that the TSP is required to withhold 20% for federal income tax the moment it cuts that check. To complete a full rollover and avoid taxes and penalties, you must deposit 100% of the original amount, including the 20% that was withheld, into your new account within 60 days. That means coming up with the withheld portion out of pocket.

    Miss the 60-day window and the entire distribution becomes taxable income for that year, plus a 10% early withdrawal penalty if you’re under age 59½. The indirect rollover route is rarely worth the risk when a direct rollover is available.

    How to Convert Your TSP to a Gold IRA in 5 Steps

    The process is more straightforward than most federal employees expect. Here’s exactly how it works from start to finish.

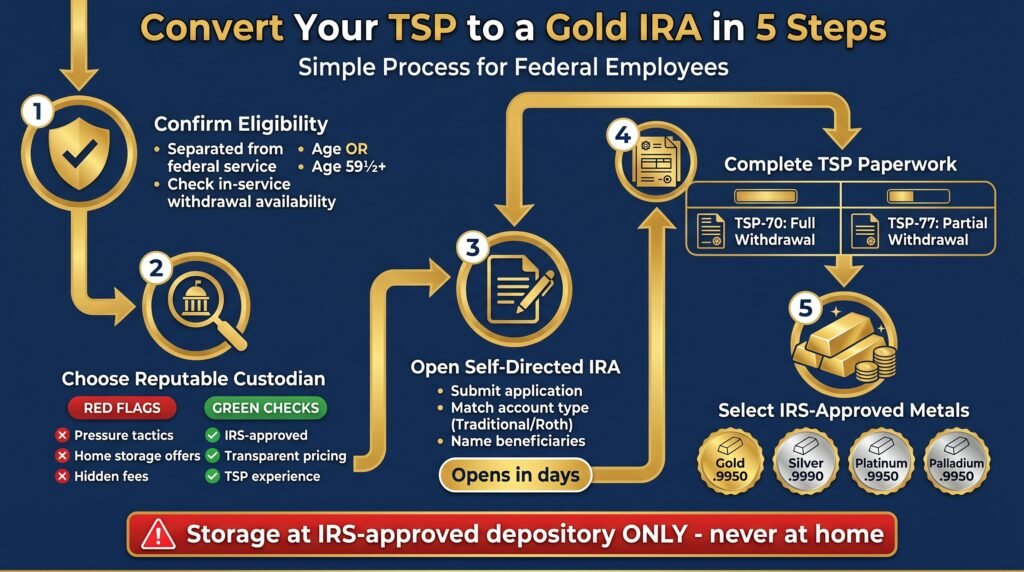
    1. Confirm Your Eligibility to Withdraw From the TSP

    Before anything else, verify that you meet the eligibility requirements. You must have separated from federal service or be at or above age 59½. If you’re still employed and under 59½, check whether your agency allows in-service withdrawals; these are limited and not always available.

    2. Choose a Reputable Gold IRA Custodian

    This is the most important decision in the entire process. Your Gold IRA custodian is the IRS-approved entity that will hold your account, coordinate the transfer, and facilitate metal purchases. Look for custodians with verifiable track records, transparent fee structures, and experience specifically working with federal employees on TSP rollovers.

    Be cautious of any company that pressures you to act fast, pushes numismatic or collectible coins with inflated markups, or is vague about storage arrangements and fees. Legitimate custodians never need to rush you. Avoid companies that suggest storing your Gold IRA metals at home; home storage of IRA-owned gold is not IRS-compliant and can result in full account disqualification.

    Augusta Precious Metals is a leading and established gold IRA company that helps investors navigate the Gold IRA process, providing a combination of an ethics-centered approach to empower the customer, the best prices, superb customer service, and expert educational resources.

    Visit Augusta’s official site and receive a free gold IRA company integrity checklist by clicking the banner below. Fill out their short form to get started.

    Gold IRA Guide
    Gold IRA Guide

    3. Open Your Self-Directed IRA Account

    Once you’ve selected a company, you’ll complete their account application to establish the self-directed IRA. This includes providing identification, selecting a traditional gold IRA structure that matches your TSP account type, and designating beneficiaries. Most custodians can get an account opened within a few business days.

    4. Complete Form TSP-70 or TSP-77 to Initiate the Rollover

    This is where the official TSP paperwork comes in. Form TSP-70 is used for a full withdrawal of your TSP balance, while Form TSP-77 covers partial withdrawals. Your Gold IRA custodian will typically help you complete these forms correctly; an error here can delay the transfer or trigger unintended tax consequences.

    5. Select and Purchase IRS-Approved Precious Metals

    With your Gold IRA funded, you can now direct your custodian to purchase IRS-approved precious metals on your behalf. You don’t physically buy the gold yourself; you instruct your custodian which metals to acquire, and they execute the purchase and arrange for storage at an approved depository. Your options go beyond just gold and include silver, platinum, and palladium, all subject to IRS purity requirements.

    • Gold bullion bars and coins meeting .9950 minimum purity
    • Silver bullion bars and coins meeting .9990 minimum purity
    • Platinum and palladium products meeting .9950 minimum purity
    • IRS-approved coins such as the American Gold Eagle and Canadian Gold Maple Leaf
    • Storage arranged at an IRS-approved depository, not at home

    You are not required to invest your entire rollover into gold. Many federal employees use this stage to build a diversified mix of metals based on their risk tolerance and retirement timeline.

    Once the metals are purchased and transferred to the depository, your Gold IRA is fully operational. From this point forward, the account functions like any other traditional IRA for tax and distribution purposes.

    Costs Involved in a TSP to Gold IRA Transfer

    A Gold IRA is not a free account to maintain. Unlike a TSP, which has some of the lowest administrative fees of any retirement plan in the country, a Gold IRA involves multiple cost layers that you need to understand before committing.

    The good news is that fee structures vary significantly between providers, and some companies offer zero-fee arrangements specifically designed for federal employees making TSP rollovers. Comparing total cost of ownership, not just the setup fee, is essential before choosing a custodian.

    Setup Fees, Annual Maintenance, and Storage Fees

    Most Gold IRA custodians charge a one-time account setup fee ranging from $50 to $150. On top of that, there’s typically an annual maintenance fee between $75 and $300 per year depending on the provider. The third cost layer, and often the largest, is the storage fee charged by the depository holding your physical metals.

    Segregated storage (where your metals are stored separately from other clients’ holdings) costs more than commingled storage, typically ranging from $100 to $150 per year or a small percentage of your account’s total value.

    Zero-Fee Gold IRA Options for Federal Employees

    Some Gold IRA companies offer fee waivers for government workers rolling over TSP funds, covering setup costs, annual maintenance, and sometimes even the first year of storage fees. These offers are worth investigating closely; read the terms to confirm what’s included and for how long, since some waivers only apply for the first year before standard fees resume.

    Learn if your TSP account qualifies for certain fee waivers. Visit Augusta’s official site and access their free gold and silver IRA info kit by clicking the banner below.

    Gold and Silver IRA Info Kit
    Click Here to Receive Gold and Silver IRA Info Kit
    Tax Implications of Rolling Over a TSP to a Gold IRA
    Tax Implications of Rolling Over a TSP to a Gold IRA

    Tax Implications of Rolling Over a TSP to a Gold IRA

    Tax treatment during a TSP to Gold IRA transfer depends entirely on how the rollover is executed and which account types are involved. Get this part right, and the transfer is completely tax-neutral. Get it wrong, and you could face an unexpected tax bill plus penalties.

    Traditional TSP to Traditional Gold IRA: Tax-Deferred Transfer

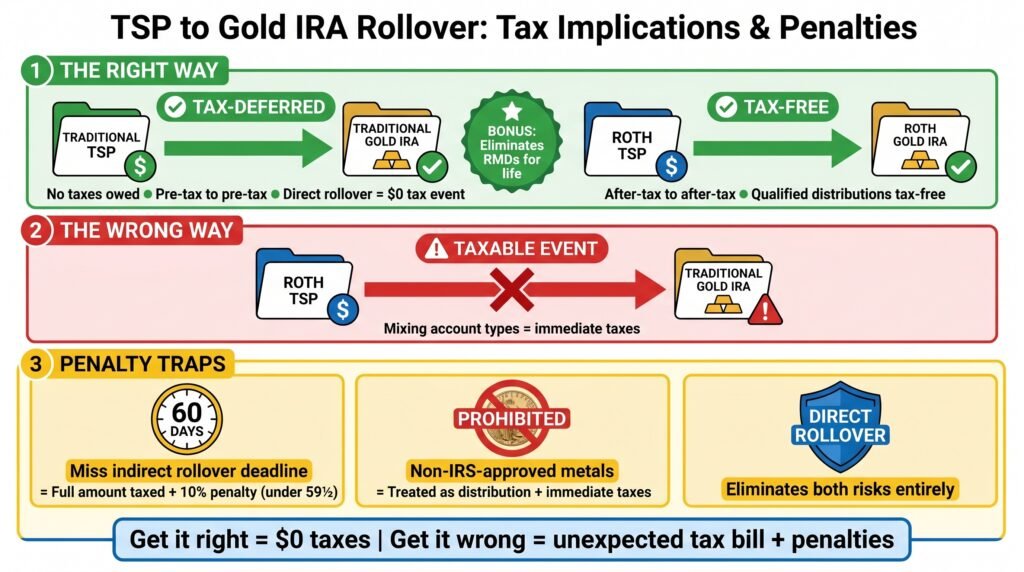
    When you roll a traditional TSP directly into a traditional Gold IRA, the transfer is completely tax-deferred, meaning no taxes are owed at the time of the transfer.

    Both accounts operate on the same pre-tax basis: contributions went in before taxes, growth compounds tax-deferred, and distributions in retirement are taxed as ordinary income. As long as you execute a direct rollover, the IRS sees no taxable event, and your full balance moves into the Gold IRA intact.

    Roth TSP to Roth Gold IRA: What Changes

    A Roth TSP rollover to a Roth Gold IRA follows the same tax-free logic; contributions were already made with after-tax dollars, so qualified distributions in retirement remain tax-free. The key is making sure you’re rolling Roth to Roth. Mixing account types, such as rolling a Roth TSP into a traditional Gold IRA, creates a taxable event that most federal employees want to avoid entirely.

    One important detail: Roth IRAs do not have required minimum distributions (RMDs) during the account holder’s lifetime, while the Roth TSP does. Rolling a Roth TSP into a Roth Gold IRA can actually eliminate your RMD obligation on those funds, which is a meaningful long-term tax planning advantage worth discussing with a financial advisor.

    Penalties to Avoid During the Rollover Process

    The two biggest penalty traps in a TSP to Gold IRA transfer are missing the 60-day window on an indirect rollover and rolling funds into a non-qualifying account type. A failed rollover results in the full distributed amount being treated as taxable income for that year, plus a 10% early withdrawal penalty if you’re under age 59½.

    Using a direct rollover eliminates both risks. Additionally, purchasing non-IRS-approved metals inside your Gold IRA, such as collectible coins, is treated as a distribution in the year of purchase, triggering immediate taxes on the full value of those assets.

    Your TSP Retirement Savings Deserve More Than One Option

    The TSP is one of the best employer-sponsored retirement plans available, low fees, consistent fund options, and decades of reliable performance for federal employees. But having all your retirement assets in a single plan with no exposure to hard assets is a concentration risk, especially during periods of inflation, dollar weakness, or prolonged market downturns. A TSP to Gold IRA transfer isn’t about abandoning your TSP; it’s about building a more complete retirement strategy that the TSP alone was never designed to provide.

    Physical gold has preserved wealth through currency crises, recessions, and geopolitical instability for thousands of years. Adding even a measured allocation through a properly structured Gold IRA can give federal employees a layer of portfolio protection that no TSP fund- not the G Fund, not the C Fund- is built to deliver. You’ve spent a career building your retirement security. Protecting it with more than one tool is simply smart planning. Get the process started of rolling over your TSP account today.

    Visit Augusta’s official site and receive a free gold IRA company integrity guide by clicking the banner below. Fill out their short form to get started.

    Frequently Asked Questions

    Below are the most common questions federal employees ask when researching a TSP to Gold IRA transfer. The answers are based on current IRS guidelines and TSP regulations.

    Can I Roll Over My TSP to a Gold IRA While Still Employed?

    Generally, no, unless you are age 59½ or older. Federal employees under 59½ who are still actively employed cannot initiate a full TSP rollover to an external IRA. Once you reach 59½, an in-service withdrawal becomes available, giving you the ability to roll over TSP funds into a Gold IRA without separating from service.

    If you’ve already separated from federal employment at any age, you are eligible to initiate the rollover regardless of age, though the 10% early withdrawal penalty may apply if you’re under 59½ and use an indirect rollover incorrectly.

    How Long Does a TSP to Gold IRA Transfer Take?

    How Long Does a TSP to Gold IRA Transfer Take?

    The typical timeline from initiating the paperwork to having your Gold IRA fully funded is up to two weeks. The exact duration depends on how quickly your forms are processed by the TSP and how efficiently your Gold IRA custodian handles the incoming transfer.

    Delays can occur if forms are completed incorrectly or if additional verification is required by the TSP. Working with a Gold IRA company that has direct experience handling TSP transfers reduces the chance of paperwork errors that slow the process down.

    Once the metals are purchased, they are transferred directly to your designated IRS-approved depository. You will receive confirmation of both the purchase and the storage arrangement from your custodian.

    Do I Have to Roll Over My Entire TSP Balance?

    No. Partial rollovers are fully permitted. Using Form TSP-77, you can specify exactly how much of your TSP balance you want to transfer to your Gold IRA while leaving the remainder in your TSP funds.

    This gives federal employees the flexibility to diversify into gold without fully exiting the TSP, a strategy that makes practical sense for those who want to maintain exposure to the C Fund or other TSP options while adding a hard asset allocation.

    Is Physical Gold Stored at Home Allowed in a Gold IRA?

    No, and this is a critical point. IRS rules require that all physical metals held inside an IRA be stored at an IRS-approved depository. Taking personal possession of Gold IRA metals, including storing them at home or in a personal safe, is treated by the IRS as a distribution.

    That means the full value of the metals becomes taxable income in the year you take possession, plus the 10% early withdrawal penalty if you’re under 59½. Any company suggesting home storage as a valid Gold IRA strategy is either misinformed or deliberately misleading you.

    Will I Owe Taxes When I Move My TSP to a Gold IRA?

    No taxes are owed when a TSP is rolled over directly into a Gold IRA of the same account type, traditional to traditional, or Roth to Roth. A direct rollover is a trustee-to-trustee transfer where the funds never pass through your hands, so the IRS does not classify it as a taxable distribution.

    Taxes only become a factor if you choose an indirect rollover, miss the 60-day reinvestment window, roll funds into the wrong account type, or purchase non-IRS-approved assets inside your Gold IRA. All of these scenarios are avoidable with proper planning and the right custodian guiding the process.

    If you have a mix of traditional and Roth TSP funds, work with your Gold IRA provider to ensure each portion rolls into the correct corresponding account type.

    Mismatching account types during a rollover creates a taxable event that cannot be reversed after the fact.

    For federal employees ready to explore diversifying their retirement with physical precious metals, Augusta Precious Metals provides step-by-step guidance on TSP rollovers, custodian selection, and IRS-compliant precious metals investing tailored specifically for government workers and uniformed service members.

    Investment Minimums – Personal Considerations

    Certain IRA companies have higher investment minimums than others. If you are a serious investor with a minimum of $50,000, you can take advantage of Augusta Precious Metals’ higher competitive prices, life-long customer service, and educational resources.

    If you require a lower barrier to entry, both National Gold Group and Birch Gold Group are trustworthy companies that provide a $10,000 investment minimum.

    National Gold Group provides exceptional price transparency and reliable buyback commitment. Birch Gold Group is one of the most established and trusted gold IRA companies, spanning over 20 years, and provides some of the lowest fees in the industry.

    Decide which gold IRA company works for you by clicking the banners below and accessing their free gold IRA guide. Fill out their short contact form to get started.

    Birch Gold Group: Best Gold IRA for Established Trust & Low Fees

    National Gold Group Review

    National Gold Group: Best Gold IRA for Transparency & Buyback

    Sources:

    Gold IRA Rules and Regulations: LendEDU

    Gold IRA storage rules: IRS requirements for storing precious metals: Yahoo!Finance

    Investments in collectibles in individually directed qualified plan accounts: IRS.gov: Retirement plans FAQs regarding IRAs: IRS.gov

    Transform Your TSP into a Secure Gold Investment – FedPilot

    Gold IRA storage rules: IRS requirements for storing precious metals: Yahoo!Finance
  • Gold IRA Scams in 2026 – Red Flags + How to Protect Your Retirement

    Gold IRA Scams in 2026 – Red Flags + How to Protect Your Retirement

    How to Roll Your 401(k) Into Gold Without Paying Penalties

    Quick Summary

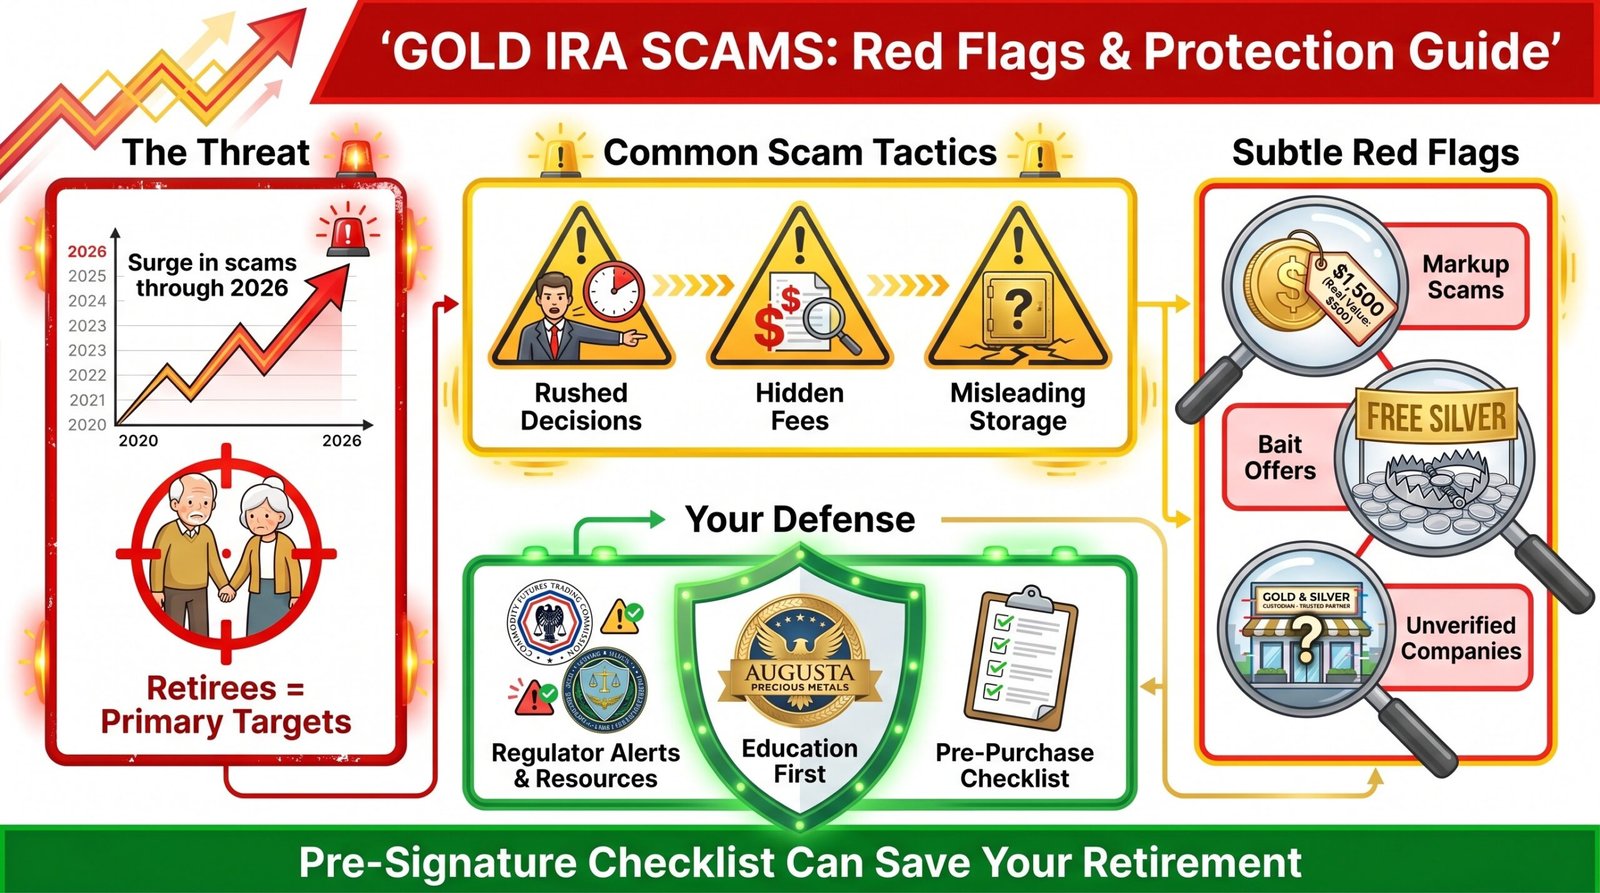
    1. Gold IRA scams are surging in 2026, with retirees being the primary targets of high-pressure tactics, hidden fees, and misleading storage arrangements.
    2. The most dangerous scams are subtle: inflated coin markups, fake “free silver” deals, and unverified custodians that look completely legitimate on the surface.
    3. Augusta Precious Metals is one of the few gold IRA companies that actively educates investors on how to identify and avoid fraud before they commit a single dollar.
    4. The CFTC and FTC have both issued warnings about precious metals fraud; knowing what regulators say can be your first line of defense.
    5. There is a specific checklist you can use before signing anything that could save your retirement from a scam, covered in detail below.

    Table of Contents

    1. Quick Summary
    2. Gold IRA Scams Are Draining Retirements Right Now
    3. What Is a Gold IRA Scam?
    4. The Most Common Gold IRA Scams and Red Flags in 2026
    5. Verify a Gold IRA Company Is Legitimate Through Consumer Advocate Sites
    6. How to Protect Your Retirement from Gold IRA Fraud
    7. A Scam-Free Gold IRA Is Possible: Here Is How to Get Started
    8. Frequently Asked Questions

    Gold IRA Scams Are Draining Retirements Right Now

    The surge in gold’s popularity as a retirement hedge has made the gold IRA space one of the most targeted sectors for financial fraud in 2025 and 2026.

    As more Americans look to protect their savings from inflation and market volatility, bad actors have flooded the space with deceptive companies, misleading claims, and outright theft disguised as investment advice. The appeal of gold is real, but so is the danger of choosing the wrong company to help you get there.

    If you are researching gold IRAs, Augusta Precious Metals has put together a free scam protection resource here that breaks down exactly what to watch for; it is one of the most thorough investor education tools available in the industry right now.

    Why Retirees Are the #1 Target

    Retirees represent the most targeted demographic in gold IRA fraud for one straightforward reason: they have accumulated savings. A person approaching or in retirement often has significant assets in a 401(k) or traditional IRA that can be rolled over, and scammers know exactly how to exploit that transition period. The rollover process involves multiple steps, unfamiliar terminology, and new service providers, which creates the perfect window for manipulation.

    Beyond the money, many retirees are less familiar with how precious metals pricing works. Scammers take advantage of this by presenting inflated markups as “standard industry pricing” or steering investors toward obscure collectible coins with enormous dealer margins. The emotional weight of retirement security also makes people more susceptible; fear of economic collapse and inflation anxiety are powerful psychological levers that dishonest dealers pull constantly.

    What the CFTC and FTC Say About Precious Metals Fraud in 2024–2026

    The Commodity Futures Trading Commission (CFTC) has explicitly warned consumers about precious metals fraud, specifically calling out schemes where dealers charge excessive markups, misrepresent storage arrangements, or claim gold is being held on behalf of investors when it is not. The CFTC notes that in many cases, the metals are never actually purchased; investors pay for gold that simply does not exist.

    The Federal Trade Commission (FTC) has similarly flagged high-pressure precious metals sales as a recurring category of consumer complaints. Both agencies emphasize that legitimate dealers will never rush you into a decision, hide their fee structures, or discourage you from seeking independent advice. If any of those behaviors appear during your research process, treat them as serious warning signs, not minor inconveniences.

    What Is a Gold IRA Scam?
    What Is a Gold IRA Scam?

    What Is a Gold IRA Scam?

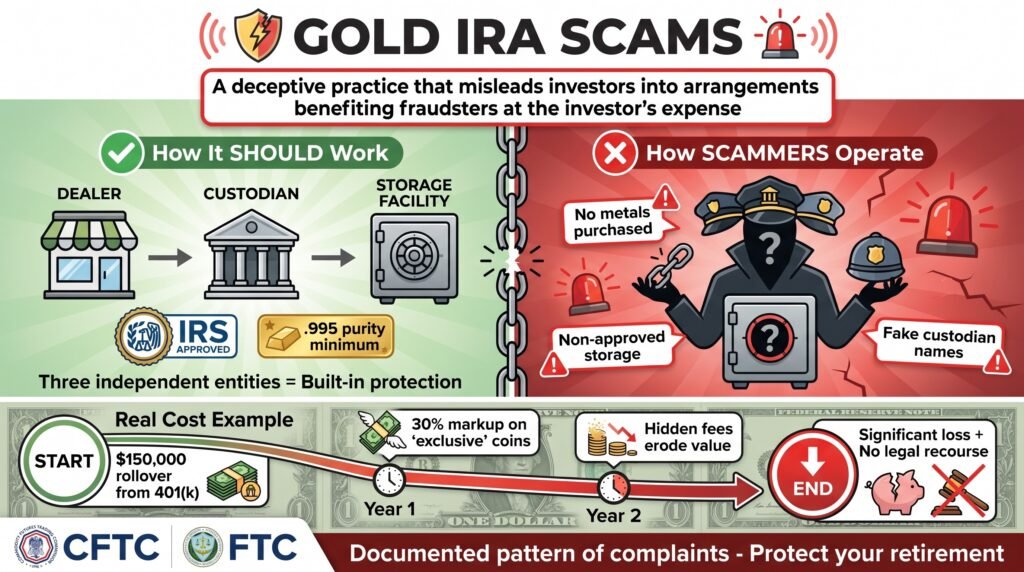
    A gold IRA scam is any deceptive practice by a dealer, custodian, or promoter that misleads an investor into a gold IRA arrangement that benefits the fraudster at the investor’s expense. To any beginning gold investor, this can be a challenge to identify.

    How Legitimate Gold IRAs Work

    A legitimate gold IRA is an IRS-recognized self-directed individual retirement account that holds physical precious metals instead of, or alongside, traditional paper assets. To be IRS-compliant, the gold must meet a minimum purity standard of .995 fineness for bars and .9999 fineness for most coins.

    The metals must be stored in an IRS-approved depository, not at home or in a personal safe. A qualified custodian, not the dealer, is legally responsible for managing the account. The process typically involves three separate entities: a dealer, a custodian, and a storage facility.

    Where Scammers Hijack the Process

    The multi-step nature of a gold IRA is exactly where fraud enters. Dishonest companies blur the lines between these roles, sometimes acting as dealer, custodian, and storage provider simultaneously, which removes the checks and balances that protect investors.

    Others use legitimate-sounding custodian names without formal agreements, or direct your metals to non-approved storage facilities while collecting ongoing storage fees. Some never purchase the metals at all.

    The Hidden Cost of Getting It Wrong

    Real-world example: An investor rolls over $150,000 from a 401(k) into a gold IRA. The dealer charges a 30% markup on “exclusive” coins instead of standard bullion, adds undisclosed annual fees, and stores the metals in a non-IRS-approved facility.

    Within two years, the effective value of the account, accounting for inflated purchase prices and fee erosion, is worth significantly less than a comparable investment in standard gold bullion through a transparent dealer. The investor has no easy legal recourse because they signed an agreement they did not fully understand.

    This scenario is not hypothetical. It reflects the pattern of complaints documented by the CFTC, FTC, and consumer advocacy organizations. The damage is financial, but also emotional; many victims are people who were simply trying to secure their retirement and trusted the wrong company.

    The Most Common Gold IRA Scams and Red Flags in 2026

    These are not edge cases. Each of the following scam types has been documented in regulatory complaints and consumer reports, and several are actively in use right now.

    1. Unrealistic Return Promises

    No one can guarantee gold will increase in value. Full stop. Any dealer that promises specific returns, guarantees price appreciation, or presents gold as a “risk-free” investment is either uninformed or deliberately misleading you. Gold’s value fluctuates with global markets, and while it has historically served as an inflation hedge over long periods, it is not a guaranteed growth vehicle. The moment a sales rep promises you a specific return percentage, end the conversation.

    2. “Free Silver” Promotions With Hidden Strings

    This is one of the most widely used bait-and-switch tactics in the gold IRA industry. A company offers “free” silver coins as a bonus when you open an account, but the cost of that silver is quietly built into inflated markups on your gold purchase. You are not receiving anything free. You are paying an above-market price for gold to subsidize the “gift.” In some cases, the spread between what you pay and the actual spot price of gold is large enough to immediately put your account at a significant loss.

    Always ask for the total cost breakdown, including the spot price of gold, the dealer markup, and any applicable fees, before accepting any promotional offer. A trustworthy company will give you this information without hesitation. For more tips on avoiding scams, visit this guide on gold IRA scams.

    3. Obscure Coin Pushing Instead of Standard Bullion

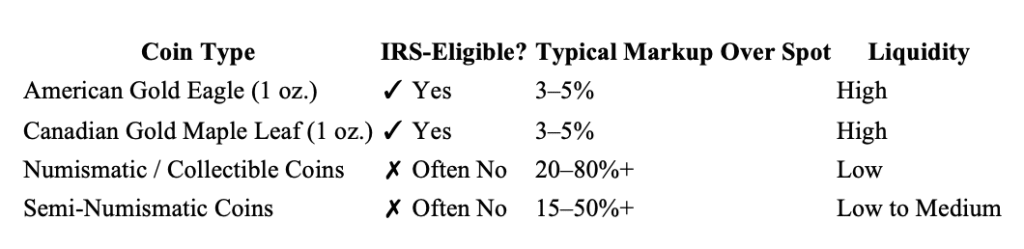
    Some dealers aggressively promote “numismatic” or “semi-numismatic” coins, collectible coins whose value is tied to rarity and condition rather than metal content alone.

    These are sold with dramatically higher markups than standard IRS-approved bullion like the American Gold Eagle or Canadian Gold Maple Leaf. Dealers profit enormously from this, while investors end up with coins that are harder to liquidate, harder to price, and often do not qualify for IRA inclusion under IRS rules.

    If a dealer pushes you toward coins you have never heard of while downplaying standard bullion options, that is a serious red flag. Stick with IRS-approved products and ask for the exact purity and eligibility confirmation in writing.

    4. Misleading Storage Arrangements

    IRS rules require that gold held in an IRA be stored in an approved depository, not at home, not in a bank safe deposit box, and not in any facility the dealer controls. Some dealers either misrepresent where metals are stored, charge fees for storage in facilities that are not IRS-compliant, or worse, collect storage fees while the metals are commingled or unaccounted for.

    There have been documented cases where investors discovered their metals were never segregated from other investors’ holdings, making recovery in the event of company insolvency extremely complicated.

    5. High-Pressure Sales Tactics

    Legitimate gold IRA companies do not need to rush you. If a sales representative tells you that a price is “only good for today,” warns you that economic collapse is imminent unless you act immediately, or calls you repeatedly after an initial inquiry, you are being manipulated, not advised.

    High-pressure tactics are specifically designed to prevent you from doing independent research, consulting a financial advisor, or simply taking the time to think clearly. That urgency is manufactured, and it should immediately disqualify the company from your consideration.

    Augusta Precious Metals is an established precious metals provider that helps investors navigate the Gold IRA process, offering IRS-approved coins and bars, along with educational resources for beginners just getting started with precious metals retirement planning.

    Click the banner below to visit Augusta’s official site and receive a free gold IRA company integrity checklist. Fill out their short form to get started.

    gold ira scam
    gold ira scam

    Verify a Gold IRA Company Is Legitimate Through Consumer Advocate Sites

    Verification is not complicated, but it does require taking a few deliberate steps that most investors skip because a sales pitch made them feel comfortable. Comfort is not the same as safety. Here is how to confirm a company is actually legitimate before you hand over a single dollar.

    Check BBB, Trustpilot, and Google Reviews

    Start with the Better Business Bureau (BBB). Look not just at the rating but at the nature of the complaints: fee disputes, failure to deliver metals, and poor communication are recurring themes in complaints against fraudulent dealers. A company with an A+ BBB rating and hundreds of verified customer reviews is meaningfully different from one with a high rating but only a handful of reviews that all appeared within a short time window.

    Trustpilot and Google Reviews provide additional layers of independent feedback. Look for patterns rather than individual opinions. Consistent mentions of transparent pricing, no-pressure sales, and reliable delivery are good indicators. Consistent complaints about unexpected fees, pushy representatives, or difficulty liquidating metals are serious red flags, regardless of how polished the company’s website looks.

    How to Protect Your Retirement From Gold IRA Fraud
    How to Protect Your Retirement From Gold IRA Fraud

    How to Protect Your Retirement from Gold IRA Fraud

    Protection starts with preparation. The investors who get scammed are not naïve; they are simply investors who trusted without verifying. Building a simple, repeatable verification process into your research eliminates the vast majority of fraud risk before it can affect you.

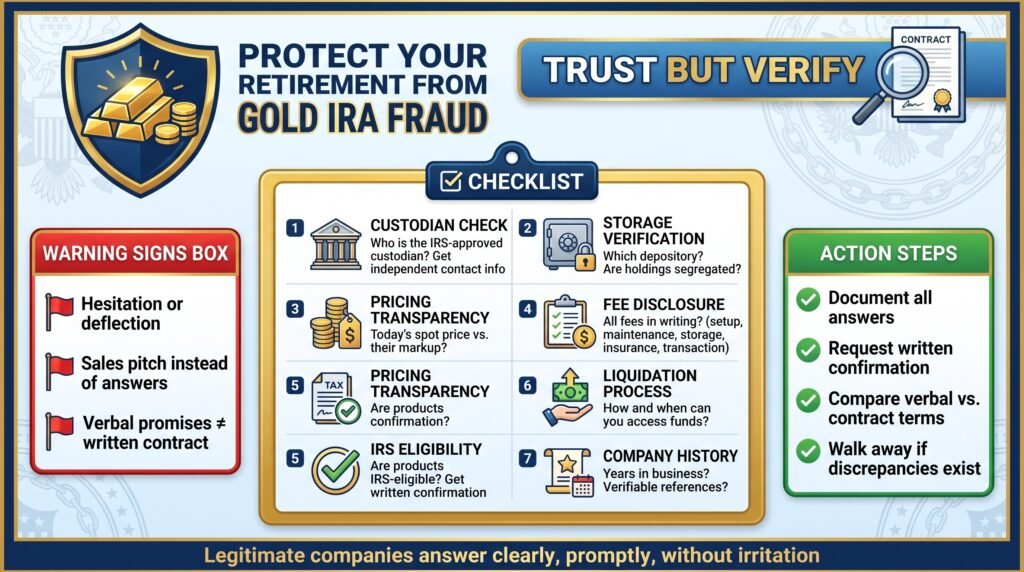
    Questions to Ask Any Gold IRA Company Before Investing

    Before committing to any gold IRA provider, run through the following questions directly with their representative. Their answers, and their willingness to answer, will tell you more than any marketing material ever could.

    Gold IRA Company Vetting Questions:

    What is the full name of the IRS-approved custodian managing my account, and how can I contact them independently?

    Which IRS-approved depository will my metals be stored in, and will my holdings be segregated from other investors’ metals?

    What is the exact spot price of gold today, and what is your markup above that price for the products you are recommending?

    Are all fees- setup, annual maintenance, storage, insurance, and transaction- disclosed in writing before I sign anything?

    Are the specific coins or bars you are recommending IRS-eligible for a self-directed IRA? Can you provide that confirmation in writing?

    What is the process and timeline for liquidating my metals if I need to access funds?

    How long has your company been operating, and can you provide verifiable references or independent reviews?

    A legitimate company will answer every one of these questions clearly, promptly, and without irritation. Any hesitation, deflection, or attempt to redirect you to a sales pitch instead of a direct answer is a warning sign you should not ignore.

    Document the answers you receive. Write them down during the call or ask for written confirmation via email. If a company’s verbal answers do not match what appears in their contract, walk away immediately; discrepancies between what a representative says and what appears in writing are one of the most reliable indicators of a fraudulent operation.

    A Scam-Free Gold IRA Is Possible: Here Is How to Get Started

    A gold IRA is a legitimate, IRS-recognized retirement tool that can genuinely serve as a hedge against inflation and market volatility; the key is choosing the right partner to help you set it up.

    Start by downloading a free scam protection checklist, verify every company you consider against the criteria outlined in this article, and never allow urgency or pressure to replace deliberate, informed decision-making. Your retirement deserves the same due diligence you would apply to any major financial decision, and with the right process, a secure gold IRA is absolutely achievable.

    See Augusta Precious Metals’ full gold IRA company integrity checklist by clicking the banner below. Fill out their short contact form to get started.

    Gold IRA Guide
    Gold IRA Guide

    Investment Minimums – Personal Considerations

    Certain IRA companies have higher investment minimums than others. If you are a serious investor with a minimum of $50,000, you can take advantage of Augusta Precious Metals’ higher competitive prices, lifelong customer service, and educational resources.

    If you require a lower barrier to entry, both National Gold Group and Birch Gold Group are trustworthy companies that provide a $10,000 investment minimum.

    National Gold Group provides exceptional price transparency and reliable buyback commitment. Birch Gold Group is one of the most established and trusted gold IRA companies, spanning over 20 years, and provides some of the lowest fees in the industry.

    Decide which gold IRA company works for you by clicking the banners below and accessing their free gold IRA guide. Fill out their short contact form to get started.

    Birch Gold Group: Best Gold IRA for Established Trust & Low Fees

    National Gold Group Review

    National Gold Group: Best Gold IRA for Transparency & Buyback

    Frequently Asked Questions

    I couldn’t open that page because the site blocks automated access, so I couldn’t check the FAQ against the article’s own wording. I wrote these from the article’s title and topic, using widely reported guidance on gold IRA scams. Before publishing, compare them against your article so the answers match what it says, especially any figures.

    The questions use natural search phrasing, and each answer is under about 60 words so it suits a rich result.

    Gold IRA Scams: Frequently Asked Questions

    What are the biggest red flags of a gold IRA scam?

    Watch for high-pressure sales tactics, guaranteed returns, and pushy claims that you must act immediately. Other warning signs include unsolicited calls, vague or hidden fees, and refusal to put fees in writing. Legitimate companies focus on education and give you time to decide

    Is it legal to store gold from an IRA at home?

    No, not in the way scammers describe it. The IRS requires precious metals held in an IRA to be kept by an approved custodian in an approved depository. “Home storage” or “checkbook IRA” pitches can lead to taxes and penalties, so treat them as a serious warning sign.

    How much markup is too much on gold IRA purchases?

    Some markup over the spot price is normal, but excessive markups are a red flag. Regulators such as the CFTC have cited typical bullion premiums in the range of 5–10%. Ask for a written price breakdown, and be wary of collectible or “rare” coins sold at inflated prices.

    How can I verify a gold IRA company is legitimate?

    Check the company’s record with the Better Business Bureau, the CFPB complaint database, and your state securities regulator or attorney general. Confirm that the custodian and depository are IRS-approved and get all fees in writing before you sign anything.

    What should I do if I think I’ve been scammed?

    Stop sending money and gather your paperwork, including contracts, statements, and call records. Report the company to the FTC, the CFTC, the SEC, and your state attorney general. Contact your IRA custodian as well, and consider speaking with a licensed financial or legal professional.

    What is a gold IRA scam and how does it work?

    A gold IRA scam is any deceptive practice by a dealer, promoter, or custodian that misleads an investor into a gold IRA arrangement designed to benefit the fraudster rather than the investor. Common mechanisms include inflated markups on non-standard coins, fabricated custodian relationships, misleading storage claims, hidden fee structures, and high-pressure sales tactics that prevent informed decision-making.

    The scam typically begins with aggressive outreach, a phone call, online ad, or mailer targeting retirees with messaging about economic instability and the safety of gold.

    Once contact is made, a high-pressure sales process begins that emphasizes urgency, fear, and trust-building rather than transparent information.
    The investor is steered toward overpriced products, often numismatic or semi-numismatic coins with markups of 20–80% above spot price, under the guise of “exclusive” or “collector-grade” investments. The investor may not discover the true cost until years later, when attempting to liquidate and finding the market value of their holdings is a fraction of what they paid.
    In the most severe cases, the metals are never purchased at all.

    The investor pays storage fees, maintenance fees, and annual custodial fees for years, for gold that does not exist. These cases have been prosecuted under federal fraud statutes, but recovery is often partial at best and requires protracted legal action.

    What does the CFTC warn about gold IRA investing?

    What does the CFTC warn about gold IRA investing?
    The Commodity Futures Trading Commission has issued specific consumer alerts about precious metals fraud, warning investors about dealers who charge excessive markups, misrepresent the storage and ownership of metals, or outright fail to purchase the metals investors have paid for.

    The CFTC notes that some fraudulent dealers use elaborate documentation, including fake storage receipts and account statements, to create the illusion that metals are being held on the investor’s behalf when they are not.

    The CFTC also warns against dealers who use retirement account rollovers as an entry point for fraud, specifically targeting investors in the transition between employer-sponsored plans and self-directed IRAs. Their guidance consistently emphasizes the same protective steps: verify the custodian independently, confirm storage arrangements through a third party, and never allow a dealer to control both the sale and the custody of your metals. Their full consumer advisory is publicly available at cftc.gov and is worth reading before you begin any gold IRA research.

    Sources:

    Gold IRA Rules and Regulations: LendEDU

    Gold IRA storage rules: IRS requirements for storing precious metals: Yahoo!Finance
    Investments in collectibles in individually directed qualified plan accounts: IRS.gov: Retirement plans FAQs regarding IRAs: IRS.gov

  • How to Roll Your 401(k) Into Gold Without Paying Penalties

    How to Roll Your 401(k) Into Gold Without Paying Penalties

    How to Roll Your 401(k) Into Gold Without Paying Penalties
    How to Roll Your 401(k) Into Gold Without Paying Penalties

    Quick Summary

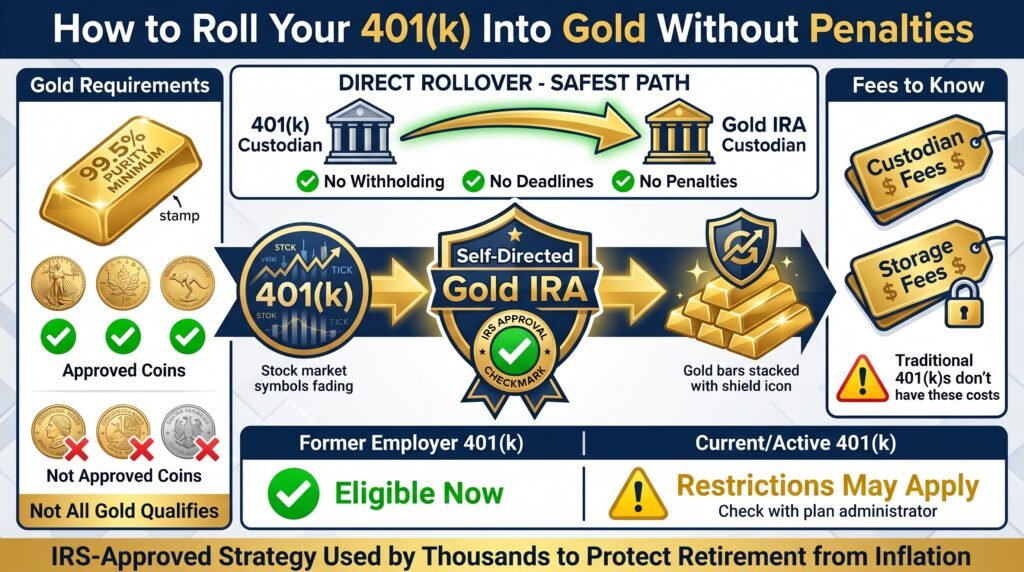
    • Rolling your 401(k) into gold is possible without taxes or penalties, but only if you follow the IRS-approved rollover process correctly, starting with a self-directed Gold IRA.
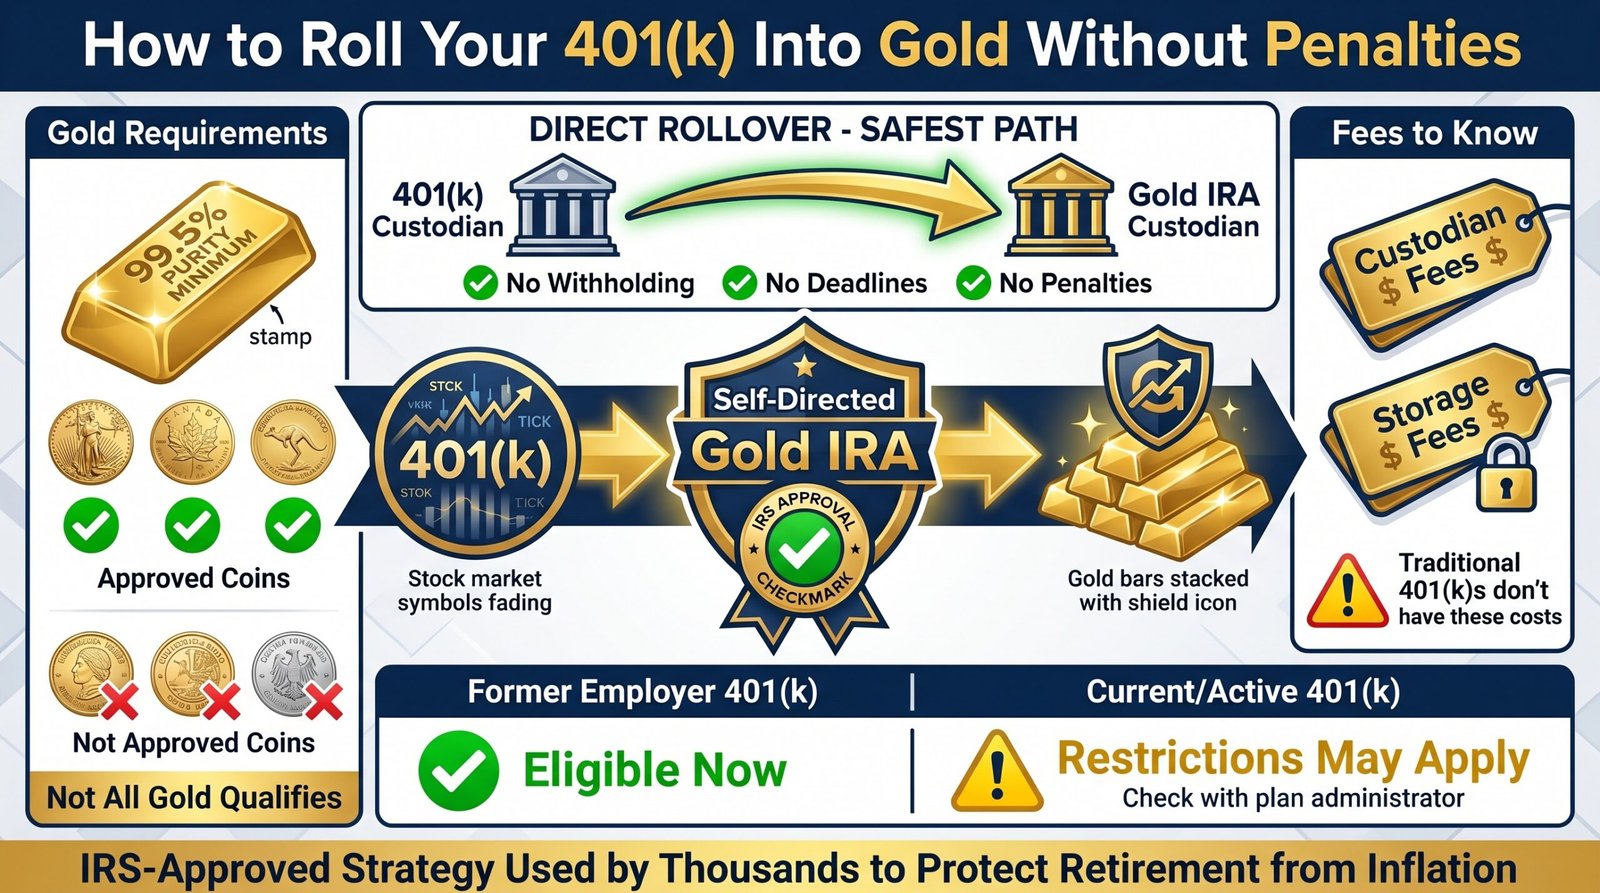
    • A direct rollover is the safest method: funds move directly from your 401(k) custodian to your Gold IRA administrator or custodian, with no withholding, no deadlines, and no risk of accidental penalties.
    • Not all gold qualifies: the IRS requires a minimum purity of 99.5% for gold bars and only approves specific coins, so knowing what you can actually hold matters before you invest.
    • There are fees involved: Gold IRAs come with custodian and storage fees that traditional 401(k) accounts do not, and understanding these upfront protects your long-term returns.
    • Keep reading to find out which type of 401(k) you have and whether you can roll it over right now, because the answer is different depending on whether your plan is active or from a previous employer.

    Your 401(k) doesn’t have to stay locked in the stock market while inflation quietly chips away at its value; rolling it into gold is a real, IRS-approved strategy that thousands of Americans use to protect their retirement.

    A gold IRA rollover from Augusta Precious Metals and similar providers has become one of the most searched retirement strategies in recent years, and for good reason. When paper assets lose value, physical gold has historically held its ground. This guide cuts through the noise and gives you exactly what you need to make the move correctly, without triggering taxes or penalties.

    Table of Contents

    1. Quick Summary
    2. What Is a Gold IRA and Why It Matters for Your Retirement?
    3. Direct Rollover vs. Indirect Rollover: Which One Should You Use
    4. How to Roll Your 401(k) Into Gold in 4 Steps
    5. Your 401(k) Can Work Harder for Your Retirement in Gold
    6. Frequently Asked Questions

    What Is a Gold IRA and Why It Matters for Your Retirement?

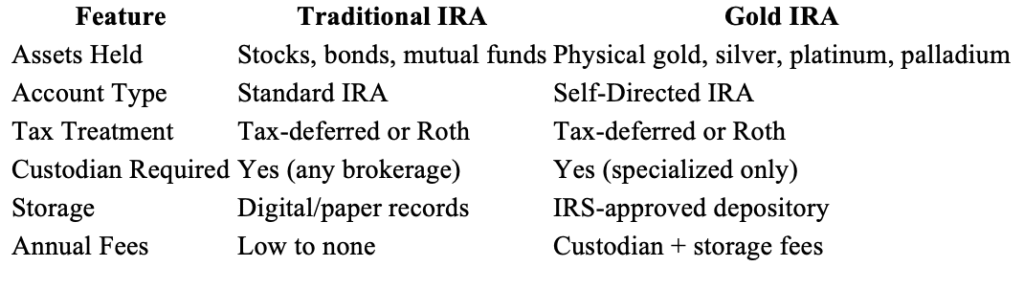
    A Gold IRA is a self-directed individual retirement account that holds physical precious metals instead of stocks, bonds, or mutual funds. It operates under the same IRS rules as a traditional IRA, meaning the same contribution limits, the same tax treatment, and the same required minimum distributions apply. The critical difference is what sits inside the account.

    How a Gold IRA Differs from a Traditional IRA

    A traditional IRA is managed by a brokerage that offers a preset menu of paper investments. A Gold IRA, on the other hand, requires a self-directed IRA custodian, a specialized financial institution approved by the IRS to hold alternative assets including physical precious metals. You do not manage the gold yourself. The custodian handles all compliance, reporting, and storage logistics on your behalf.

    This structure matters because it’s what makes a Gold IRA legally distinct from simply buying gold coins at a dealer. Inside a Gold IRA, your metals are held in a secure, IRS-approved depository, and the account retains all the tax advantages you’ve already built up in your 401(k).

    Why Gold Has Been a Reliable Store of Wealth

    Most beginning gold investors may not know that gold has functioned as a store of value for over 5,000 years. Unlike paper currency, it cannot be printed into devaluation.

    During periods of high inflation, currency crises, and stock market downturns, gold has consistently preserved purchasing power in ways that bonds and cash equivalents often cannot. That track record is exactly why it remains a core diversification tool for serious retirement planners.

    The Role of a Custodian in a Gold IRA

    Every Gold IRA must have an IRS-approved custodian. This is non-negotiable. The custodian is responsible for holding the account, executing purchases of approved metals, arranging insured storage at an approved depository, and filing the necessary IRS reports each year.

    Choosing the right custodian is one of the most important decisions in the entire rollover process. A custodian that specializes in precious metals IRAs will know exactly which gold products are IRS-compliant, which depositories meet federal standards, and how to execute a rollover from your specific 401(k) plan without triggering a taxable event.

    Not every financial institution offers self-directed IRA custody. Banks, standard brokerages, and most 401(k) plan administrators cannot serve as Gold IRA custodians. You will need to open a new account specifically designed for this purpose before initiating any transfer of funds.

    Quick Reference: Traditional IRA vs. Gold IRA

    Augusta Precious Metals is an established precious metals provider that helps investors navigate the Gold IRA process, offering IRS-approved coins and bars, along with educational resources for beginners just getting started with precious metals retirement planning.

    Visit Augusta’s official site and receive a free gold IRA guide by clicking the banner below. Fill out their short form to get started.

    Gold IRA Guide
    Gold IRA Guide

    Direct Rollover vs. Indirect Rollover: Which One Should You Use

    When moving your 401(k) into a Gold IRA, you have two options: a direct rollover or an indirect rollover. They both get your money to the same destination, but the risks involved are not even close to equal.

    For most people, the answer is simple — use the direct rollover. It eliminates risk, removes the pressure of deadlines, and ensures not a single dollar is withheld for taxes during the transfer.

    How a Direct Rollover Works and Why It Is the Safer Option

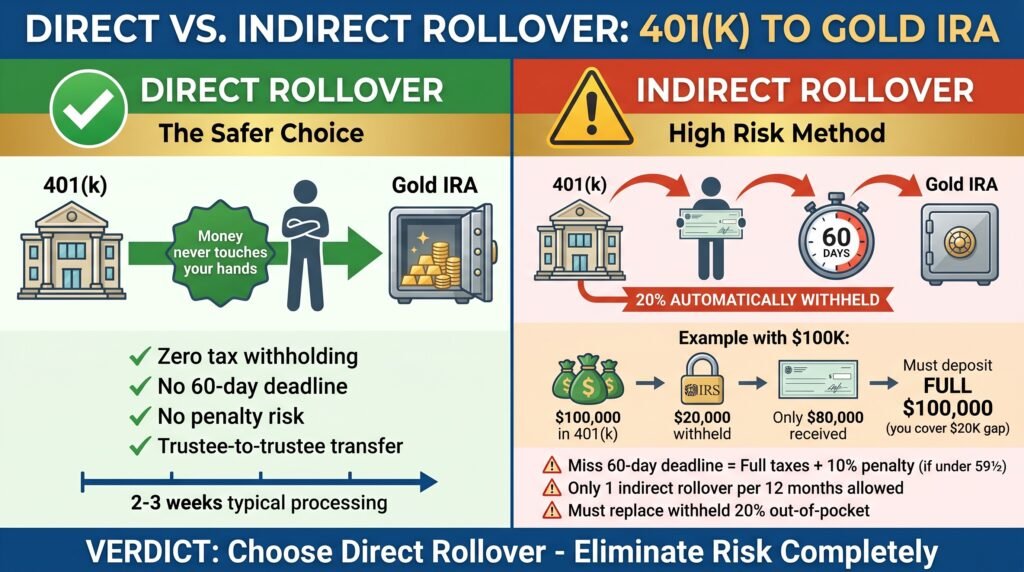
    In a direct rollover, your 401(k) plan administrator transfers your funds directly to your new Gold IRA custodian. The money never passes through your hands. There is no IRS withholding, no 60-day countdown, and no chance of accidentally triggering a taxable distribution. This is the method the IRS refers to as a trustee-to-trustee transfer, and it is the cleanest way to move retirement assets.

    The process typically involves completing paperwork with both your 401(k) plan administrator and your new Gold IRA custodian. Once both sides confirm the transfer, the funds move, sometimes within a few business days, sometimes in two to three weeks depending on your existing plan’s processing time.

    The 60-Day Rule for Indirect Rollovers and the Risks Involved

    An indirect rollover works differently. Your 401(k) plan administrator sends the funds directly to you, and you then have exactly 60 days to deposit the full amount into your new Gold IRA. Miss that deadline by even one day, and the IRS treats the entire distribution as ordinary income, taxable in full, plus a 10% early withdrawal penalty if you are under age 59½.

    How Tax Withholding Can Catch You Off Guard with an Indirect Rollover

    The Hidden Withholding Problem: When a 401(k) plan distributes funds directly to you in an indirect rollover, the IRS requires your plan administrator to withhold 20% for federal taxes automatically. That means if you have $100,000 in your 401(k), you only receive $80,000. To complete a full rollover without penalty, you must deposit the entire $100,000 into your Gold IRA within 60 days, which means you will need to pay the missing $20,000 out of pocket. You do get that 20% back as a tax refund later, but only after filing your return.

    This withholding trap catches a surprising number of people off guard. Many assume they can simply deposit the check they receive and call it complete, only to find they owe taxes on the withheld portion because they didn’t cover the shortfall in time.

    The 60-day indirect rollover also carries an additional restriction: the IRS only allows one indirect rollover per 12-month period across all your IRA accounts. Exceed that limit, and the second transfer is treated as a fully taxable distribution regardless of timing.

    Given all these risks, the indirect rollover rarely makes sense for someone moving a 401(k) into a Gold IRA. Unless you have a specific reason to take possession of the funds temporarily, the direct rollover protects you completely.

    How to Roll Your 401(k) Into Gold in 4 Steps

    The rollover process is more straightforward than most people expect. Once you understand which type of account you have and confirm your eligibility, the actual execution comes down to four clear steps. Following each one in order is what keeps the process tax-free and penalty-free from start to finish.

    1. Confirm Your 401(k) Rollover Eligibility

    Before anything else, you need to confirm that your specific 401(k) plan allows a rollover and under what conditions. For old employer plans, eligibility is almost always automatic. For active employer plans, you need to check whether your plan includes an in-service distribution provision. Call your plan administrator directly and ask two specific questions: “Does my plan allow in-service distributions?” and “What documentation is required to initiate a rollover to an outside IRA?”

    Get the answers in writing if possible. Plan administrators are required to provide you with a Summary Plan Description that outlines all rollover rules, and you are entitled to request one at any time. This step takes a day or two but prevents costly surprises later in the process.

    2. Open a Self-Directed Gold IRA With an Approved Custodian

    Your Gold IRA account must be open and ready to receive funds before you initiate the transfer from your 401(k). Choose a gold IRA company that has a clear, transparent fee structure. During the account opening process, you will complete identity verification and receive the account details your 401(k) plan administrator will need to send the funds. This step typically takes two to five business days once your application is submitted.

    Visit Augusta’s official site and receive a free gold IRA company integrity checklist by clicking the banner below. Fill out their short form to get the process started.

    3. Initiate the Rollover and Transfer Your Funds

    Once your Gold IRA account is open, contact your 401(k) plan administrator and formally request a direct rollover. Provide them with your new Gold IRA custodian‘s account information, including the receiving institution’s name, address, account number, and any wire transfer instructions. The administrator will process the request and send the funds directly to your new custodian — no check passes through your hands, no taxes are withheld, and no deadline clock starts ticking.

    Processing times vary. Some 401(k) plans move quickly and complete the transfer in under a week. Others, particularly older plans or those with less modern infrastructure,  can take three to four weeks. Your Gold IRA custodian will notify you when the funds arrive and are ready to be invested.

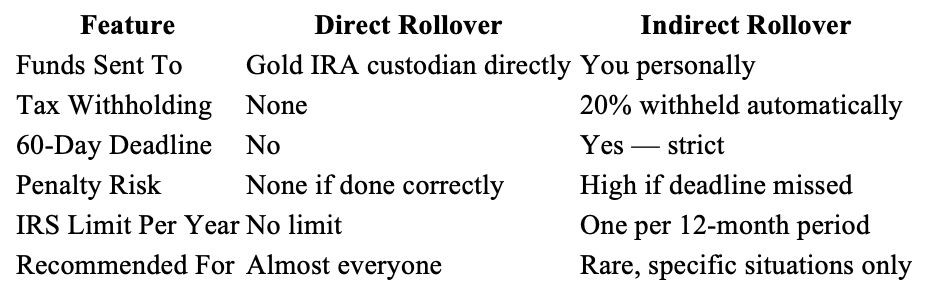
    Direct Rollover vs. Indirect Rollover: At a Glance

    Direct Rollover vs. Indirect Rollover- At a Glance
    Direct Rollover vs. Indirect Rollover- At a Glance

    Once your custodian confirms the funds have arrived, you will work with them to select which IRS-approved gold products to purchase. This is where the physical asset acquisition actually happens, and it is where purity standards and product eligibility become critically important.

    Keep records of every step of this process. Retain the rollover request confirmation from your 401(k) administrators, any wire transfer receipts, and the purchase confirmations from your Gold IRA custodian. These documents are your evidence that the rollover was completed correctly if the IRS ever has questions about the transaction.

    4. Select and Purchase IRS-Approved Gold for Your IRA

    After the funds arrive in your Gold IRA, your custodian will guide you through selecting eligible gold products. This is not as open-ended as buying gold from a dealer; the IRS has a strict list of approved coins and bars that can legally be held inside a retirement account. Your custodian will only offer products that qualify, which removes most of the guesswork from this step.

    Once you select your preferred gold holdings, the custodian purchases them on your behalf and arranges for secure delivery to an IRS-approved depository. You will receive confirmation of the purchase and documentation showing the specific metals held in your account, their weight, purity, and current valuation. From that point forward, your Gold IRA is fully funded and actively holding physical precious metals on your behalf.

    If you are ready to get started with one of the most reputable gold IRA companies for lifelong customer service, prices, and education, click the banner below to visit Augusta Precious Metals’ official site. Access their free gold IRA guide by filling out their short contact form.

    There are many other IRS rules, such as withdrawals, approved depositories, and more, that are worth reviewing once your gold IRA rollover is established. See the full guide here.

    Find out whether gold IRAs are a good choice for your retirement needs. Access our Gold IRA and Inflation-Retirement Calculators.  Perform real-time calculations as you read our reviews. See the buttons below to access these calculators and start protecting your wealth today.

    GOLD IRA CALCULATOR
    GOLD IRA CALCULATOR

    Your 401(k) Can Work Harder for Your Retirement in Gold

    If your retirement savings are sitting in a standard 401(k) exposed entirely to market volatility, you already understand the risk; you have probably watched your balance drop during downturns and wondered whether there is a better way to protect what you have built. Rolling part or all of that 401(k) into a Gold IRA is not a radical move.

    It is a deliberate, IRS-compliant strategy to hold a portion of your wealth in an asset that has preserved value across centuries of economic upheaval. The process is straightforward, the protections are real, and when done correctly with a direct rollover, it costs nothing in taxes or penalties to make the move. Augusta Precious Metals’ step-by-step rollover process is one resource worth reviewing as you evaluate your options and choose a custodian that fits your retirement goals.

    Receive a free gold IRA company integrity checklist from Augusta Precious Metals by clicking the banner below.

    Gold IRA Guide
    Gold IRA Guide

    Investment Minimums – Personal Considerations

    Certain IRA companies have higher investment minimums than others. If you are a serious investor with a minimum of $50,000, you can take advantage of Augusta Precious Metals’ higher competitive prices, lifelong customer service, and educational resources.

    If you require a lower barrier to entry, both National Gold Group and Birch Gold Group provide a $10,000 investment minimum.

    National Gold Group provides exceptional price transparency and reliable buyback commitment. Birch Gold Group is one of the most established and trusted gold IRA companies, spanning over 20 years, and provides some of the lowest fees in the industry.

    Decide which gold IRA company works for you by clicking the banners below and accessing their free gold IRA guide. Fill out their short contact form to get started.

    Birch Gold Group: Best Gold IRA for Established Trust & Low Fees

    National Gold Group Review

    National Gold Group: Best Gold IRA for Transparency & Buyback

    Frequently Asked Questions

    Rolling a 401(k) into a Gold IRA raises a lot of specific questions, especially around taxes, timing, and IRS rules. Here are the most common ones answered clearly so you can move forward with confidence.

    Can I Roll My Entire 401(k) Into a Gold IRA Without Paying Taxes?

    Yes, you can roll your entire 401(k) balance into a Gold IRA without paying taxes, provided you use a direct rollover. In a direct rollover, your funds move from your 401(k) plan administrator directly to your Gold IRA custodian without ever passing through your hands. No taxes are withheld, no taxable event is triggered, and the full balance transfers intact.

    The tax treatment of the Gold IRA going forward depends on which type you open. A Traditional Gold IRA mirrors a traditional 401(k) — contributions and growth are tax-deferred, and you pay ordinary income tax when you take distributions in retirement.

    How Long Does a 401(k) to Gold IRA Rollover Take?

    The timeline from initiating a rollover to having physical gold in your account typically runs between two and six weeks. Opening your Gold IRA account takes two to five business days. The fund transfer from your 401(k) plan administrator can take anywhere from a few days to three weeks depending on your plan’s internal processing speed and whether they require paper forms or accept electronic requests.

    Once the funds arrive at your Gold IRA custodian, purchasing the approved gold products and arranging depository delivery usually takes an additional two to five business days. Starting the process with all your paperwork organized shortens the timeline considerably.

    What Happens if I Miss the 60-Day Deadline on an Indirect Rollover?

    Missing the 60-day deadline on an indirect rollover is a costly mistake. The IRS treats the entire amount that was not deposited into a qualifying retirement account by day 60 as a taxable distribution. You owe ordinary income tax on that amount for the year it was distributed, and if you are under age 59½, you also owe a 10% early withdrawal penalty on top of the tax bill.

    The IRS does allow for waivers in certain documented hardship situations, such as a serious illness, a natural disaster, or errors made by a financial institution, but these waivers are not automatic. You must formally request a waiver from the IRS and provide evidence of the qualifying circumstance. The safest way to avoid this scenario entirely is to use a direct rollover from the beginning, which eliminates the 60-day deadline.

    Can I Hold Physical Gold at Home if It Is Purchased Through My Gold IRA?

    No. Gold purchased through your Gold IRA must be stored at an IRS-approved depository, not in your home, not in a personal safe, and not in a safe-deposit box that you control. The moment you take personal possession of gold that is legally owned by your IRA, the IRS considers that a distribution.

    However, once you reach retirement age and begin taking distributions from your Gold IRA, you can choose to receive your distributions in the form of physical metal rather than cash. At that point, the gold is legally distributed to you and is no longer inside the IRA structure, meaning you can store it however you choose.

    Taking an in-kind distribution of physical gold is a legitimate retirement income strategy and one that some investors specifically plan for from the beginning of their Gold IRA journey.

    Sources:
    Gold IRA Rules and Regulations: LendEDU

    Gold IRA storage rules: IRS requirements for storing precious metals: Yahoo!Finance
    Investments in collectibles in individually directed qualified plan accounts: IRS.gov: Retirement plans FAQs regarding IRAs: IRS.gov

  • Gold IRA Investing (2026): Beginners Guide, Tips, and Insights

    Gold IRA Investing (2026): Beginners Guide, Tips, and Insights

    Gold IRA Investment - Beginner Guide, Tips & Insights
    Gold IRA Investment – Beginner Guide, Tips & Insights

    Quick Summary

    A Gold IRA is a self-directed retirement account that holds physical precious metals like gold, silver, platinum, and palladium, giving you real assets, not just paper-backed investments.

    The IRS requires gold held in an IRA to meet a 99.5% purity standard and must be stored in an approved depository; home storage is not allowed and can trigger penalties.

    Rolling over a 401(k) or traditional IRA into a Gold IRA can be done without triggering taxes if done correctly; the process matters more than most beginners realize.

    Gold IRAs come with higher fees than standard IRAs, including setup, storage, and annual custodian costs that can quietly erode your returns if you are not paying attention.

    Augusta Precious Metals offers a precious metals IRA that lets you combine the tax advantages of a retirement account with the time-tested stability of physical gold and silver.

    Table of Contents

    1. Quick Summary
    2. What Is a Gold IRA?
    3. IRS Rules Every Gold IRA Investor Must Know
    4. How to Open a Gold IRA in 3 Steps
    5. How to Choose the Right Gold IRA Company
    6. Is a Gold IRA Right for You?
    7. Frequently Asked Questions

    What Is a Gold IRA?

    A Gold IRA is a self-directed IRA (SDIRA) that holds physical precious metals instead of traditional paper assets, giving you more control. It works just like a standard IRA in terms of tax treatment and annual contribution limits, but it gives you the ability to invest in tangible assets, specifically IRS-approved gold, silver, platinum, and palladium.

    The trade-off for that control is responsibility. You need to understand the IRS rules, choose your own custodian, and make informed decisions about which metals to purchase. There is no robo-advisor making choices for you.

    How a Gold IRA Differs from a Traditional IRA

    A traditional IRA holds paper-based assets like stocks, ETFs, and bonds. A Gold IRA, by contrast, holds physical metals that must be stored in an IRS-approved depository.

    It requires a specialized custodian, comes with additional storage fees, and gives you exposure to precious metals markets rather than equity markets. The tax treatment: pre-tax contributions and tax-deferred growth for traditional accounts remains the same.

    Types of Metals You Can Hold: Gold, Silver, Platinum, and Palladium

    Despite being called a “Gold IRA,” these accounts can hold more than just gold. The IRS permits four types of precious metals inside a self-directed IRA, provided each meets specific purity requirements:

    • Gold: minimum 99.5% purity (examples: American Gold Eagle coins, Canadian Gold Maple Leaf, gold bars from approved refiners)
    • Silver: minimum 99.9% purity (examples: American Silver Eagle coins, Canadian Silver Maple Leaf)
    • Platinum: minimum 99.95% purity (examples: American Platinum Eagle coins)
    • Palladium: minimum 99.95% purity (examples: Canadian Palladium Maple Leaf coins)

    Not every coin or bar qualifies. Collectibles, rare coins, and metals that fall below IRS purity thresholds are not permitted. Always confirm eligibility with your custodian before purchasing.

    Benefits of Investing in a Gold IRA

    A Gold IRA is not a get-rich-quick strategy; it is a long-term wealth preservation tool. The strongest argument for including one in your retirement plan comes down to what gold does when traditional markets struggle.

    From acting as a hedge against inflation and currency devaluation to portfolio diversification, the benefits of a gold IRA are quite extensive and can best be experienced by investors with the long view.

    A gold IRA introduces a non-correlated asset, meaning gold does not always follow the same market forces that drive stock and bond prices.

    IRS Rules Every Gold IRA Investor Must Know

    The IRS does not give Gold IRA investors a free pass just because they are holding a tangible asset. There are strict rules around purity, storage, custodianship, contributions, and withdrawals, and breaking any of them can trigger taxes, penalties, or the loss of your account’s tax-advantaged status.

    Gold Purity Requirements: The 99.5% Standard

    Gold held inside an IRA must meet a minimum fineness of 99.5%, that is 0.995 on the purity scale. This rule exists to ensure only investment-grade metal enters these accounts. One notable exception is the American Gold Eagle coin, which has a purity of 91.67% (22 karats) but is explicitly approved by the IRS due to its status as legal tender.

    Common IRS-approved gold products include the American Gold Eagle, American Gold Buffalo (24-karat, 99.99% pure), Canadian Gold Maple Leaf, and gold bars or rounds produced by NYMEX- or COMEX-approved refiners. Anything outside this approved list is off-limits.

    Why You Cannot Store Gold IRA Metals at Home

    This is one of the most common misconceptions beginners have. IRS regulations require that all metals held in a Gold IRA be stored in an approved third-party depository, not at home, not in a personal safe, and not in a bank safe deposit box you control. If you take personal possession of your IRA metals, the IRS treats it as a distribution, which means you owe income taxes on the full value and potentially a 10% early withdrawal penalty if you are under 59½.

    The Role of an IRS-Approved Custodian

    Every Gold IRA must be administered by an IRS-approved custodian,  typically a bank, credit union, trust company, or other licensed financial institution. The custodian holds the account, handles transactions, ensures IRS compliance, and coordinates with the approved depository where your metals are physically stored. You cannot self-custody a Gold IRA, and you cannot use a standard brokerage as your custodian.

    Contribution Limits and Withdrawal Rules

    Gold IRAs follow the same contribution limits as traditional and Roth IRAs set by the IRS each year. For 2026, the limit is $7,500 per year, or $8,600 if you are age 50 or older (catch-up contribution). Withdrawals before age 59½ are subject to a 10% penalty plus applicable income taxes. Required Minimum Distributions (RMDs) begin at age 73 for traditional Gold IRAs, the same as any traditional IRA.

    How to Open a Gold IRA in 3 Steps

    Opening a Gold IRA is more straightforward than most beginners expect,  but the details matter. Choose the wrong company or skip a step in the rollover process, and you could end up with unexpected taxes, penalties, or metals that do not qualify under IRS rules.

    Whether you are opening a new account or rolling over a older account, such as a 401k, the entire process generally takes between two and four weeks from start to finish, depending on how quickly your existing custodian processes the transfer. Here is exactly how it works.

    1. Choose a Reputable Gold IRA Company

    Your Gold IRA company is not the same as your custodian; it is the dealer that guides you through the process, helps you select IRS-approved metals, and connects you with a custodian and depository. Choosing the right one upfront saves you from costly mistakes later.

    Look for companies with long operating histories, transparent fee structures, and strong third-party reviews. A company that pressures you into making a quick decision or upsells you into rare or collectible coins is a red flag; collectibles are not IRS-approved for Gold IRAs and can disqualify your account.

    Augusta Precious Metals is one example of an established precious metals provider that helps investors navigate the Gold IRA process, offering IRS-approved coins and bars along with educational resources for beginners who are just getting started with precious metals retirement planning.

    Visit Augusta’s official site and receive a free gold IRA guide by clicking the banner below. Fill out their short form to get started.

    Before committing to any company, ask these questions directly:

    • What are your setup, storage, and annual maintenance fees?
    • Which custodians and depositories do you work with?
    • What IRS-approved metals do you carry?
    • Do you offer buyback programs if I need to liquidate?

    2. Open a Self-Directed IRA with an Approved Custodian

    Once you have selected your Gold IRA company, the next step is opening a self-directed IRA with an IRS-approved custodian. Your Gold IRA company will typically have preferred custodian partners and can facilitate the introduction. The custodian handles the administrative and compliance side of the account; they do not give investment advice, but they ensure every transaction meets IRS requirements. Expect to complete an account application and provide standard identification documents during this step.

    3. Fund Your Account Through a Rollover, Transfer, or Direct Contribution

    You have three ways to get money into your Gold IRA. A direct rollover moves funds from a 401(k), 403(b), or another qualified plan directly into your Gold IRA without you ever touching the money; this avoids taxes and penalties entirely.

    An IRA transfer moves existing IRA funds directly between custodians, also tax-free. A direct contribution means depositing new money up to the annual IRS limit. Most investors use a rollover or transfer since they typically involve larger sums and do not require out-of-pocket cash.

    How to Choose the Right Gold IRA Company

    The Gold IRA industry has grown significantly, and not every company operating in this space has your best interests in mind. Some charge excessive fees, push non-qualifying metals, or use high-pressure sales tactics designed to rush you into decisions before you fully understand what you are buying.

    Taking the time to properly vet your Gold IRA company is not optional; it is one of the most important steps in the entire process. Here is what to look at.

    BBB Ratings, Trustpilot Reviews, and Why They Matter

    Third-party review platforms give you an unfiltered view of how a Gold IRA company actually treats its customers. The Better Business Bureau (BBB) rates companies on a scale from A+ to F based on complaint history, transparency, and business practices. Trustpilot and Google Reviews surface real customer experiences around responsiveness, fees, and the overall buying process.

    Do not just look at the star rating; read the negative reviews specifically. Pay attention to patterns: repeated complaints about unexpected fees, poor communication after the sale, or difficulty with the buyback process are serious warning signs that no amount of marketing polish should override.

    Fee Structures to Watch Out For

    Gold IRAs carry more fees than standard IRAs, and understanding the full cost structure before you sign anything is critical. Most companies charge a combination of the following: a one-time account setup fee, an annual custodian administration fee, and an annual storage fee charged by the depository. Storage fees are typically either a flat annual rate or a percentage of your total holdings.

    Some companies advertise “free” first-year fees as a promotional incentive, which is fine, as long as you know what years two, three, and beyond will cost you. Ask for a complete fee schedule in writing and calculate the total annual cost against your expected account balance before committing.

    Red Flags: High-Pressure Sales Tactics and Hidden Costs

    Be cautious of any Gold IRA company that creates artificial urgency, telling you that gold prices are about to spike, that a “special offer” expires today, or that you need to act immediately to protect your retirement. These are sales tactics, not financial advice.

    Watch out for companies that push numismatic or collectible coins. These coins are marketed as rare and valuable but are not IRS-approved for Gold IRAs, carry massive markups, and are nearly impossible to resell at the price you paid. Legitimate Gold IRA companies focus on standard bullion products, coins, and bars with transparent, market-based pricing.

    Hidden costs are another issue. Some companies bury wire transfer fees, insurance charges, or liquidation fees in the fine print. Always request an itemized breakdown of every possible fee before funding your account.

    Receive a free gold IRA company integrity checklist from Augusta Precious Metals by clicking the banner below.

    Investment Minimums – Personal Considerations

    Certain IRA companies have higher investment minimums than others. If you are a serious investor with a minimum of $50,000, you can take advantage of Augusta Precious Metals’ higher competitive prices, lifelong customer service, and educational resources.

    If you require a lower barrier to entry, both National Gold Group and Birch Gold Group provide a $10,000 investment minimum.

    National Gold Group provides exceptional price transparency and reliable buyback commitment. Birch Gold Group is one of the most established and trusted gold IRA companies, spanning over 20 years, and provides some of the lowest fees in the industry.

    Decide which gold IRA company works for you by clicking the banners below and accessing their free gold IRA guide. Fill out their short contact form to get started.

    Birch Gold Group: Best Gold IRA for Established Trust & Low Fees

    National Gold Group Review

    National Gold Group: Best Gold IRA for Transparency & Buyback

    Is a Gold IRA Right for You?

    A Gold IRA is not the right move for every investor, but for the right person, it can be one of the most effective tools for building a retirement portfolio that is genuinely resilient to inflation, market crashes, and currency devaluation.

    It makes the most sense if you have a long investment time horizon (ideally 10 or more years), have existing retirement funds of at least $25,000 to $50,000 that justify the fee structure, want diversification beyond stocks and bonds, and are comfortable with a self-directed account that requires more active decision-making than a standard IRA. If you are looking for quick returns, high liquidity, or passive income from dividends and interest, a Gold IRA is not the right primary vehicle. But as one component of a broader, balanced retirement strategy, it is a powerful one.

    Read our full list of reviews of the best gold IRA companies that we have carefully researched and vetted here.

    Find out whether gold IRAs are a good choice for your retirement needs. Access our Gold IRA calculator. Bookmark this page and perform real-time calculations as you read our reviews.

    Click the banner below to access these calculators and start protecting your wealth today.

    GOLD IRA CALCULATOR
    GOLD IRA CALCULATOR

    Frequently Asked Questions

    If you are still weighing whether a Gold IRA fits your retirement plan, these are the questions most beginners ask before taking the next step.

    Can I roll over my 401(k) into a Gold IRA without paying taxes?

    Yes, you can roll over a 401(k), 403(b), TSP, or existing traditional IRA into a Gold IRA without triggering taxes or penalties, provided you use a direct rollover. In a direct rollover, the funds move from your existing plan administrator directly to your new Gold IRA custodian; you never personally receive the money.

    If you opt for an indirect rollover instead (where the funds are sent to you first), you have 60 days to deposit the full amount into your new Gold IRA or the IRS will treat the distribution as taxable income and apply a 10% early withdrawal penalty if you are under age 59½. Direct rollovers are always the safer, cleaner option.

    Read our more extensive article here.

    What gold coins and bars are IRS-approved for a Gold IRA?

    What gold coins and bars are IRS-approved for a Gold IRA?

    IRS-approved gold products must meet a minimum fineness of 99.5% (except the American Gold Eagle coin). Below is a breakdown of the most commonly approved gold coins and bars for Gold IRA investors:

    Always confirm with your custodian that the specific product you intend to purchase is on the IRS-approved list before completing any transaction. Purchasing a non-qualifying metal inside your IRA can trigger immediate tax consequences.

    Gold bars must be produced by a refiner that is accredited by a national government mint or an approved commodities exchange such as NYMEX or COMEX. The bar must also be accompanied by an assay certificate verifying its weight and purity. Your Gold IRA company should handle verification as part of the purchase process; if they do not, that is a red flag worth taking seriously.

    How much does it cost to open and maintain a Gold IRA?

    The total cost of a Gold IRA typically includes three categories of fees: a one-time setup fee ranging from $50 to $150, an annual custodian administration fee between $75 and $300, and an annual depository storage fee between $100 and $300 (or a percentage-based fee for larger accounts). In total, most investors pay between $175 and $600 per year in ongoing fees, depending on the company and their account balance.

    Some providers waive setup fees or first-year storage fees as a promotional incentive, which is worth taking advantage of, as long as you understand what the ongoing costs look like in subsequent years.

    Investment minimums will vary from company to company. See our list of the best gold IRA companies we give a full breakdown of the fees and minimums here.

    What happens to my Gold IRA when I retire?

    When you reach retirement age and want to access your Gold IRA funds, you have two primary options: take an in-kind distribution or liquidate your holdings for cash. An in-kind distribution means the physical metals are transferred directly to you; you take possession of the actual gold or silver coins and bars.

    A cash distribution means your custodian sells the metals and deposits the proceeds into your account, which you then withdraw as cash. Both options are subject to ordinary income tax for a traditional Gold IRA (since contributions were made pre-tax).

    Required Minimum Distributions (RMDs) begin at age 73 for traditional Gold IRAs, the same rule that applies to all traditional IRAs. At that point, you are required to withdraw a minimum amount each year based on your account balance and IRS life expectancy tables.

    If your Gold IRA holds physical metals and you want to satisfy your RMD without selling, you can take an in-kind distribution of metals equal in value to the required withdrawal amount, though this adds logistical complexity that not all custodians handle the same way.

    If you are ready to explore how physical precious metals can strengthen your retirement strategy, Augusta Precious Metals offers a full range of IRS-approved gold and silver products along with expert guidance to help you build a Gold IRA that works for your long-term goals.

    Get started with a tax-advantaged IRA with Augusta by clicking the banner below.

    Sources:
    Gold IRA Rules and Regulations: LendEDU

    Gold IRA storage rules: IRS requirements for storing precious metals: Yahoo!Finance
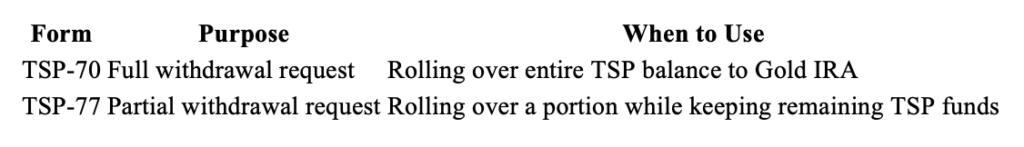
    Investments in collectibles in individually directed qualified plan accounts: IRS.gov: Retirement plans FAQs regarding IRAs: IRS.gov

  • Top 4 Reasons Why Chasing the Gold Price is an Investing Mistake in 2026

    Top 4 Reasons Why Chasing the Gold Price is an Investing Mistake in 2026

    Quick Summary

    Chasing short-term gold price moves is one of the biggest mistakes precious metals investors make. Gold prices are driven by emotion, fear, speculation, interest rates, currency strength, and geopolitical events — all of which create unpredictable volatility. Investors who buy after major rallies often enter near market peaks and risk panic-selling during corrections.

    Instead of treating gold like a fast-moving trade, the article explains why it works better as a long-term wealth preservation asset and portfolio hedge. Successful investors typically focus on disciplined accumulation, diversification, and long-term strategy rather than trying to “time” gold price spikes. The article also highlights how emotional investing, FOMO, and headline-driven decisions can lead to poor returns and missed opportunities elsewhere.

    Table of Contents

    1. Introduction
    2. Reason 1. Gold Should Not Be Treated as a Risk Asset.
    3. Reason 2. Gold Investing Requires a Deeper Understanding of the Investing Landscape
    4. Reason 3. Understanding Gold’s Strategic Purpose
    5. Reason 4. Making Portfolio Diversification a Priority. Not Price.
    6. Avoiding Gold Investing Mistakes

    Introduction

    Why are Americans often called ‘bubble chasers’? They wait until prices have already surged, read headlines about new all-time highs, feel that unmistakable pull of missing out, and then finally jump in, right before a topping, price stabilization, or a correction.

    Most of the time, Americans are deal-finders and are always on the lookout for a deal. Sadly, with investing, when finding a bargain matters the most, many uneducated investors buy at the top and panic sell at the bottom.

    Reason 1. Gold Should Not Be Treated as a Risk Asset.

    This pattern repeats itself with remarkable consistency across market cycles.

    Gold investing should be one of the most straightforward components of a diversified portfolio. Gold provides stability, acts as insurance against currency devaluation, and offers a hedge during periods of genuine uncertainty.
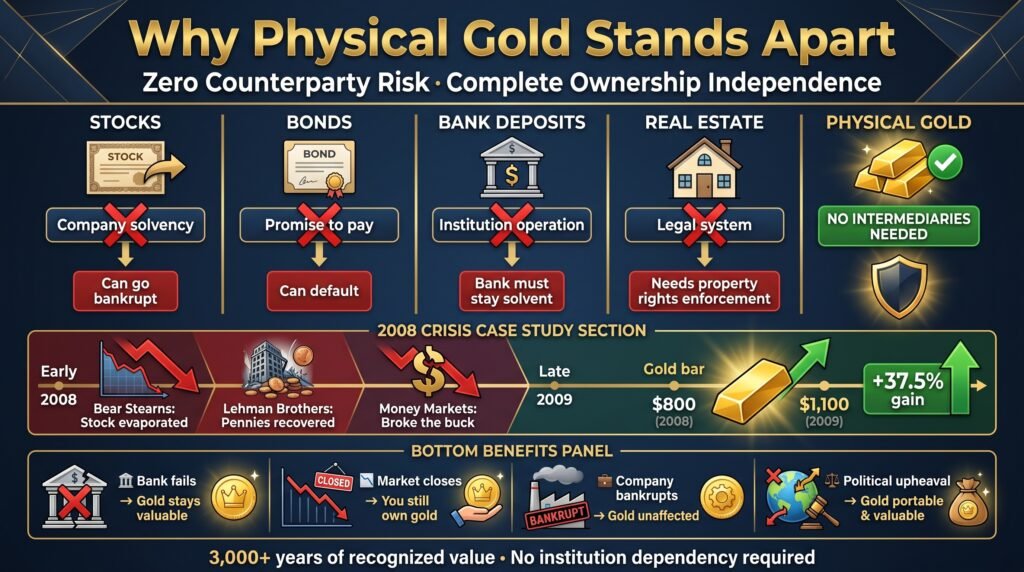
    When investors start treating it like a momentum play or a get-rich-quick scheme, they transform what should be a stabilizing force into a source of unnecessary volatility and disappointment.

    The basic problem with chasing gold prices comes from the timing and the psychology that drives late-stage buying decisions.

    The obsession with timing entries and exits, predicting price spikes, and trading around market sentiment has led countless people to miss the actual point of owning this metal.

    The question “When should I buy gold?” fundamentally misunderstands what gold actually does in your financial life.

    The recent prevailing narrative treats gold like a momentum stock or cryptocurrency, something you jump in and out of based on technical charts and analyst predictions.

    Gold serves a completely different function than growth assets, and trying to trade it like one represents a basic category error that costs investors real money and genuine protection when they need it most.

    Reason 2. Gold Investing Requires a Deeper Understanding of the Investing Landscape

    Gold can best be characterized as wealth insurance. A long-held philosophy of gold ownership is ‘You don’t own gold to get rich. You own gold to keep from going broke.’

    On the contrary, I imagine investors who bought gold in 2023 in the $2000 range have benefited greatly from the price appreciation.

    However, you simply do not wait until the cost of insurance is at record highs to finally insure the car or house. That would be irrational. Correct? Well, the same goes for your wealth.
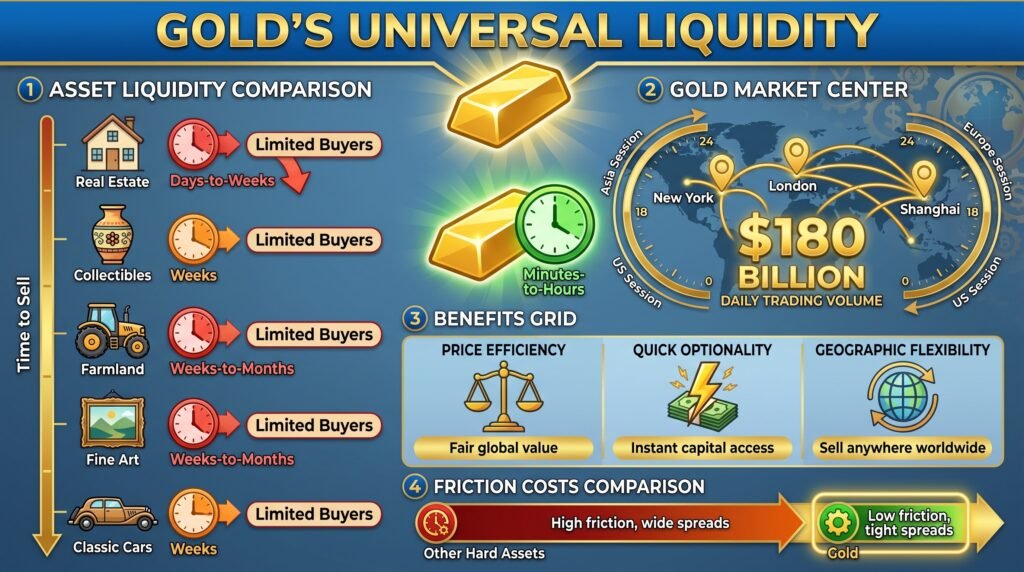
    The real question shouldn’t be ‘Will the gold price continue rising?’ The real questions are: ‘Will the dollar continue to lose value?’ ‘Are we in an inflationary or stagflationary currency environment?’, ‘Is there continued economic uncertainty?’, ‘Is there global conflict and geopolitical instability?’ ‘Will the national debt and monetary expansion continue to grow?’
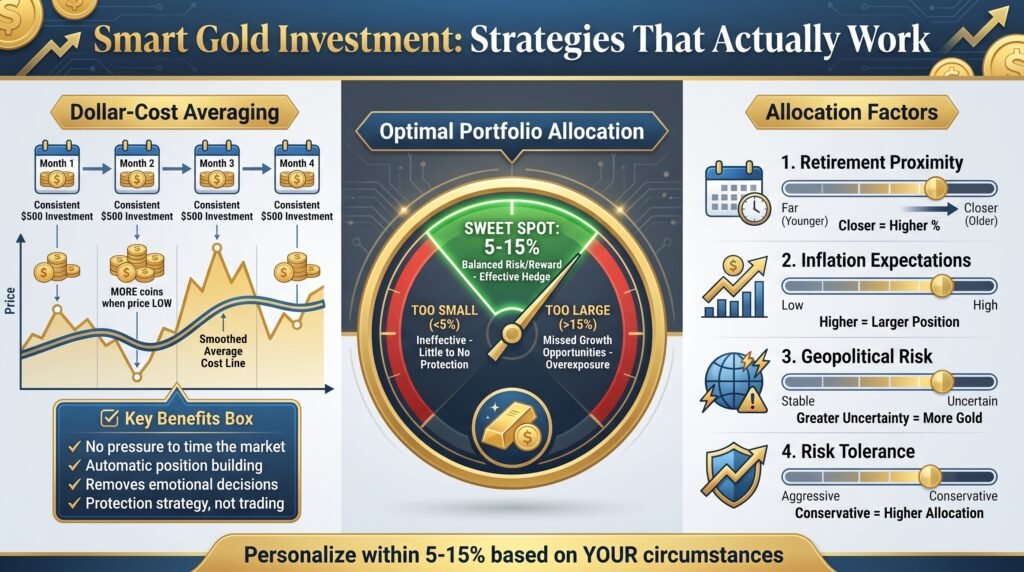
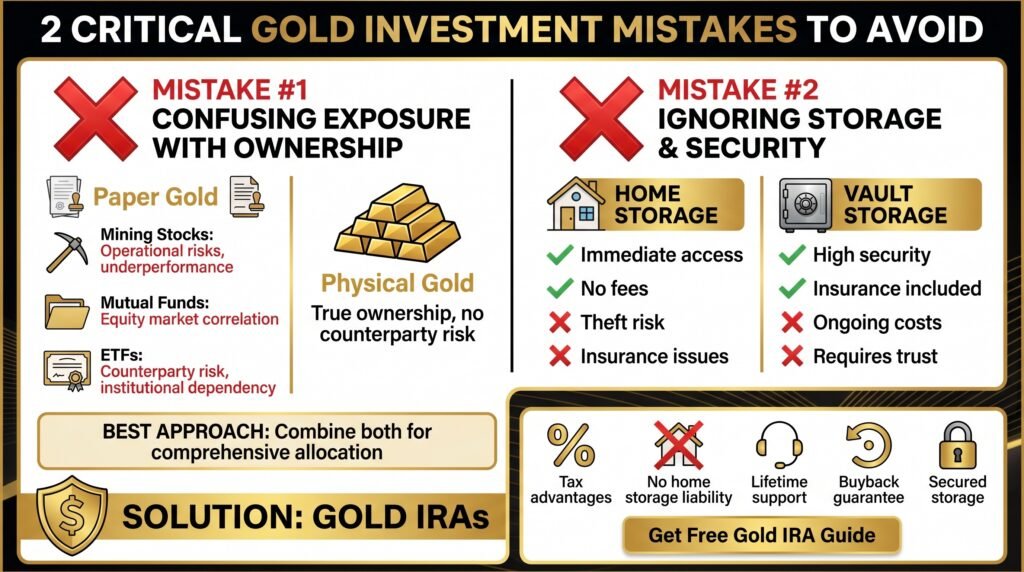
    If you said yes to a majority of these questions, then the question of whether gold prices will continue to rise answers itself. In the affirmative. How fast or slow depends on the momentum of the answers from those prior questions.

    Two more crucial questions should settle the matter. First, from a long view of history, how many fiat currencies have lost significant value, have gone to zero, or gone negative? Feel free to Google that one now. Secondly, how many times has gold gone to zero? You will not need to Google that answer.

    Reason 3 -  Understanding Gold's Strategic Purpose
    Reason 3 – Understanding Gold’s Strategic Purpose

    Reason 3. Understanding Gold’s Strategic Purpose

    The distinction between speculation and strategic positioning might seem subtle, but these represent entirely different philosophies of investing. When you speculate on gold prices, you’re essentially making a bet on short-term market movements driven by sentiment, technical factors, and timing.

    This approach needs you to be right twice, when you buy and when you sell, and it positions gold as just another tradable instrument in your portfolio.

    Strategic gold ownership operates from a radically different premise. You’re acknowledging certain structural realities about modern financial systems.

    Currencies lose purchasing power over time.

    Governments expand money supplies during crises. Geopolitical tensions create financial instability.

    Traditional assets like stocks and bonds sometimes move in synchronized declines.

    The theoretical foundation here draws from decades of academic research on portfolio construction and risk management. Modern Portfolio Theory emphasizes the importance of combining assets with low correlation to reduce overall volatility.

    Gold’s historical behavior during market stress periods provides exactly this characteristic, but only if you own it before the crisis hits.

    Trying to buy gold after stocks have already crashed defeats the entire purpose; you’ve already suffered the equity losses, and you’re now buying protection at elevated prices.

    Reason 4. Making Portfolio Diversification a Priority. Not Price.

    If you are wheel-house as an investor is stocks and risk assets, you may need some guidance with gold investing. Gold is often seen as a ‘boring investment’. Of course, it is. It’s not supposed to be exciting.

    Insurance is bought to protect the sports car; it’s not meant to be as exciting as driving the sports car itself. And you wouldn’t drive that lovely sports car down the crowded highway without insurance, would you?

    However, the steady rise in the gold price in the last 3 years has provided some excitement for those who bought at the right time. They didn’t buy when gold was rocketing up in price. They bought gold because it was time to buy insurance and prepare for any time risk.

    Yes, bonds do provide some hedging protection. But bonds are not a hard asset like precious metals, real estate, fine art, or the like. Bonds also suffer from a similar drawback that stocks suffer from: counterparty risk. That party is the federal government.

    If we were living in a steady environment of fiscal responsibility, national debt solvency, zero inflation, and balanced budgets, then government bonds would probably be the only portfolio hedging asset you would need. But we do not live in this world and do not appear to be entering it at any point soon.

    Regardless of the political party or administration in power, both sides appear to have a steady record and insatiable appetite for overspending. Hence, owning an asset that a counterparty cannot manipulate the supply and value of is of paramount importance.

    Furthermore, certain gold investing vehicles can provide tax-deferred growth. Gold IRAs are a tax-advantaged way of owning physical gold and silver without the need or liability of storing the actual precious metal in your own residence.

    These gold IRA companies provide lifetime customer support, competitive price matches, buyback guarantees, low fees, and secured storage.

    Access Augusta Precious Metals’ free gold IRA checklist by clicking the banner below. Fill out their short form to get started.

    Avoiding Gold Investing Mistakes

    The first major mistake involves confusing gold exposure with gold ownership. Gold mining stocks, gold mutual funds, and gold ETFs all provide price exposure to gold, but they introduce counterparty risk and correlation to equity markets that physical gold ownership avoids.

    Mining stocks often underperform gold itself because of operational challenges, regulatory issues, and general equity market correlation.

    ETFs depend on institutional solvency and proper metal backing.

    These paper gold choices offer advantages in tax-advantaged retirement accounts and provide convenient trading. But they fundamentally differ from direct physical ownership in ways that matter for gold’s core strategic purposes.

    A comprehensive approach might include both physical holdings and paper exposure for different roles within your overall allocation.

    The second mistake involves inadequate attention to storage and security for physical gold. Home storage provides immediate access and eliminates storage fees, but it introduces theft risk and potential insurance complications.

    Professional vault storage offers high security and insurance, but it adds ongoing costs and requires trust in the storage provider.

    The optimal solution depends on position size, the person’s circumstances, and risk preferences.

    Gold IRAs are a tax-advantaged way of owning physical gold and silver without the need or liability of storing the actual precious metal in your own residence.

    These gold IRA companies provide lifetime customer support, competitive price matches, buyback guarantees, low fees, and secured storage. See the links below to find the right gold IRA company that fits your individual needs. Fill out their short contact form and receive a free gold IRA guide.

    Gold IRAs are a tax-advantaged way of owning physical gold and silver without the need or liability of storing the actual precious metal in your own residence.

    These gold IRA companies provide lifetime customer support, competitive price matches, buyback guarantees, low fees, and secured storage. See the links in the video description to find the right gold IRA company that fits your individual needs. Fill out their short contact form and receive a free gold IRA guide.

    The third mistake centers on buying gold from inappropriate sources at excessive premiums. Reputable dealers charge modest premiums over spot prices for standard bullion products.

    Less scrupulous operators charge far higher markups for “rare” or “collectible” coins that don’t offer extra benefits for investment purposes.

    Focus on recognized bullion products, American Eagles, Canadian Maple Leafs, or standard bars, from established dealers with transparent pricing.

    Augusta Precious Metals is a gold IRA company with over a decade in the industry of providing account rollover services. Augusta is one of the leading gold investing companies for trust, customer empowerment, and prices.

    Receive a free gold IRA integrity checklist from their official site by clicking the banner below. Fill out their short contact form to get started.

    Frequently Asked Questions

    Is gold a bad investment?

    No. Gold can serve as a hedge against inflation, economic uncertainty, and currency weakness. However, problems often arise when investors chase rapid price increases or treat gold as a short-term speculation vehicle instead of a long-term portfolio diversifier.

    Why is chasing the gold price risky?

    Gold prices can swing sharply due to changing interest rates, geopolitical tensions, investor sentiment, and currency movements. Investors who buy after large rallies may enter near temporary highs and suffer losses during pullbacks.

    What is the biggest mistake gold investors make?

    One of the biggest mistakes is emotional investing, buying because prices are surging or headlines create fear of missing out. This often leads to buying high and selling low during corrections.

    Is gold better for long-term investing?

    Many investors use gold primarily as a long-term store of value and portfolio hedge rather than a short-term trading asset. Long-term accumulation strategies generally reduce the risks associated with trying to time the market.

    Why doesn’t gold always rise during crises?

    While gold is considered a safe-haven asset, it can still fall during periods of market stress. Investors sometimes sell gold to raise cash, cover losses, or respond to rising interest rates and a stronger U.S. dollar.

    Does gold generate income like stocks or bonds?

    No. Physical gold does not pay dividends or interest. Returns depend entirely on price appreciation, which is why some investors view it as a hedge or insurance asset rather than a growth investment.

    Gold Leases, such as those provided by Monetary Metals, generate a fixed-income return competitive with the interest yield produced by bonds. The company provides a real yield on your gold investment, paid in actual gold. See the link here to learn more.

    Read our full list of reviews of the best gold IRA companies that we have carefully researched and vetted here.

  • Top 5 Real Reasons to Invest in Gold in 2026 (Price is NOT One of Them)

    Top 5 Real Reasons to Invest in Gold in 2026 (Price is NOT One of Them)

    Quick Summary

    Investing in gold is primarily about protecting wealth—not chasing high returns. The metal has historically served as a store of value, helping investors hedge against inflation, currency devaluation, and economic uncertainty. It also provides portfolio diversification, often moving independently from stocks and bonds, which can reduce overall risk.

    Gold becomes especially valuable during market crashes, recessions, and geopolitical instability, where it tends to hold or increase its value while traditional assets decline. Its tangible nature and limited supply further enhance its appeal as a long-term hedge against financial system risks.

    In short, gold isn’t about rapid growth—it’s about preserving purchasing power and stabilizing your portfolio during uncertain times.

    Table of Contents

    1. The Real Reasons Gold Belongs in Your Portfolio
      • Protection Against Currency Destruction
      • Uncorrelated Performance During Market Stress
      • Ownership Without Institutional Dependency or Counterparty Risk
      • Historical Crisis Performance
      • Universal Acceptance and Deep Liquidity
    2. Implementation Strategies That Actually Work
    3. Wealth Insurance Investing
    4. Key Takeaways
    5. Frequently Asked Questions

    The Real Reasons Gold Belongs in Your Portfolio

    1. Protection Against Currency Destruction

    The mathematical reality of fiat currency is straightforward. Governments can create unlimited amounts of it. This is literally how modern monetary systems function.

    When you hold dollars, euros, or any other paper currency, you own a claim on purchasing power that governments can dilute by expanding the money supply.

    Gold provides a counterbalance to this structural dynamic because of basic geology and economics. All the gold ever mined throughout human history would fit in a cube roughly 22 meters on each side.

    New gold production adds only about 1-2% to the total supply annually, constrained by the difficulty and expense of mining.

    This scarcity doesn’t depend on policy or government promises. Planetary formation billions of years ago determined it.

    The purchasing power comparison becomes stark when you examine long timeframes.

    In 1913, before the Federal Reserve’s creation, a $20 bill and a one-ounce gold coin (also worth $20 at the time) had equivalent value. Today, that same paper $20 buys considerably less than it did then, while the gold coin is worth well over $3,000.

    The gold maintained its purchasing power. The currency did not.

    This matters enormously for retirees living on savings accumulated over decades of work. If you’ve spent 30-40 years building a nest egg, currency debasement can silently erode that purchasing power even if your account balance looks stable.

    A portfolio allocation to gold directly addresses this risk without requiring you to forecast when inflation will accelerate or which policies will debase the currency.

    The protection operates continuously, quietly maintaining value while paper assets fluctuate.

    2. Uncorrelated Performance During Market Stress

    Most diversification strategies fail when you need them most because assets that normally move independently suddenly correlate during crises. Stocks and corporate bonds both declined in 2008 because both depend on corporate profitability and credit availability.

    Real estate and stocks both suffered because both depend on economic growth and credit conditions.

    Even international stocks provide less diversification than many realize because global equity markets increasingly move together.

    Gold genuinely behaves differently because it responds to different drivers. When stock markets decline because of recession fears, gold often rises as investors seek safety.

    When bond yields fall during flight-to-quality episodes, gold appreciates alongside them.

    When both stocks and bonds struggle during stagflation periods like the 1970s, gold can surge while traditional assets languish.

    The mechanism behind this low correlation relates to gold’s role as a monetary choice as opposed to a productive asset. Stocks and bonds represent claims on future cash flows generated by economic activity.

    Real estate generates rental income.

    These assets all join in the economic cycle.

    Gold doesn’t generate cash flows; it simply exists as a scarce, universally recognized store of value. However, we will discuss a means of investing in gold that does generate a yield very soon.

    This basic difference creates the diversification benefit.

    Research examining multi-decade periods confirms that adding gold allocations of 5-15% to traditional stock/bond portfolios reduces overall volatility while maintaining comparable returns. The mathematics work because gold’s independent price behavior smooths the portfolio’s total fluctuation.

    During periods when stocks surge, the gold allocation might lag, but during market crashes, gold’s stability or appreciation offsets equity losses.

    A common objection to gold and silver ownership is the opportunity cost of potential gains in the aforementioned risk assets.

    The answer to this is gold and silver leases. Gold and silver leases provide investors with the opportunity to gain a competitive interest rate that matches or exceeds the yield on bonds. Monetary Metals is a gold investment company that delivers a real interest yield on gold, paid in actual gold. 

    Click the banner below to learn more about Monetary Metals’ fixed-income products, and get started earning a competitive interest rate in addition to gold’s natural price appreciation. Fill out their short contact form to get started.

    3. Ownership Without Institutional Dependency or Counterparty Risk

    This characteristic deserves more attention than it typically receives. When you own physical gold coins or bars, you possess an asset that doesn’t depend on anyone else’s solvency, honesty, or competence.

    No counterparty can fail to deliver, no institution that must remain solvent, no government that must honor obligations.

    Compare this to stocks, which represent partial ownership in companies that can go bankrupt. Or bonds, which are promises to pay that can default. Or bank deposits, which depend on the bank’s continued operation and the deposit insurance system’s funding.

    Or even real estate, which needs enforceable property rights and a functioning legal system to maintain title.

    Physical gold needs none of these intermediaries. The metal itself has intrinsic value recognized globally for thousands of years.

    If your bank fails, your gold stays valuable.

    If the stock market closes during a crisis, you still own your gold. If a company goes bankrupt, your gold is unaffected. If political upheaval disrupts property rights, gold stays portable and valuable.

    The 2008 financial crisis illustrated this distinction vividly. Bear Stearns shareholders watched their stock value evaporate.

    Lehman Brothers bondholders recovered pennies on the dollar. Money market funds “broke the buck,” returning less than investors deposited.

    Meanwhile, physical gold owners simply held an asset whose value actually increased during the chaos, rising from around $800 in early 2008 to over $1,100 by late 2009.

    This counterparty-free characteristic provides psychological benefits that extend beyond mathematical portfolio optimization.

    During market turmoil, when headlines scream about bank failures and corporate bankruptcies, physical gold ownership offers genuine peace of mind.

    You’re not wondering whether some institution will honor its obligations; you hold direct ownership of a globally recognized asset.

    4. Historical Crisis Performance

    Gold’s safe-haven reputation comes from documented performance across many crisis types. The pattern repeats consistently.

    When uncertainty rises and traditional assets stumble, gold tends to appreciate or at least maintain value.

    The 1970s stagflation period provides a particularly relevant case study for today’s environment. As oil shocks drove inflation higher and economic growth stagnated, stocks and bonds both struggled. The traditional 60/40 portfolio suffered meaningful losses in real terms.

    Gold, meanwhile, surged from $35 per ounce in 1971 to over $800 by 1980, preserving and growing purchasing power while other assets floundered.

    The 2008 financial crisis demonstrated gold’s crisis characteristics from a different angle. The initial market panic actually saw gold decline slightly alongside everything else as investors liquidated positions to meet margin calls.

    But as the crisis deepened and central banks responded with unprecedented monetary expansion, gold began a multi-year rally that nearly doubled prices between 2008 and 2011.

    Investors who owned gold before the crisis began enjoyed protection that late buyers missed.

    More recently, the COVID-19 pandemic created a sharp test of gold’s defensive properties. In the initial market crash of March 2020, the S&P 500 fell nearly 34% from peak to trough.

    Gold initially declined modestly but quickly recovered and pushed to new all-time highs above $2,000 per ounce by August 2020.

    The divergent performance provided exactly the diversification benefit that strategic gold positions deliver.

    Today, you are seeing massive gains in gold and silver as concerns about the dollar’s long-term solvency, the US national debt and deficits, and countries’ drawdown of US bonds start to grow.

    Also, the increasing mass accumulations of gold bullion by world central banks that have remained steady for the last 10 years have provided a stable floor under the gold price.

    5. Universal Acceptance and Deep Liquidity

    Some assets offer excellent theoretical characteristics but lack practical liquidity when you actually need to transact. Collectibles might hold value, but finding buyers takes time.

    Certain real estate can be difficult to sell quickly.

    Even some financial instruments have limited markets with wide bid-ask spreads.

    Gold operates in a different universe entirely. The global gold market trades over $180 billion daily across many time zones and continents.

    London, New York, Shanghai, and other financial centers maintain continuous markets with transparent pricing and large liquidity.

    This depth means you can buy or sell meaningful positions without materially affecting the price or accepting unfavorable terms.

    The practical implications extend beyond just trading convenience. Universal liquidity creates price efficiency, ensuring you receive fair value based on global market conditions as opposed to local supply constraints.

    It provides optionality, allowing you to access capital quickly if circumstances change.

    And it offers geographic flexibility, since gold’s global recognition means you can sell in any major city worldwide.

    This liquidity characteristic distinguishes gold from other hard assets often proposed as inflation hedges. Farmland might protect against inflation, but selling acreage quickly at fair prices presents challenges.

    Classic cars or fine art might appreciate, but finding qualified buyers willing to pay full value needs time and effort.

    Gold’s liquidity eliminates these friction costs.

    Implementation Strategies That Actually Work

    Dollar-cost averaging provides the most straightforward approach for most investors. Rather than attempting a single perfectly-timed purchase, you commit to buying fixed dollar amounts at regular intervals, perhaps monthly or quarterly.

    This method automatically buys more ounces when prices are lower and fewer when prices are higher, smoothing your average cost over time.

    The psychological advantage of dollar-cost averaging shouldn’t be underestimated. You eliminate the pressure to forecast market bottoms or worry about buying before a correction. Instead, you’re systematically building a position regardless of short-term price movements.

    This aligns perfectly with gold’s strategic purpose; you’re gradually establishing protection, not trying to trade it.

    Portfolio allocation percentages need personal consideration based on your specific circumstances, but the 5-15% range appears in recommendations from various financial institutions and advisors for good reasons.

    Below 5%, the position may be too small to provide meaningful diversification benefits during market stress.

    Above 15%, you’re potentially allocating too much to a non-yielding asset at the expense of growth opportunities.

    Your allocation within that range should reflect several factors. Proximity to retirement matters; a closer retirement might justify higher allocations for protection.

    Inflation concerns play a role; higher inflation expectations support larger positions.

    Geopolitical risk assessment factors in, and greater uncertainty argues for more defensive positioning. Overall risk tolerance influences the decision; conservative investors might prefer higher gold allocations.

    Avoiding Common Implementation Mistakes

    The first major mistake involves confusing gold exposure with gold ownership. Gold mining stocks, gold mutual funds, and gold ETFs all provide price exposure to gold, but they introduce counterparty risk and correlation to equity markets that physical gold ownership avoids.

    Mining stocks often underperform gold itself because of operational challenges, regulatory issues, and general equity market correlation.

    ETFs depend on institutional solvency and proper metal backing.

    These paper gold choices offer advantages in tax-advantaged retirement accounts and provide convenient trading. But they fundamentally differ from direct physical ownership in ways that matter for gold’s core strategic purposes.

    A comprehensive approach might include both physical holdings and paper exposure for different roles within your overall allocation.

    The second mistake involves inadequate attention to storage and security for physical gold. Home storage provides immediate access and eliminates storage fees, but it introduces theft risk and potential insurance complications.

    Professional vault storage offers high security and insurance, but it adds ongoing costs and requires trust in the storage provider.

    The optimal solution depends on position size, the person’s circumstances, and risk preferences.

    Gold IRAs are a tax-advantaged way of owning physical gold and silver without the need or liability of storing the actual precious metal in your own residence.

    These gold IRA companies provide lifetime customer support, competitive price matches, buyback guarantees, low fees, and secured storage. See the links below to find the right gold IRA company that fits your individual needs. Fill out their short contact form and receive a free gold IRA guide.

    Gold IRAs are a tax-advantaged way of owning physical gold and silver without the need or liability of storing the actual precious metal in your own residence.

    These gold IRA companies provide lifetime customer support, competitive price matches, buyback guarantees, low fees, and secured storage. See the links in the video description to find the right gold IRA company that fits your individual needs. Fill out their short contact form and receive a free gold IRA guide.

    The third mistake centers on buying gold from inappropriate sources at excessive premiums. Reputable dealers charge modest premiums over spot prices for standard bullion products.

    Less scrupulous operators charge far higher markups for “rare” or “collectible” coins that don’t offer extra benefits for investment purposes.

    Focus on recognized bullion products, American Eagles, Canadian Maple Leafs, or standard bars, from established dealers with transparent pricing.

    Augusta Precious Metals is a gold IRA company with over a decade in the industry of providing account rollover services. Augusta is one of the leading gold investing companies for trust, customer empowerment, and prices.

    Click the banner below to receive a free gold IRA integrity checklist from their official site. Fill out their sort contact form to get started.

    Read our full list of reviews of the best gold IRA companies that we have carefully researched and vetted here.

    Wealth Insurance Investing

    Gold’s value in your portfolio has nothing to do with predicting price movements. The metal maintains purchasing power, reduces correlation to traditional assets, eliminates counterparty risk, provides crisis protection, and confirms liquidity.

    Trying to time gold purchases represents a basic misunderstanding of its strategic purpose.

    Implementation through dollar-cost averaging at suitable allocation percentages (5-15% depending on a person’s circumstances) provides the practical approach that aligns with gold’s characteristics. Physical ownership offers the final benefit set that paper choices can’t fully replicate, though both may play roles in a comprehensive strategy.

    The investment sophistication required to use gold properly involves recognizing that some assets exist for protection, diversification, and wealth preservation across generations as opposed to growth. Mastering this distinction elevates your entire approach to portfolio construction beyond simple return chasing toward genuine risk management.

    Key Takeaways

    Gold’s value in your portfolio has nothing to do with predicting price movements. The metal maintains purchasing power, reduces correlation to traditional assets, eliminates counterparty risk, provides crisis protection, and confirms liquidity.

    Trying to time gold purchases represents a basic misunderstanding of its strategic purpose.

    Implementation through dollar-cost averaging at suitable allocation percentages (5-15% depending on a person’s circumstances) provides the practical approach that aligns with gold’s characteristics. Physical ownership offers the final benefit set that paper choices can’t fully replicate, though both may play roles in a comprehensive strategy.

    The investment sophistication required to use gold properly involves recognizing that some assets exist for protection, diversification, and wealth preservation across generations as opposed to growth. Mastering this distinction elevates your entire approach to portfolio construction beyond simple return chasing toward genuine risk management.

    To get started on your gold investing journey, obtain a free investment guide from one of the gold IRA companies below. Whether you require a company with a low investment minimum to get started or are a serious investor with a larger portfolio to protect, a tax-advantaged gold IRA is a great vehicle to own physical gold without the need or liability of storage within your own home.

    Augusta Precious Metals: Best Gold IRA Company for Prices, Education, and Lifetime Customer Support. $50,000 Minimum.

    Birch Gold Group: Most Trusted Customer Service, Low Investment Minimums, and Low Fees. $10,000 Minimum

    Click the right banner for your individual needs. Fill out their short contact form on their site to get started.

    Birch Gold IRA Guide
    Birch Gold IRA Guide
    Free Gold IRA Guide

    Frequently Asked Questions

    Can gold protect against inflation?

    Gold has historically maintained purchasing power during inflationary periods. The 1970s provide the clearest example, when inflation averaged over 7% annually, and gold surged from $35 to over $800 per ounce.

    More recently, during the 2021-2023 inflation spike, gold appreciated meaningfully while bond portfolios suffered losses.

    The protection mechanism works because gold’s supply increases slowly (only 1-2% annually from mining) while fiat currency supplies can expand rapidly.

    Should I buy physical gold or gold ETFs?

    Physical gold provides final ownership without counterparty risk, making it ideal for the strategic protection role discussed throughout this article.

    Gold ETFs offer convenience and work well in retirement accounts where physical ownership presents challenges.
    Many investors use both physical holdings for core strategic positions and ETFs for tactical allocations or retirement account exposure.

    The choice depends on your specific goals and circumstances.

    How much gold should I own in my portfolio?

    Most financial advisors and institutions recommend allocations between 5-15% of total portfolio value. Below 5%, the position may not provide meaningful protection during market stress.

    Above 15%, you’re potentially sacrificing too much growth potential from productive assets.

    Your specific allocation within that range should reflect your proximity to retirement, inflation concerns, risk tolerance, and overall financial situation.

    Is now a good time to buy gold?

    This question reflects the timing mindset that misses Gold’s strategic purpose. The relevant question focuses on whether you now have adequate protection against currency debasement, market volatility, and systemic risks.

    If you don’t have a gold position matching your target allocation, then yes, now is a suitable time to begin building one through dollar-cost averaging.

    If you already maintain your target allocation, then no extra purchases are needed regardless of current prices.

    Does gold pay dividends or interest?

    Unless you are investing in a gold lease, gold generates no income, which represents one of its key characteristics as opposed to a weakness. Assets that generate cash flows, such as stocks, bonds, and rental properties, depend on economic activity and institutional functioning.

    Gold’s value doesn’t need corporate profits, interest payments, or rental income.

    This independence from cash flow generation provides the diversification benefit that makes gold valuable for portfolio protection as opposed to growth.

    To get started on your gold investing journey, obtain a free investment guide from one of the gold IRA companies below. Whether you require a company with a low investment minimum to get started or are a serious investor with a larger portfolio to protect, a tax-advantaged gold IRA is a great vehicle to own physical gold without the need or liability of storage within your own home.

    Click the right banner for your individual needs. Fill out their short contact form on their site to get started.

    BIRCH GOLD GROUP - Free GOLD IRA KIT
    BIRCH GOLD GROUP – Free GOLD IRA KIT

  • Is Gold Still Worth It? War, Oil, Your Money, and Gold Investing in 2026

    Is Gold Still Worth It? War, Oil, Your Money, and Gold Investing in 2026

    Is Gold Still Worth It? War, Oil, and Your Money in 2026
    Is Gold Still Worth It? War, Oil, and Your Money in 2026

    Quick Summary

    Gold isn’t behaving like a traditional “safe haven” during the current war and oil shock. Prices can fall—even during crises—because gold is driven by liquidity, interest rates, and global capital flows, not just fear.

    A surge in oil prices is fueling inflation and higher interest rates, which hurts gold since it doesn’t produce yield.  Central banks and countries may sell gold to cover economic stress, reducing demand and pushing prices down.

    Gold still has a long-term role as a hedge, but short-term performance can be volatile and counterintuitive. Depending on the duration of the conflict and the level of central bank support in the form of monetary easing and money supply expansion, the longer-term price action of gold.

    Introduction

    Is gold still worth it? Like all things, it’s all about timing and context.

     “One of the strongest arguments for gold is that it acts as a hedge against geopolitical instability, wars, fragmentation, and loss of trust between countries.

    In those environments, investors look for assets that aren’t tied to any one government, and gold fits that role. It’s a neutral asset.

    But what’s interesting, and often misunderstood, is that gold doesn’t just go up every time there’s a crisis.

    You can actually see situations where geopolitical tensions rise, and gold initially spikes… but then either levels off or even declines.

    And that’s because gold isn’t just reacting to fear; it’s mainly reacting to variables like interest rates, the dollar, liquidity, and the world central bank’s reaction to the conflict.

    So even if a conflict increases uncertainty, if it also leads to higher real rates or a stronger dollar, that can offset or even overwhelm the bullish impact on gold.

    Which means the relationship between geopolitics and gold is real, but it’s not simple, and it’s definitely not one-directional.”

    The recent events of March 2026 perfectly illustrate this exact point:

    • Gold initially surged when the Middle East conflict escalated.
      → Early reaction: safe-haven buying.
    • But then gold fell sharply despite the ongoing war. Down 13–15% after the conflict began
    • Why? Because:
      • Rising oil → higher inflation expectations. But not Monetary inflation,
      • Central banks stay tighter with higher rates.
      • This leads to a Stronger dollar plus higher real yields
      • This leads to downward Pressure on gold.


    Geopolitics alone doesn’t drive gold. Macro conditions determine whether the move sticks.

     “Gold doesn’t just trade on fear — it trades on the macro response to that fear.”

    Scenario 1 – Limited / Contained Conflict

    What happens:

    • Conflict remains regional with no major escalation.
    • Markets initially react with fear and then normalize.
    • Oil may spike briefly, then stabilize.

    Macro response:

    • Central banks stay cautious or slightly hawkish.
    • Real rates remain stable or slightly elevated.
    • USD stays relatively strong.

    🪙 Gold reaction:

    • Initial spike due to safe-haven demand.
    • Then plateaus or pulls back.

     “Fear alone isn’t enough — if rates stay high, gold struggles.”e to that fear.”

    Scenario 2 – Major Escalation – Regional War Expansion

    What happens:

    • Broader Middle East involvement.
    • Oil supply disruption is leading to a sharp spike in energy prices.
    • Global uncertainty increases significantly.

    Macro response leads to two possible paths…

    Path A –  Inflation Shock plus Tight Policy

    • Oil-driven inflation rises.
    • Central banks stay tighter for longer.
    • Real rates rise or stay elevated.

    👉 Gold Outcome..

    • Short-term surge.
    • Then suppressed or volatile.

    Path B: Crisis leads to a Central Bank Policy Pivot.

    • Growth slows sharply.
    • Financial stress emerges.
    • Central banks cut rates and inject liquidity.

    👉 Gold Outcome:

    Sustained a strong rally.

    Escalation helps gold only if it leads to easier monetary policy. The easing essentially increases the monetary supply, leading to inflation.

    Scenario 3 – Global Financial Spillover – This is the true “gold bull” scenario.

    What happens:

    • War triggers:
      • Banking stress.
      • Credit tightening.
      • Market instability.

    Macro response:

    Real rates fall (or go negative).

    Central banks intervene aggressively.

    Liquidity increases through QE or money printing.

    🪙 Gold reaction:

    • Strong, sustained upside.

    🎯 Key takeaway:

    This is where gold behaves exactly as advertised, as a system hedge.

    Scenario 4 – De-escalation – A Sustained Peace Resolution.

    What happens:

    • Tensions ease.
    • Oil prices fall.
    • Risk sentiment improves.

    Macro response:

    • Inflation expectations decline.
    • Real rates may stabilize or rise.
    • Risk assets outperform.

    Gold reaction:

    • Gradual decline or underperformance.

    Key takeaway:

    Gold loses its “insurance premium” when fear fades.

    A Simplified Cheat Sheet.

    1. A contained conflict equals a gold spike, then fades.
    2. An escalation with tight monetary policy equals a volatile and capped gold price.
    3. An escalation with a tight monetary policy pivot equals a strong rally for gold.
    4. De-escalation of conflict equals a gradual decline and evening out of the gold price.

    Whichever of these scenarios is likely will largely depend on the duration and the amount of liquidity and national debt resulting from money supply growth.

    “Gold reacts less to the war itself… and more to how central banks respond to it.”

    To take advantage of the volatility of gold and silver before their eventual resurgence.

    Gold and silver IRAs are a tax-advantaged means of owning physical gold without the need or potential liability of storing the precious metal in your own residence. Gold IRA companies provide competitive price matches, lifetime customer service, secured storage, and solid buyback guarantees for their clients.

    Read the full list of reviews of the best gold IRA companies that we have carefully researched and vetted here.

    Augusta Precious Metals is a gold IRA company with over a decade in the industry of providing account rollover services. Augusta is one of the leading gold investing companies for trust, customer empowerment, and prices.

    Click the banner below to receive a free gold IRA integrity checklist from their official site. Fill out their short contact form to get started.

    Why War Doesn’t Immediately Send Gold Higher

    Many investors think war automatically sends gold higher. But that’s not actually how it works.

    According to a macro investor named Luke Gromen: Gold doesn’t react to war…It reacts to what central banks do because of war.

    Here’s the chain reaction:

    War breaks out, governments spend massively, and deficits explode. Now, central banks have a problem: They can’t let interest rates rise too much…
    Or the system breaks under the debt.

    So, what do they do? They step in, add liquidity, and expand the money supply.

    But here’s the part most people miss: At first, war pushes oil higher, which drives inflation, which keeps the central bank’s monetary policy tight, so gold might actually stall or even drop early on.

    The real move happens later. When markets realize: Central banks have to ease… and the money supply starts expanding. That’s when gold tends to break out in a big way.

    So, the takeaway is simple: War doesn’t drive gold…Money printing does.

    Phase 1, War Breaks Out, and Central Banks Are Forced to Respond

    When global conflict escalates, Governments increase spending on defense, Energy security, Supply chains, and Alliances to provide aid. This creates large fiscal deficits

    According to Gromen, central banks don’t operate independently in these scenarios.

    They are effectively forced to:

    • Keep interest rates from rising too much.
    • Ensure government debt remains fundable.
    • Maintain financial system stability.

    👉 This often leads to:

    • Debt monetization, direct or indirect.
    • Balance sheet expansion.
    • Liquidity injections.

    Phase 2 – Money Supply Expands

    This is the key pivot – War leads to deficits, then monetization and the resulting money printing.

    Even if not explicit Q.E., it can show up as: Yield curve control, implicitly. The creation of Bank liquidity programs and/ or Treasury issuance is absorbed by the system.

    Phase 3 – Downstream Inflation Effects

    This creates two layers of inflation:

    1. Immediate – Supply Shock.

    • Oil spikes.
    • Commodity prices rise.
    • Input costs increase.

    👉 This is oil-driven inflation. Often bad for gold in the short term.

    2. Secondary – Monetary Inflation.

    • Currency supply expands.
    • Real purchasing power declines.
    • Confidence in fiat weakens.

    👉 This is monetary inflation, which is very bullish for gold.

    To get started on your gold investing journey, obtain a free investment guide from one of the gold IRA companies below. Whether you require a company with a low investment minimum to get started or are a serious investor with a larger portfolio to protect, a tax-advantaged gold IRA is a great vehicle to own physical gold without the need or liability of storage within your own home.

    Click the right banner for your individual needs. Fill out their short contact form on their site to get started.

    BIRCH GOLD GROUP - Free GOLD IRA KIT
    BIRCH GOLD GROUP – Free GOLD IRA KIT

    Gold’s Role and Timeline of Gold Reaction

    Gold doesn’t respond to the war itself; it responds to the policy response to the war.

    Phase 1: Shock.

    • War begins.
    • Oil spikes.
    • Rate expectations rise.

    👉 Gold is volatile and mixed.


    Phase 2: Policy Constraint

    • Governments can’t afford high rates.
    • Financial stress builds.

    👉 Markets begin to anticipate:

    • Intervention.
    • Liquidity support.

    👉 Gold starts to stabilize.


    Phase 3: Monetary Expansion

    • Central banks ease – explicitly or implicitly.
    • Money supply grows.

    👉 Gold = strong, sustained rally.

     “Gold is driven by real rates, liquidity, and macro response — not just geopolitics.”

    Gromen’s view is essentially the endgame of that logic:

    • Geopolitics forces policy.
    • Policy drives liquidity.
    • Liquidity drives gold.

    Tie-In to Gold–Oil Ratio –  A Critical Connection

    This is where it all clicks:

    Early War Phase:

    • Oil rises in price.
    • Gold rises, but not as much as oil.

    The Ratio falls; gold appears weak.

    Later Phase (Gromen Scenario):

    • Money supply rises.
    • Real rates are down.
    • Gold increases.
    • Oil stabilizes or falls.

    Ratio rises; true gold bull phase begins.

    Conclusion

    In summary, Gromen’s Big Macro Bet, if you condense his view:

    The U.S. and global system cannot sustain: High debt, High rates, AND geopolitical conflict. Something has to give…And that “something” is: Currency value declines due to money supply expansion

    Again, “War doesn’t just create inflation — it forces the system to print, and that’s when gold really moves.

    Another factor, the geopolitical fallout of the large US military interventions and the resulting divestment in the dollar, plays into the bullish case for gold.

    With increasing geopolitical tensions, the desire by world governments and central banks to seek a neutral asset that does not carry the same counterparty risk as the US dollar will become more and more a priority. Only time will tell.

    But waiting is not an option as an investor. Preparation is. And one rule has remained true and constant over 5,000 years: gold has never gone to zero. Currencies have.

    To take advantage of the volatility of gold and silver before their eventual resurgence, see the links below to obtain a free guide from either Birch Gold Group or Augusta Precious Metals. Fill out their short contact form on their site to get started.

    Best Gold IRA for Low Investment Minimums and Fees

    Birch Gold IRA Guide
    Birch Gold IRA Guide

    Best Gold IRA for Prices, Customer Support, & Education

    Gold and Silver IRA Info Kit
    Gold and Silver IRA Info Kit

    Frequently Asked Questions

    Is gold still a good investment in 2026?

    Gold can still play a role as a long-term hedge against inflation and uncertainty, but it’s not reliable in the short term. Its performance depends heavily on interest rates, the dollar, and global liquidity—not just geopolitical events.

    Why is gold falling during a war?

    Because markets are reacting to economic mechanics, not headlines. Rising oil prices increase inflation and interest rates, which reduces gold’s appeal. At the same time, investors and governments may sell gold to raise cash.

    Does gold always go up during crises?

    No. While gold often rises during uncertainty, it can fall if:
    Interest rates rise
    The U.S. dollar strengthens
    Investors need liquidity
    These factors can outweigh the “fear trade.”

    How do interest rates affect gold?

    Gold doesn’t pay income. When interest rates rise, bonds and cash become more attractive, pulling money away from gold.

    However, gold leases provide a competitive interest yield that is equal to or greater than interest earned on bonds.

    What role do central banks play in gold prices?

    Central banks are major buyers of gold, but during economic stress they may:
    Slow purchases
    Sell reserves
    This shift in demand can significantly impact prices.

    Is gold better than stocks or bonds?

    Not necessarily. Gold:
    –Doesn’t generate income
    -Relies on price appreciation alone

    However, gold leases provide a competitive interest yield that is equal to or greater than the interest earned on bonds.

    Stocks and bonds provide returns through earnings or interest, making them more productive assets over time.

    Should you hold gold in your portfolio?

    Yes—in moderation. Gold works best as:
    A diversification tool. Average holding for hedging is 10%.
    A hedge against extreme scenarios
    But relying on it, or any single asset class alone, as a primary investment strategy is risky.

    What’s the biggest misconception about gold?

    That it always rises during a crisis. In reality, gold follows liquidity and macroeconomic conditions, which can cause it to drop even when fear is high.

  • Hello world!

    Welcome to WordPress. This is your first post. Edit or delete it, then start writing!