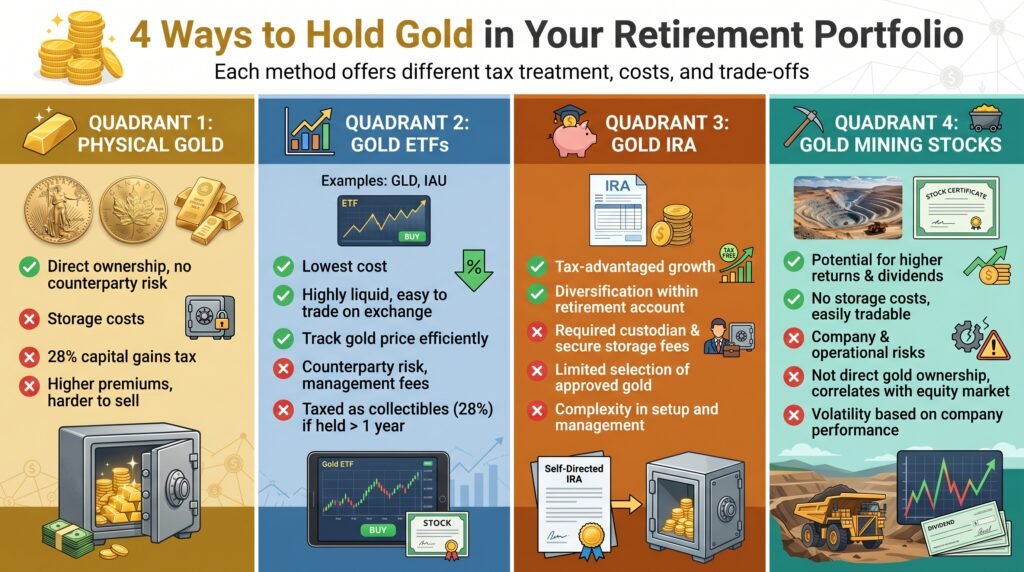
Author: Adam ONeill

  • How Much Silver Should Be in a Retirement Portfolio? 2026 Guide

    How Much Silver Should Be in a Retirement Portfolio? 2026 Guide

    How Much Silver Should Be in a Retirement Portfolio?
    How Much Silver Should Be in a Retirement Portfolio?

    Quick Summary

    • Most financial experts recommend keeping silver to just 5%-10% of your total retirement portfolio, not a core holding but a diversification tool.
    • Silver’s price surged 144.8% in 2025 alone, proving its volatility can work in your favor during the right market conditions.
    • The gold-to-silver ratio gives you a built-in signal for when silver is cheap relative to gold, helping you time purchases smarter.
    • Working with an established partner like Augusta Precious Metals can help you navigate IRA rules and avoid costly mistakes when adding physical silver to retirement accounts.
    • Silver behaves differently than gold because industrial demand from solar panels and electric vehicles plays a massive role in its price swings, something we’ll break down later in this guide.

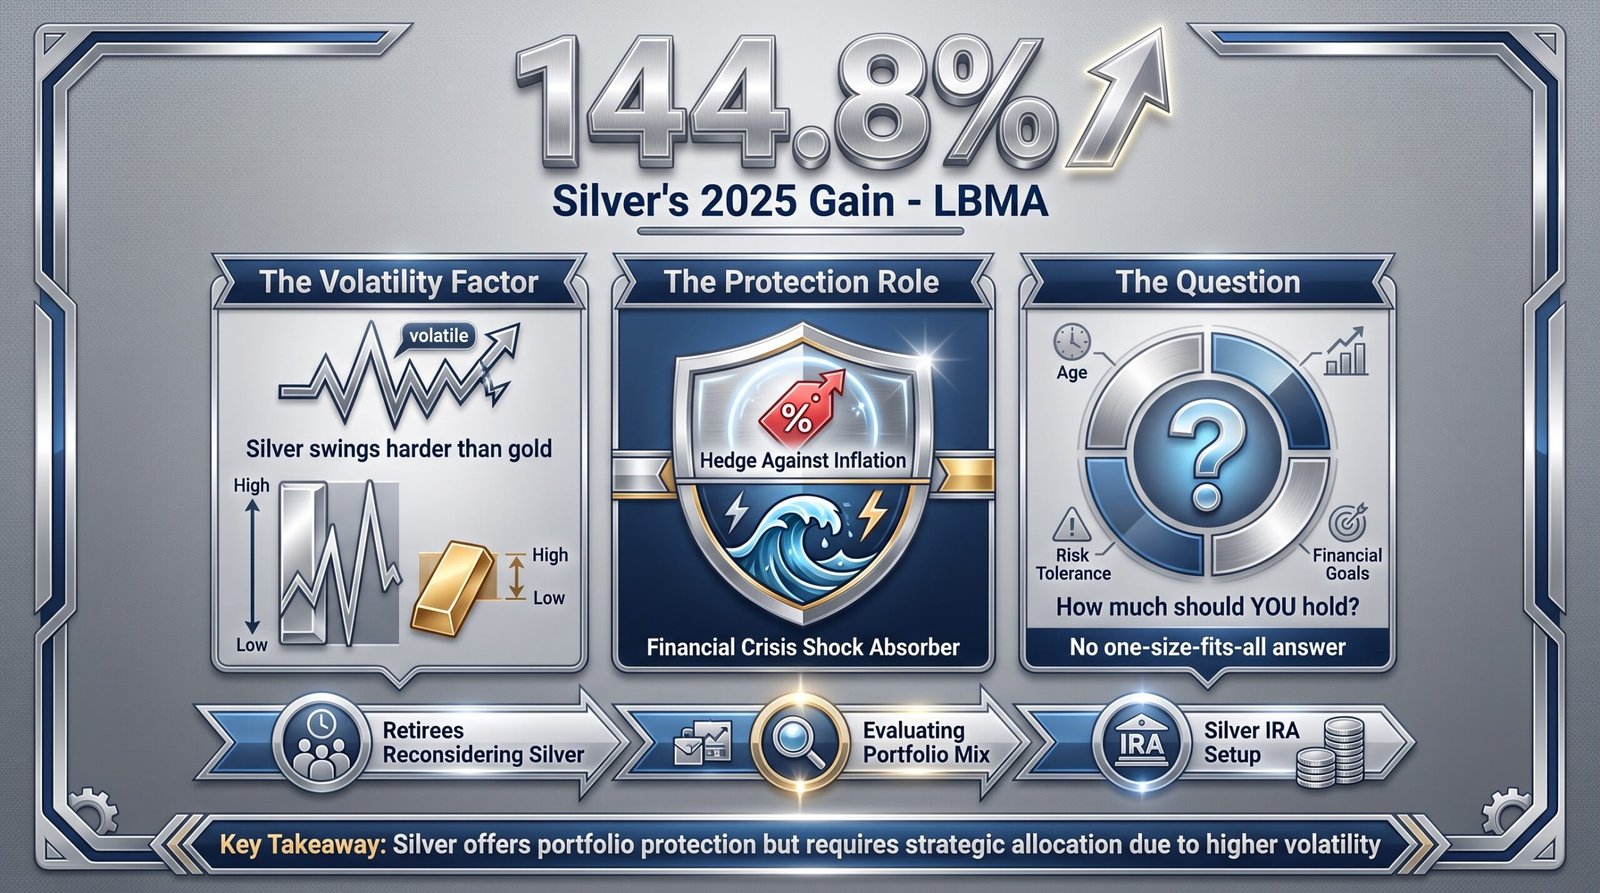
    Silver just posted a 144.8% gain in 2025, according to the LBMA, and that kind of performance has retirees asking one question: how much of this stuff should actually sit in my portfolio?

    The answer isn’t as simple as picking a random percentage and calling it a day. Silver swings harder than gold, yet it’s also proven itself as a hedge against inflation and a shock absorber during financial crises, which is exactly why so many retirees are taking a second look at it.

    If you’re exploring how precious metals fit into your retirement strategy, Augusta Precious Metals has spent over a decade helping people navigate exactly these kinds of decisions, particularly when it comes to setting up silver IRAs the right way.

    This guide covers the percentages experts recommend, the tools you can use to time your purchases, and the real costs and risks that don’t always make it into the sales pitch.

    Table of Contents

    1. Quick Summary
    2. How Much Silver Should You Actually Own?
    3. Physical Silver Coins and Bars
    4. Paper Silver Investments
    5. Setting Up a Silver IRA the Right Way
    6. The Real Risks of Holding Silver
    7. Your Silver Allocation Decision Starts Now
    8. Frequently Asked Questions

    How Much Silver Should You Actually Own?

    Here’s where the rubber meets the road. Knowing silver’s history and having a timing tool is great, but none of it matters if you don’t know how much to actually allocate.

    Financial advisors generally land on a few different frameworks for this, and none of them suggest going overboard.

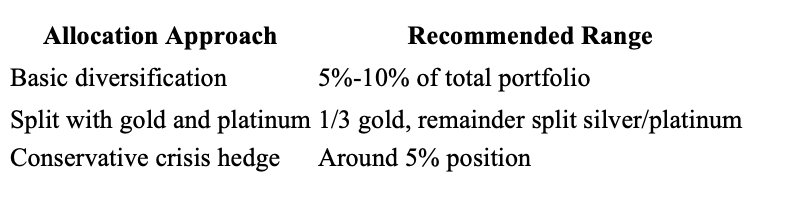
    The 5%-10% Rule for Portfolio Diversification

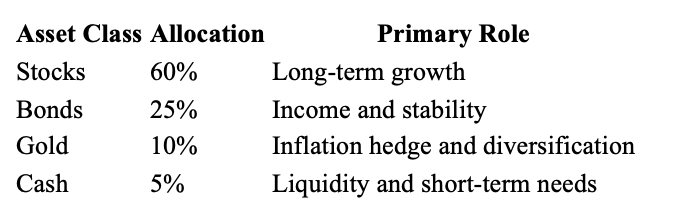
    The most commonly recommended approach is keeping 5% to 10% of your total portfolio in precious metals for basic diversification. This isn’t meant to be your growth engine. It’s meant to be ballast, something that zigs when your stocks and bonds zag.

    The 1/3 Rule: Splitting Between Gold, Silver, and Platinum

    Another framework some investors use splits precious metals holdings into thirds: one-third in gold, with the remaining amount divided between silver and platinum. This approach spreads your precious metals exposure across multiple metals rather than concentrating entirely in one.

    Why a 5% Position Might Be Your Sweet Spot

    For retirees specifically, a 5% position in silver may be enough to deliver impressive returns during a financial meltdown without crushing your overall portfolio if the price moves against you. That’s the balance you’re after: meaningful upside potential during a crisis, limited downside during normal market conditions.

    The consistent theme across every framework is restraint. No credible financial advisor is suggesting retirees put a large chunk of their nest egg into silver, and for good reason, which we’ll get into later in this guide.
    1. Physical Silver Coins and Bars

    When most people picture investing in silver, they picture the physical stuff: coins and bars you can actually hold. This remains the most straightforward way to own silver, though it comes with its own set of considerations.

    Physical silver splits into two main categories, and understanding the difference helps you decide which fits your goals better.

    American Silver Eagles and Canadian Maple Leafs

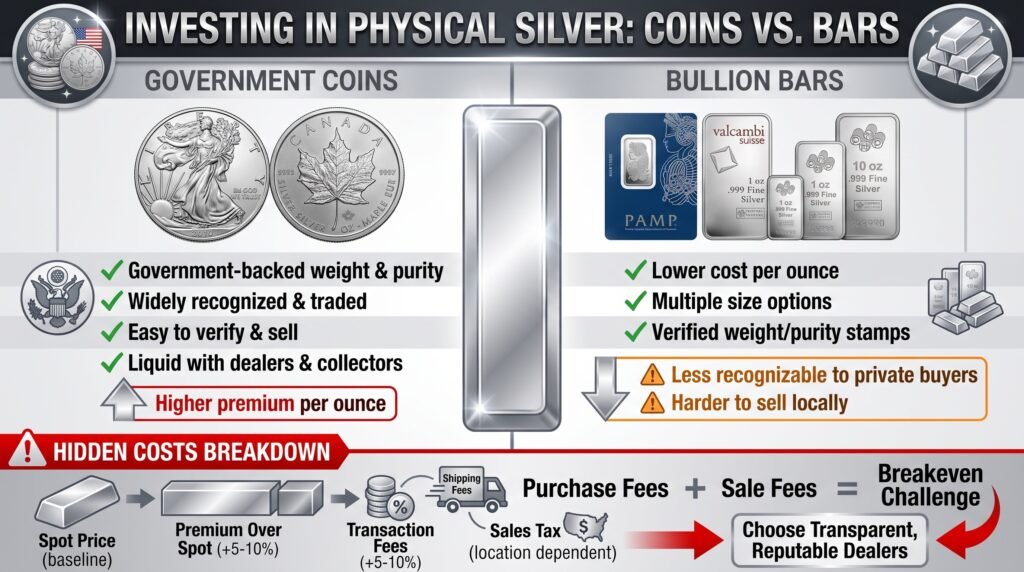
    Government-minted coins represent the gold standard, so to speak, of physical silver ownership. American Silver Eagles, produced by the U.S. Mint, and Canadian Silver Maple Leafs are two of the most widely recognized and traded options. These coins carry government backing for their weight and purity, making them easy to buy, sell, and verify.

    Trusted Bar Producers Like PAMP Suisse and Valcambi

    Silver bullion bars come in several different sizes and typically cost less per ounce than coins, since they require less manufacturing detail. Reputable refiners stamp their bars with verified weight and purity markings, which matters enormously when it comes time to sell. The tradeoff is that bars aren’t traded as easily with private parties or local coin shops compared to coins, since they lack the instant recognizability of a government-minted coin.

    The Hidden Cost of Premiums and Transaction Fees

    Here’s something that catches a lot of first-time silver buyers off guard: you’ll pay a premium over the spot price for any physical silver you buy, covering manufacturing costs and dealer margins. On top of that, transaction fees for silver bullion coins or bars can run anywhere from 5% to 10%, and that’s not unusual.

    If you’re paying those fees on both the purchase and the eventual sale, the price needs to climb substantially just to get you back to breakeven. Factor in shipping fees and sales tax depending on where you live, and the all-in cost of physical silver adds up fast. This is exactly why working with a reputable dealer who’s transparent about pricing matters so much.
    2. Paper Silver Investments

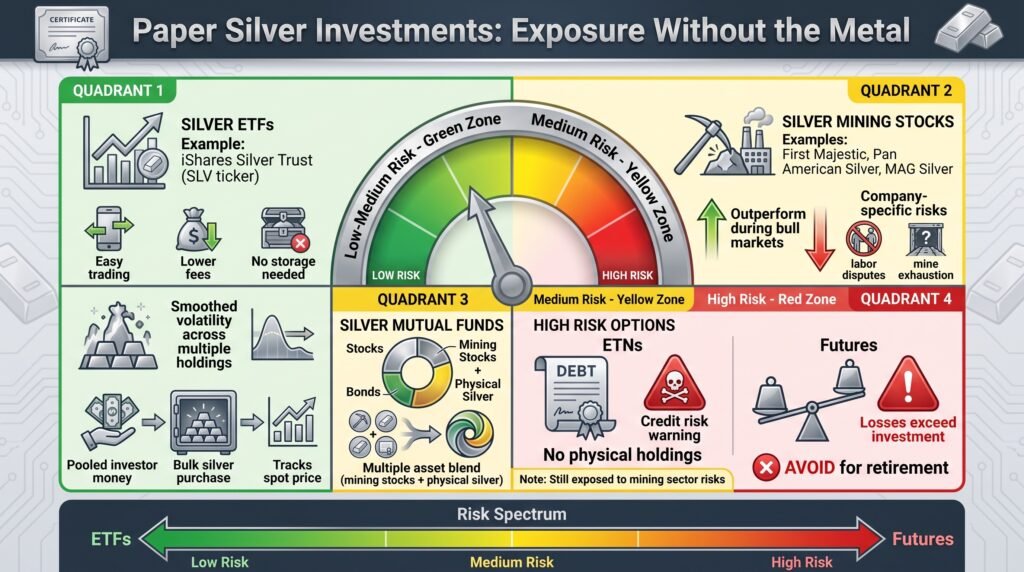
    Not everyone wants to deal with physical storage, insurance, and the hassle of verifying authenticity. That’s where paper silver investments come in, offering exposure to silver’s price movements without ever touching an actual coin or bar.

    Silver ETFs Like iShares Silver Trust (SLV)

    Silver exchange-traded funds pool investor money to buy silver at scale, with share prices designed to track the metal’s spot price. The iShares Silver Trust, trading under the ticker SLV, is one of the most recognized examples. ETFs let you buy and sell your silver exposure as easily as trading a stock, with lower fees than dealing in physical metal and none of the storage headaches.

    Silver Mining Stocks vs. Silver Mutual Funds

    Silver mining stocks represent shares in companies that actually dig silver out of the ground, names like First Majestic Silver Corp, Pan American Silver Corp, and MAG Silver Corp. These stocks can outperform silver itself during bull markets, since a rising silver price often boosts mining company profits disproportionately. But they also carry company-specific risks that have nothing to do with silver prices, like labor disputes or mine exhaustion.

    Silver mutual funds, on the other hand, pool investor money across several silver-related assets, often blending mining stocks with physical silver holdings. This diversified approach can smooth out some of the volatility you’d get from betting on a single mining company, though it still carries exposure to the broader risks facing the mining sector.

    ETNs and Futures Contracts: Higher Risk Options

    Exchange-traded notes, or ETNs, track an underlying silver index but don’t actually hold physical silver or stock in mining companies. Instead, they’re unsecured debt securities issued by a financial institution, which means you’re taking on credit risk tied to the issuer alongside silver’s price risk. That’s an extra layer of complexity most retirees don’t need.

    Silver futures take things even further into speculative territory, letting you bet on future silver prices using leverage. The potential for losses with futures can exceed your initial investment, which makes this option far too risky for most retirement portfolios. If you’re building a nest egg you plan to rely on, futures contracts belong on the “avoid” list rather than the “consider” list.
    Setting Up a Silver IRA the Right Way

    If you’re serious about adding silver to your retirement portfolio in a tax-advantaged way, a silver IRA is the vehicle built specifically for that purpose. But the IRS has strict rules about what qualifies, and getting this wrong can trigger unexpected taxes and penalties.

    A silver IRA works similarly to a traditional retirement account, except instead of holding stocks and bonds, it holds physical silver that meets specific IRS purity requirements. Setting one up correctly requires working with the right custodian and understanding exactly what silver products qualify.

    This is an area where having an experienced partner matters enormously. Augusta Precious Metals  and Birch Gold Group have built relationships with mints around the world specifically to help customers purchase IRA-eligible gold and silver coins directly from their producers, which helps ensure authenticity and compliance with IRS rules from day one.

    2026 Contribution Limits You Need to Know

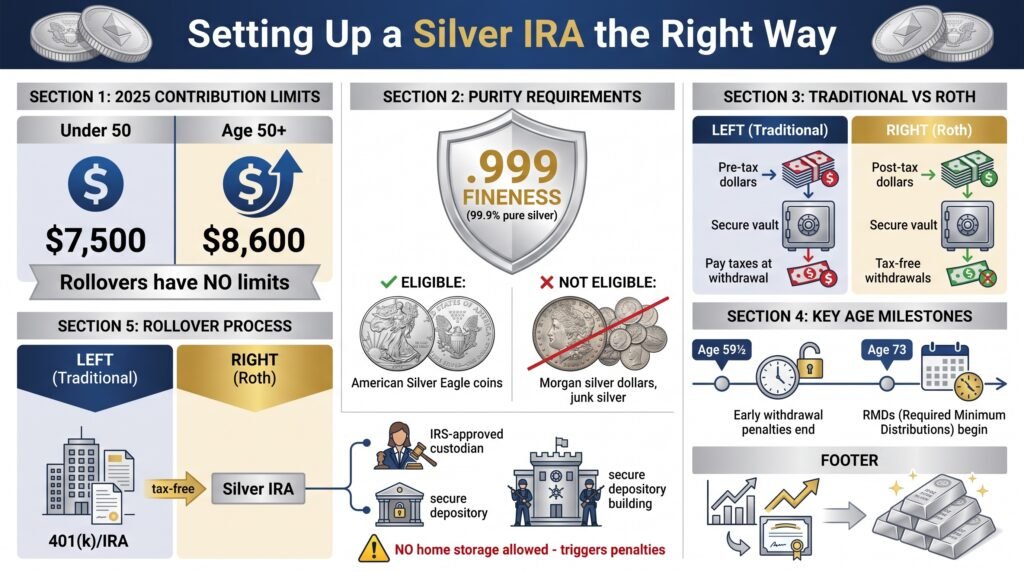
    For 2026, the IRA contribution limit sits at $7,500 if you’re under age 50, and $8,600 if you’re 50 or older. These limits apply to new contributions into your account each year.

    Here’s the good news if you’re rolling over an existing retirement account: contribution limits don’t apply to rollovers and transfers, which can be any sum. This means you can move funds from an existing 401(k) or traditional IRA into a silver IRA without worrying about hitting an annual cap.

    Fineness Requirements for IRA-Eligible Silver

    Not every silver coin or bar qualifies for an IRA. The tax code specifically forbids collectibles from being held in an IRA, and IRA-eligible silver coins must meet a minimum fineness requirement of .999, meaning 99.9% pure silver. American Silver Eagle coins produced by the U.S. Mint meet this standard and are among the most commonly held IRA-eligible silver products.

    This requirement rules out a lot of silver that investors already own. Older Morgan silver dollars and US junk silver, for example, don’t meet the fineness requirement and aren’t eligible for purchase through a silver IRA. It’s also worth noting you can’t purchase coins you already personally own using silver IRA funds, since that would violate IRS rules against self-dealing.

    Traditional vs. Roth Silver IRAs

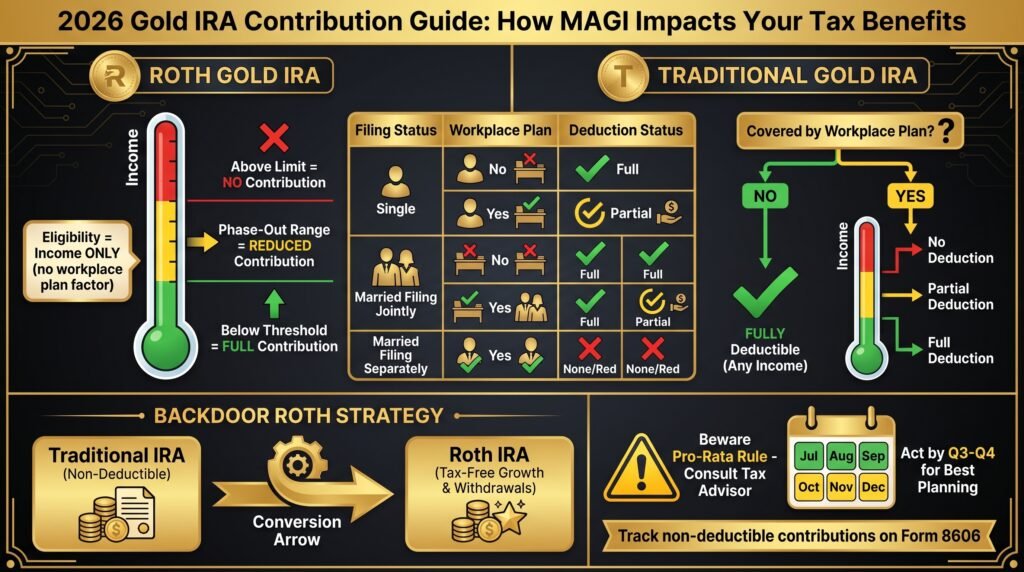
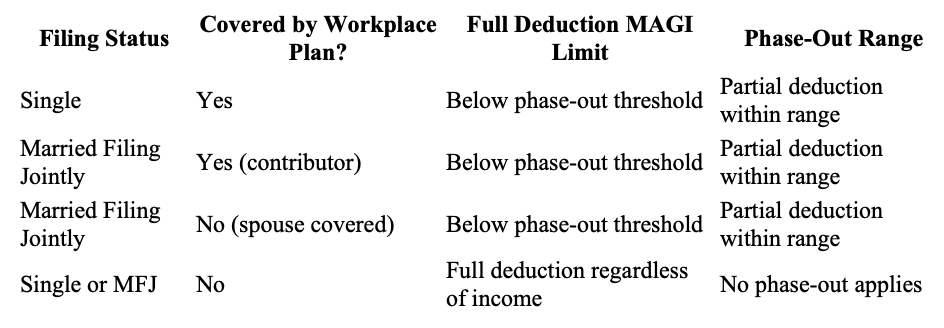
    Most silver IRAs are structured as Traditional IRAs, meaning you fund them with pre-tax dollars and only pay taxes once you take distributions in retirement. This setup works well if you expect to be in a lower tax bracket once you retire.

    You can also open a Roth silver IRA instead, funding it with post-tax dollars. The advantage here is that qualified distributions in retirement come out completely tax-free, gains included. If you expect your tax bracket to be similar or higher in retirement, a Roth structure might serve you better long-term.

    Required Minimum Distributions After Age 73

    If your silver IRA is structured as a Traditional IRA, you’ll be required to take required minimum distributions, known as RMDs, once you reach age 73. This is a standard IRS rule across all traditional retirement accounts, not something unique to silver, but it’s worth planning around since you’ll need enough liquidity to satisfy these distributions.

    Taking money out before age 59½ triggers potential taxes and penalties, so timing matters just as much on the front end as it does once RMDs kick in.

    Rolling Over Your 401(k) or IRA Tax-Free

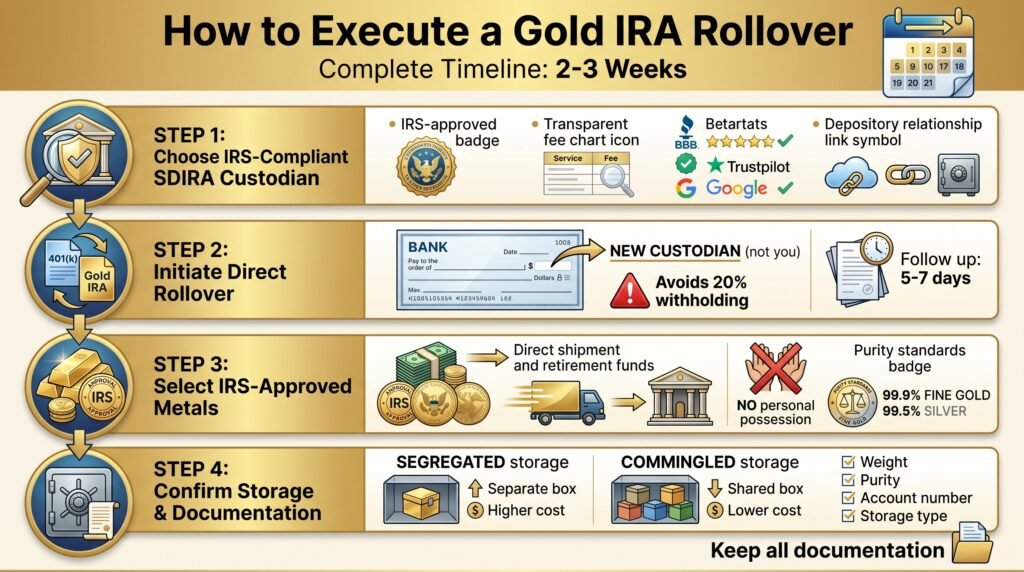
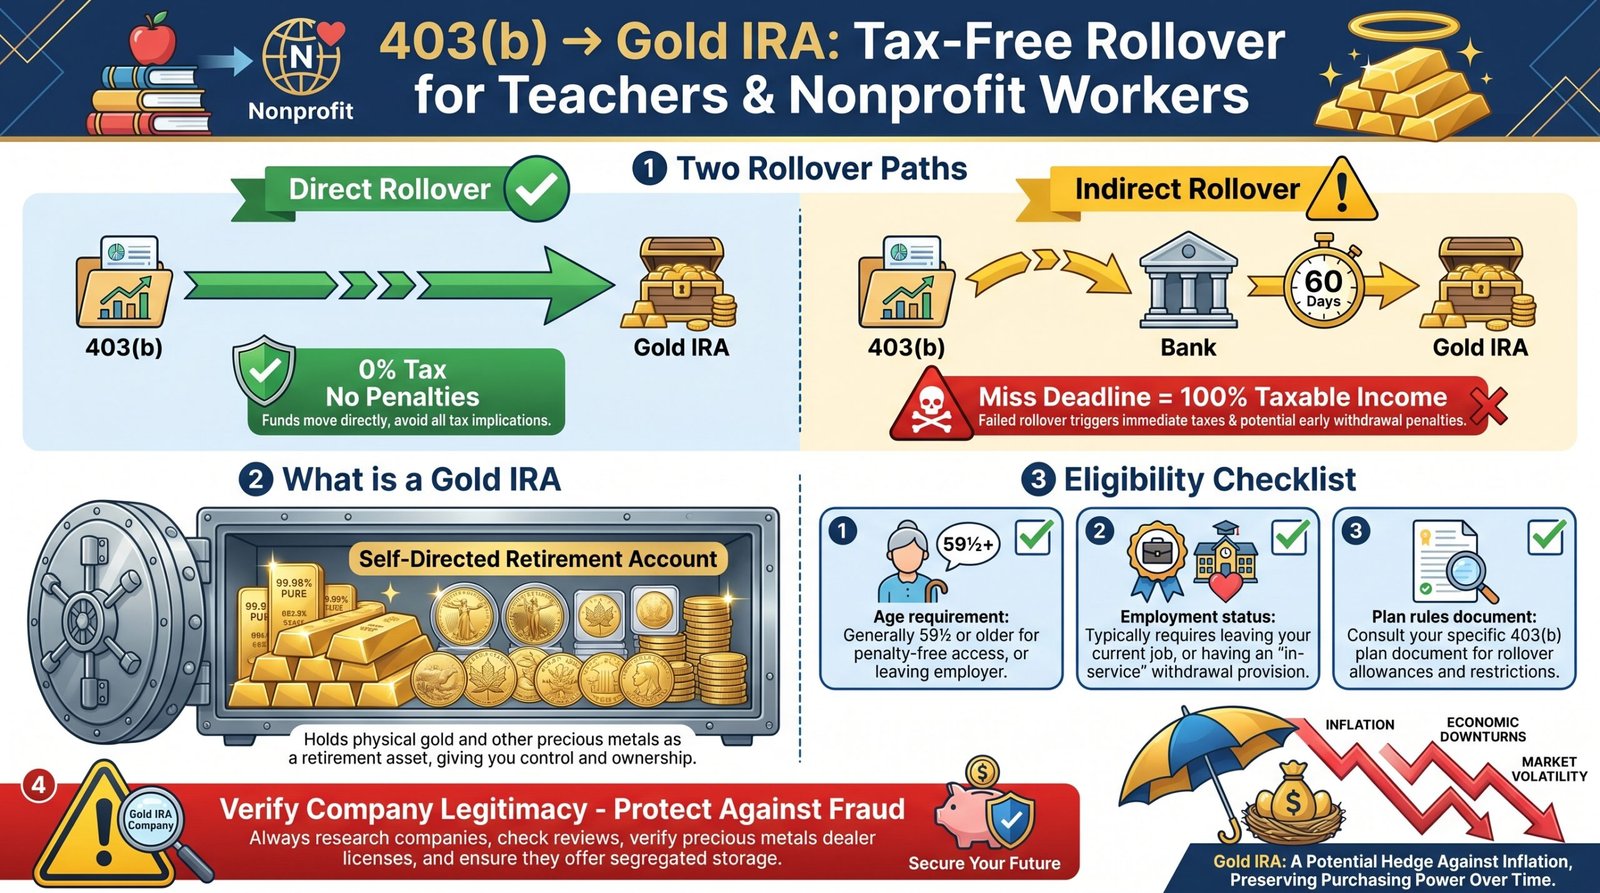
    If you already have retirement savings sitting in a 401(k) from a previous employer, or in an existing traditional IRA, you can roll those funds into a silver IRA without triggering taxes or penalties, as long as the rollover follows IRS guidelines. This is often the most practical entry point for retirees who want silver exposure without pulling new money out of pocket.

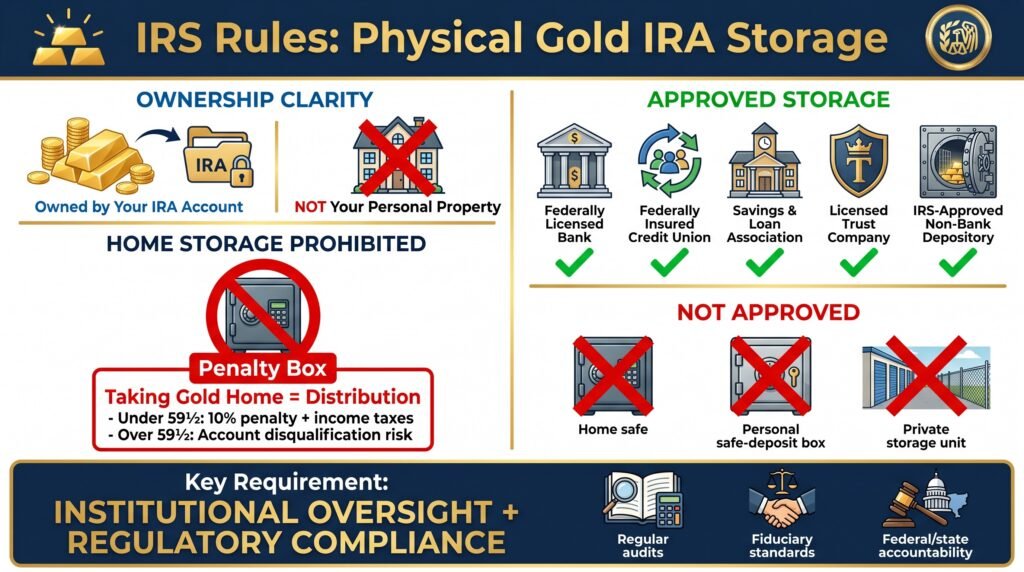
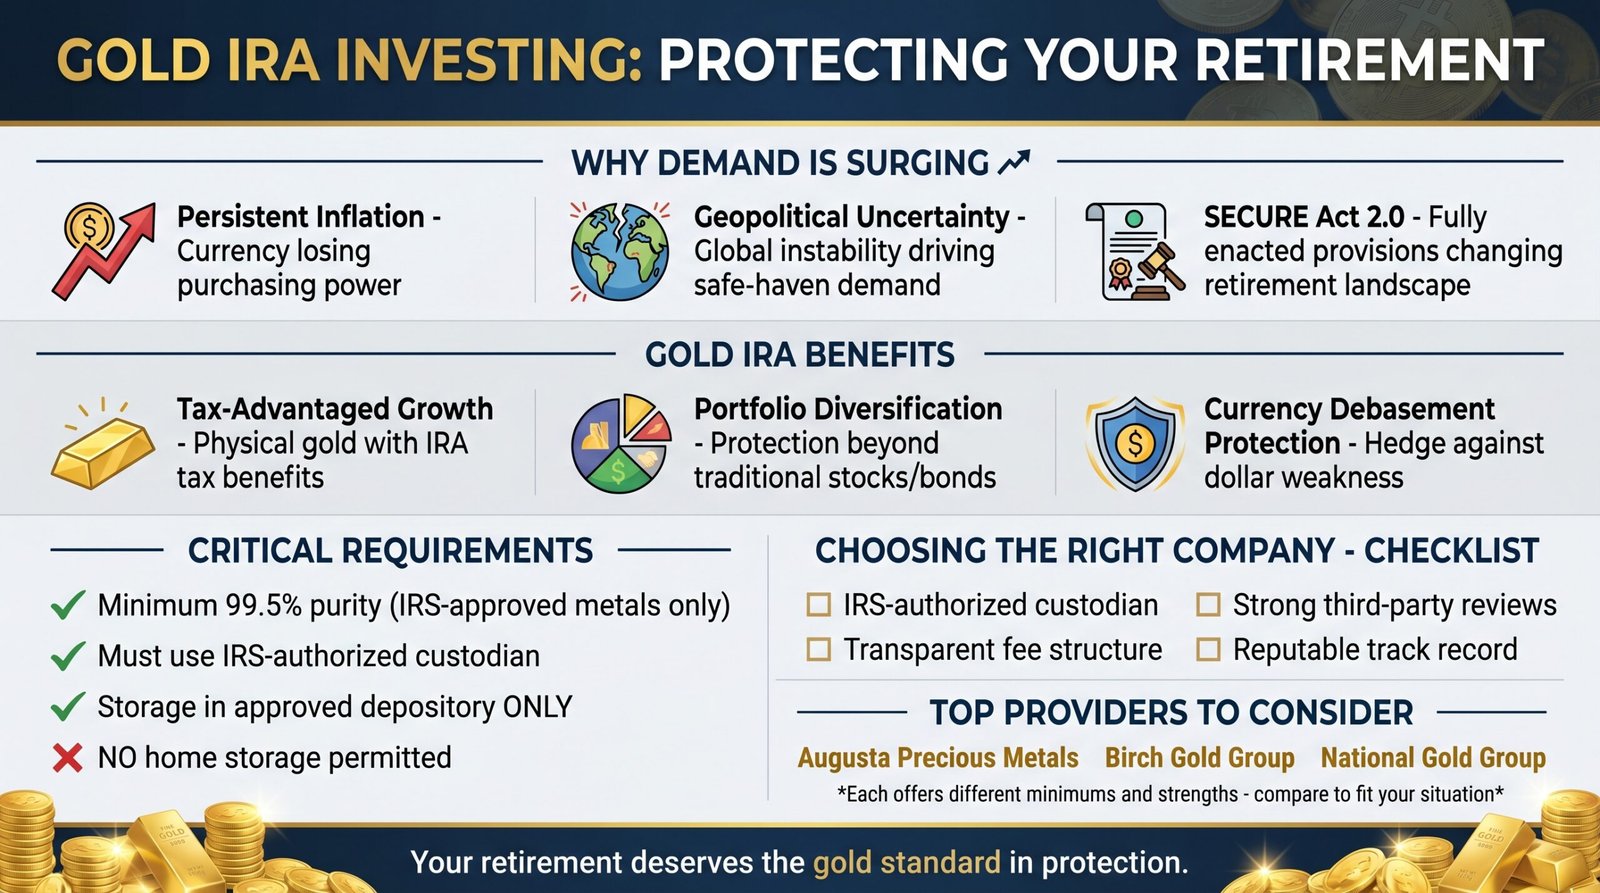
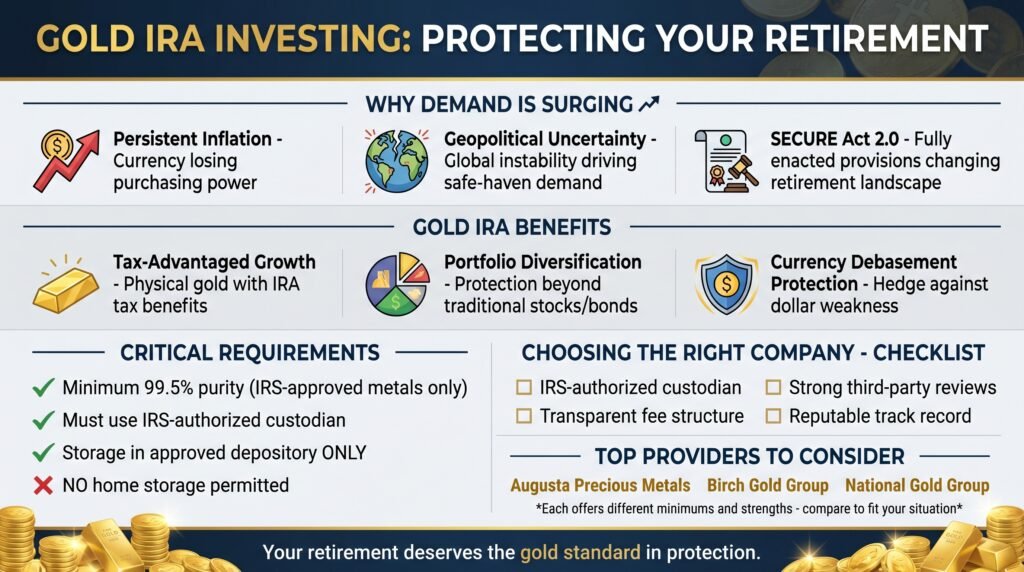
    Your silver IRA assets will need to be managed by an IRS-approved custodian, and the physical silver itself gets stored at a precious metals depository rather than in your home. Attempting to store IRA silver yourself, even in a home safe, could subject you to significant taxes and penalties, so this isn’t a step worth cutting corners on.

    Augusta Precious Metals is best for high-income earners, best pricing, & lifetime customer support. Birch Gold Group is known for low investment minimums, low fees, and established trust.

    Receive a free gold information kit by filling out their short contact form when you click one or both of the banners below.
    gold_silver_kit
    Augusta Precious Metals

    The Real Risks of Holding Silver

    Silver isn’t a set-it-and-forget-it investment, and pretending otherwise does retirees a disservice. The same volatility that can produce impressive gains can just as easily produce painful losses, and understanding these risks upfront helps you size your position appropriately.

    • Price volatility driven by shifting industrial demand
    • No income or yield generated while you hold it
    • Mining stock risks tied to company-specific issues
    • Long stretches of flat, directionless price action
    • Difficulty timing entry and exit points

    The major risk with silver investing is simply price instability. Unlike bonds that pay predictable interest, silver’s value depends entirely on what someone else is willing to pay for it at any given moment. When the broader economy is performing well, silver and other precious metals generally become less attractive, since investors shift toward assets offering higher yields elsewhere. That’s an important dynamic to keep in mind: silver often does best precisely when everything else is struggling.

    Price Volatility and Industrial Demand Swings

    Because industrial demand makes up such a large portion of silver’s overall demand, a decrease in that industrial activity can drop the market price fairly quickly. This differs meaningfully from gold, whose price is far less tied to industrial consumption.

    This means silver’s price performance may actually be poor during exactly the kind of financial instability that would otherwise make precious metals attractive, if that same instability also suppresses industrial activity and manufacturing output.

    Why Silver Produces No Yield…Or Does It.

    • No dividends paid out, unlike dividend-paying stocks
    • No interest earned, unlike bonds or savings accounts
    • Returns come exclusively from price appreciation

    This is a critical distinction for retirees to understand before allocating retirement savings toward silver. A bond or dividend stock generates cash flow you can actually live on in retirement, while silver sits there, potentially gaining value, but never paying you anything along the way unless you invest in a silver lease.

    Contrary to merely holding the physical metal itself, participating in a silver lease actually puts the silver into productive use within industry and provides a real interest yield competitive with bonds. Monetary Metals provides silver as well as gold leases that average 3-4%+ during the term of the lease. Learn more here.

    Mining Stock Risks Beyond Price Movement

    Silver mining stocks are probably the most speculative way to participate in the silver market, and they carry risks that have nothing to do with silver’s price. International disturbances, environmental catastrophes, foreign government regulation or nationalization, labor unrest, and currency fluctuations can all tank a mining stock even while silver prices hold steady or rise. More and more people today seem to be getting nervous about the future of the economy and their financial security, which is why some are considering options like a Silver IRA as a hedge against these risks.

    On top of these external risks, mining companies face risks specific to the business itself: high capital costs, the risk of mine exhaustion, oversupply of the metal, and the genuine possibility of investing heavily to develop a mine that ultimately produces minimal or no silver.

    Your Silver Allocation Decision Starts Now

    Silver isn’t a complicated asset once you strip away the hype. It’s a volatile, non-yielding metal with real industrial utility and a documented history of holding up during financial crises. Used correctly, in that 5% to 10% range most advisors recommend, it can serve as genuine diversification against the risks concentrated stock and bond portfolios carry.

    The retirees who get the most out of silver treat it as a deliberate, limited allocation rather than a speculative bet on quick riches. Whether that means opening a silver IRA, buying physical coins through a trusted dealer, or gaining exposure through an ETF, the principles stay the same: understand the costs, respect the volatility, and size your position so a downturn in silver prices never threatens your broader retirement security.

    Birch Gold Group: Best Gold IRA for Established Trust & Low Fees
    Gold and Silver IRA Info Kit
    Gold IRA Information Kit

    Augusta Precious Metals: Best Gold IRA for Prices & Customer Support

    Read more about how gold belongs in your portfolio for proper diversification, inflation hedging, and more here.

    Find out whether gold IRAs are a good choice for your retirement needs. Access our Silver IRA calculator by clicking the banner below.

    Silver IRA Calculator
    Silver IRA Calculator

    Frequently Asked Questions

    Silver raises plenty of practical questions once you start considering it for your retirement portfolio. Here are the answers to the ones retirees ask most often.

    These questions cover everything from allocation percentages to tax treatment, giving you a quick reference as you finalize your own silver strategy.
    What percentage of my retirement portfolio should be silver?

    Most financial advisors recommend keeping silver between 5% and 10% of your total portfolio, with some suggesting a conservative 5% position specifically for crisis protection without overexposing your retirement savings to silver’s volatility.

    Can I hold silver in my IRA at home?

    No. Attempting to store silver IRA assets at home could subject you to significant taxes and penalties. Your silver IRA coins and bars must be stored at an approved precious metals depository, managed by an IRS-approved custodian.

    How do I start a silver IRA rollover?

    You can roll over funds from an existing 401(k) or traditional IRA into a silver IRA without triggering taxes or penalties, as long as you follow IRS rollover guidelines and work with an approved custodian. Contribution limits don’t apply to rollovers, so you can transfer any sum from an eligible existing account.

    Working with an experienced partner throughout this process helps ensure your silver purchases meet IRS fineness requirements and that your rollover gets handled correctly from start to finish.

    What’s the difference between silver coins and silver bars for investing?

    Silver coins, like American Silver Eagles, typically cost more per ounce but trade more easily with private parties and coin shops due to their instant recognizability. Silver bars cost less per ounce but aren’t traded as easily outside formal dealer networks.

    Both qualify for IRA purposes as long as they meet the required .999 fineness standard, though coins tend to offer more liquidity for retirees who might need to sell quickly.

    Should I choose a Traditional or Roth silver IRA?

    A Traditional silver IRA uses pre-tax dollars and taxes your gains only when you take distributions, which works well if you expect a lower tax bracket in retirement. A Roth silver IRA uses post-tax dollars, but qualified distributions come out completely tax-free, which can benefit those expecting a similar or higher tax bracket down the road.

    Figuring out your exact number doesn’t have to be a solo project. Augusta Precious Metals works with retirement investors every day to build precious metals strategies that match their specific timeline, income needs, and comfort with risk.

    Get started with a tax-advantaged IRA with Augusta by clicking the banner below.
    Sources:
    How To Invest In Silver: 2026 Guide – Swiss America

    How to Invest in Silver

    Start a Silver IRA- Goldco

  • Gold in a Retirement Portfolio: How Much Is Right for You?

    Gold in a Retirement Portfolio: How Much Is Right for You?

    Gold IRA Investment - Beginner Guide, Tips & Insights
    Gold IRA Investment – Beginner Guide, Tips & Insights

    Quick Summary

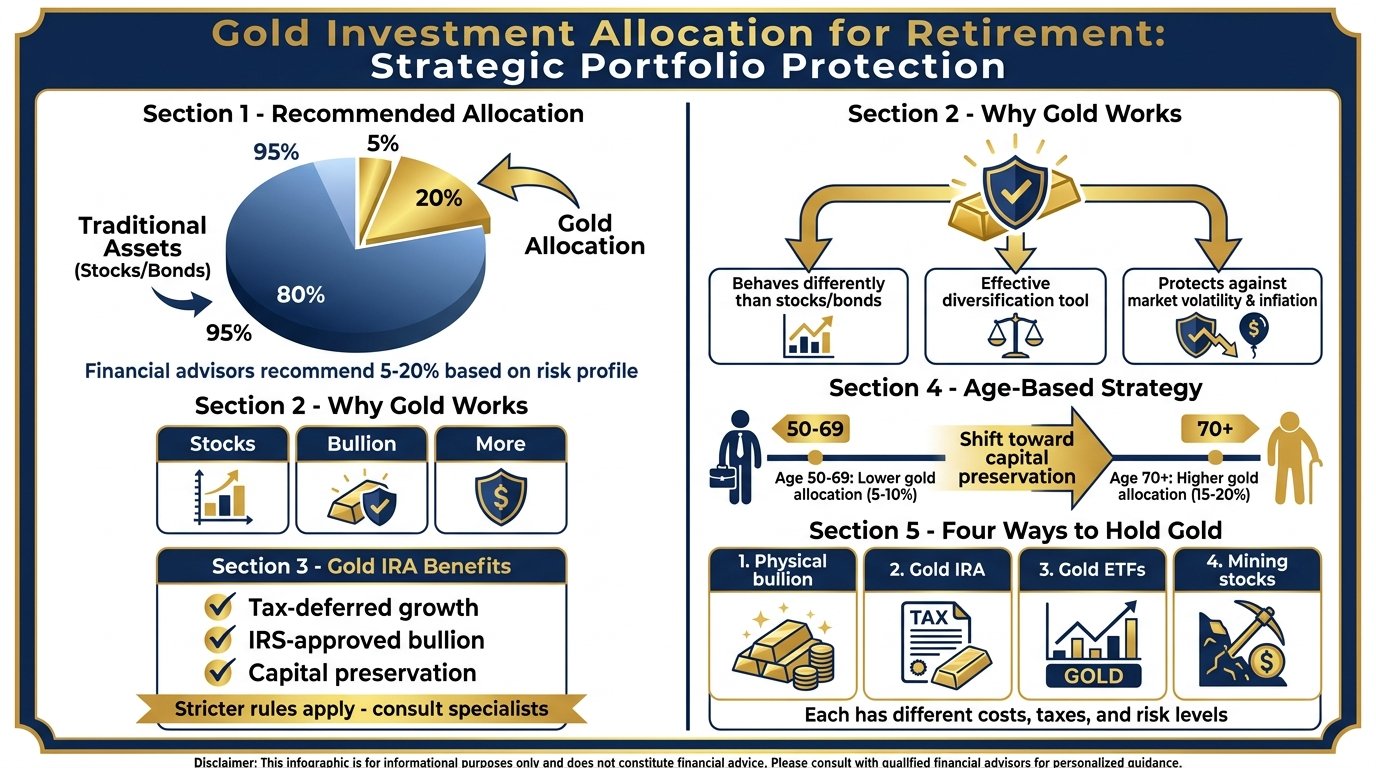
    • Most financial institutions recommend holding between 5% and 15% of a retirement portfolio in gold, though the right number depends heavily on your age, risk tolerance, and income needs.
    • Gold pays no dividends or interest, so planners generally cap non-income-producing assets like gold at 15%–20% of a retiree’s total portfolio.
    • Gold hit a record high above $4,800 per ounce in early 2026 after a 65% run in 2025 alone, but a recent rally is not a reason to overload your allocation.
    • Working with a knowledgeable resource like reputable gold companies with a solid reputation can help you figure out which allocation, storage structure, and metal mix actually fits your retirement timeline.
    • There’s a specific allocation range for every stage of retirement planning, from first-time buyers decades away to retirees already drawing income, and knowing where you land changes everything about how much gold makes sense.

    Gold’s role in a retirement portfolio isn’t about getting rich quick; it’s about making sure a market crash doesn’t wreck the retirement you’ve spent decades building.

    If you’ve ever wondered whether 5% is too little or 20% is too much, you’re asking the right question. The answer isn’t one-size-fits-all, and the financial world’s biggest names don’t even agree with each other. BlackRock suggests a modest 2%–5%. Ray Dalio’s “all-weather” strategy calls for 15% or more. Somewhere between those numbers sits the right answer for you, and figuring out where requires understanding how gold actually behaves, not just what it’s worth today.

    This guide breaks down exactly what the data shows, how gold performed during the crashes that mattered most, and how much of it belongs in your portfolio depending on where you stand in your retirement journey.

    Firms like Augusta Precious Metals work with investors every day who are trying to answer this exact question, and the patterns they see tend to echo what the broader research confirms.

    Table of Contents

    1. Quick Summary
    2. What Percentage of Gold Should Be in Your Retirement Portfolio
    3. How Gold Actually Behaves in a Portfolio
    4. Where Gold and Silver Prices Stand Right Now
    5. The Right Gold Allocation for Your Stage of Life
    6. Frequently Asked Questions

    What Percentage of Gold Should Be in Your Retirement Portfolio

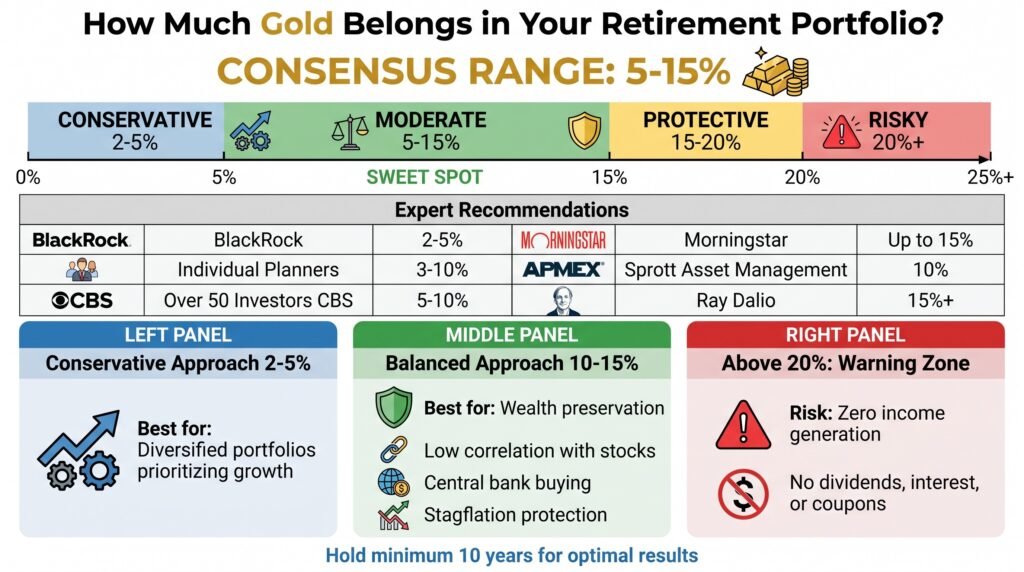
    There’s no single magic number, but there is a consensus range. Pull together recommendations from BlackRock, Morningstar, Sprott Asset Management, and independent financial planners, and you’ll find most professional guidance clusters between 5% and 15% of total portfolio value. That range isn’t arbitrary, it reflects decades of data on how gold performs relative to stocks and bonds during both calm markets and genuine panics.

    Where you fall within that range depends on factors unique to you: how close you are to retirement, how much income your portfolio needs to generate, and how much volatility you can stomach watching your account balance swing. A 35-year-old with three decades until retirement has very different needs than a 68-year-old drawing monthly income from the same pool of assets.

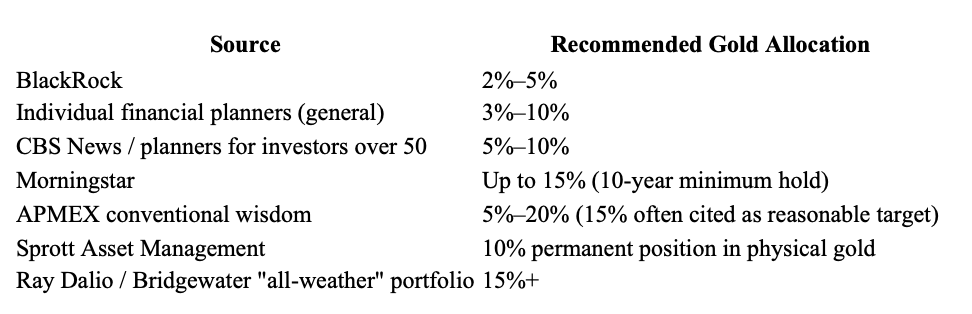
    Here’s how some of the most recognized names in finance and precious metals break down their recommendations:

    Why Most Experts Land Between 5% and 15%

    This range persists across so many different institutions because it strikes a balance. It’s large enough to provide meaningful protection when stocks sell off hard, but small enough that you’re not sacrificing long-term growth potential chasing an asset that produces no income on its own.

    Morningstar’s guidance is particularly useful here because it attaches a timeline: hold for at least 10 years. Gold isn’t a trading vehicle for most retirement investors; it’s a long-term stabilizer that needs time to do its job.

    BlackRock’s Conservative 2%–5% Approach

    BlackRock sits on the lower end of the spectrum, recommending just 2% to 5% in gold. The firm cites favorable near-term economic factors alongside longer-term structural drivers, but its overall stance reflects a belief that gold should play a supporting role rather than a starring one in a well-diversified portfolio.

    If you’re someone who already holds a broad mix of stocks, bonds, and real estate, BlackRock’s lighter-touch recommendation might be the better fit,especially if growth remains your primary objective.

    Why Sprott and Ray Dalio Push for 10%–15% or More

    On the opposite end, Sprott Asset Management advocates for a 10% permanent position in physical gold, separate from gold mining stocks or ETFs. Ray Dalio goes even further, suggesting 15% or more as part of his “all-weather” portfolio philosophy, a strategy specifically designed to hold up across every type of economic environment: growth, recession, inflation, and deflation alike.

    The logic behind these higher allocations comes down to a few recurring themes:

    • Gold has historically shown low or negative correlation with stocks during periods of genuine market panic.
    • Central banks have been net buyers of gold, with 297 tons purchased in 2025 alone, signaling long-term institutional confidence in the metal.
    • During stagflation-style periods, like the 1970s, gold has delivered standout returns compared to most other asset classes.

    For investors who prioritize wealth preservation over maximum growth, a 10%–15% allocation reflects a deliberate trade-off: slightly lower upside potential in exchange for meaningfully better protection when markets turn hostile.

    When Going Above 20% Becomes Risky.

    Pushing past 20% in precious metals is considered a minority approach, and for good reason. Gold generates zero income, no dividends, no interest, no coupons. The more of your portfolio tied up in an asset that produces nothing, the more you’re relying on price appreciation alone to meet your retirement income needs.

    Financial planners generally recommend capping non-income-producing assets at 15% to 20% of a retiree’s total portfolio. Go beyond that, and you risk starving your income strategy just to chase downside protection you may not even need in that magnitude.

    How Gold Actually Behaves in a Portfolio

    Understanding gold’s role starts with understanding what it isn’t. Gold doesn’t represent ownership in a company. It doesn’t pay you anything just for holding it. Its entire value proposition rests on scarcity, global demand, and its historical reputation as a store of value, which is precisely why it behaves so differently from stocks and bonds.

    Gold Pays No Dividends or Interest, or Does It?

    This is the single most important thing to internalize before adding gold to a retirement account. A $100,000 stock portfolio might throw off $2,000–$3,000 a year in dividends.

    A $100,000 gold position throws off exactly $0 in direct income unless you are utilizing a gold lease as an investment vehicle.  Monetary Metals is a gold leasing company that provides investors the ability to expose themselves to gold’s natural price appreciation while earning a real interest yield that is competitive with bonds. And the option to get paid in gold creates an inflation-free fixed-income source as well.  Learn more about Monetary Metals here.

    Traditionally, gold’s value comes from hedging against inflation and depreciation within other parts of your portfolio when equity markets are correcting downward.

    This is why gold functions best as a complement to income-producing assets, not a replacement for them.

    What Drives Gold’s Price Up or Down?

    Gold’s price is shaped by a handful of interconnected forces:

    • Overall economic conditions, including growth or recession signals
    • Currency movements, particularly the strength or weakness of the U.S. dollar
    • Inflation expectations among investors and institutions
    • Global events — wars, political instability, and financial crises
    • Central bank buying and selling activity

    Because these drivers rarely move in lockstep with corporate earnings or stock market sentiment, gold tends to behave differently from equities when markets come under stress, which is exactly the behavior that makes it valuable as a diversification tool.

    Gold vs. S&P 500: A 1970–2026 Comparison

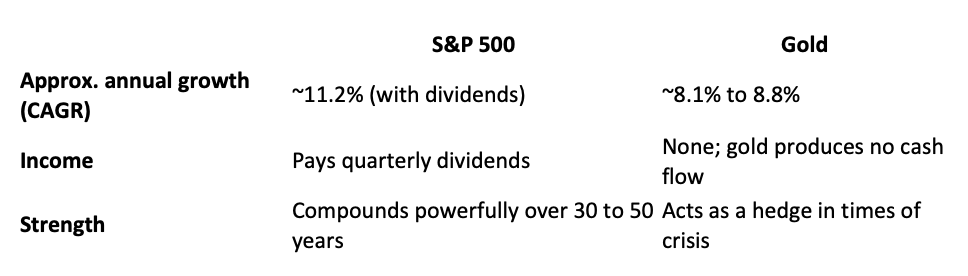
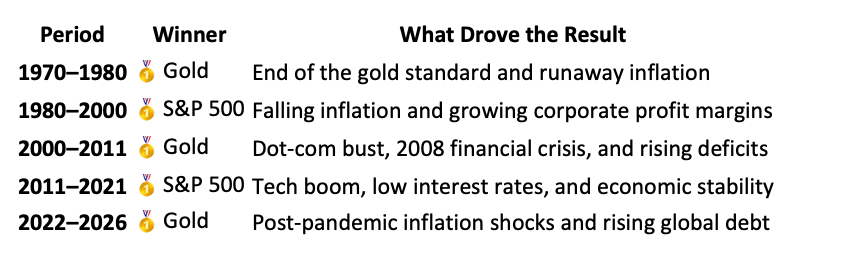
    From 1970 to 2026, the S&P 500 has generally beaten gold on a total-return basis, meaning returns that include reinvested dividends. Gold has still come out ahead during several major stretches, particularly periods of high inflation and global turmoil.

    The Long-Term Numbers

    Why the S&P 500 leads over time: Companies grow earnings and pay out dividends. Reinvesting those payments lets returns build on themselves year after year, which is why the S&P 500 tends to dominate over multi-decade spans.

    Why gold still matters: Gold doesn’t generate income, but it has outperformed during the 1970s, from 2000 to 2011, and again from 2022 to 2026. These were times of inflation, financial stress, or geopolitical uncertainty.

    Era-by-Era: Who Came Out on Top?

    Where Gold Prices Stand Right Now

    As of late 2026, gold is above $4,000 per ounce after hitting an all-time high at $4,800, capping a 65% rise throughout 2025, its strongest annual run since 1979. Silver moved in tandem, posting an even sharper gain of approximately 69% over the same period, though with much larger swings along the way.

    Brett Elliott, Director of Marketing at APMEX, sums up the distinction well: “Gold tends to be a reliable store of value while silver tends to be a growth asset.”

    Gold’s Record Run Past $4,800 an Ounce

    Several forces converged to push gold to these levels, including persistent inflation running above the Federal Reserve’s 2% target, sustained central bank buying, and renewed investor demand for safe-haven assets amid broader economic uncertainty.

    But here’s the caution worth repeating: recent performance is not a reason to buy. Buying into an asset after a 65% annual run carries more risk than buying into a quiet, undervalued market. Chasing the rally rather than building a deliberate, long-term allocation is one of the more common mistakes investors make right now. Gold’s current price surge also doesn’t mean the asset has suddenly become a core growth holding. Its job hasn’t changed, insurance, not offense.

    The Right Gold Allocation for Your Stage of Life

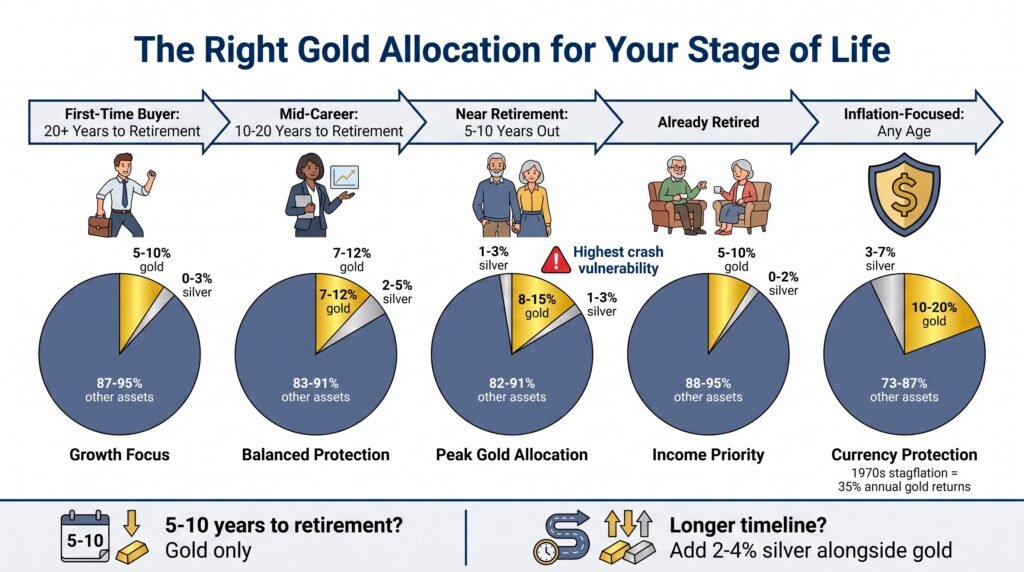
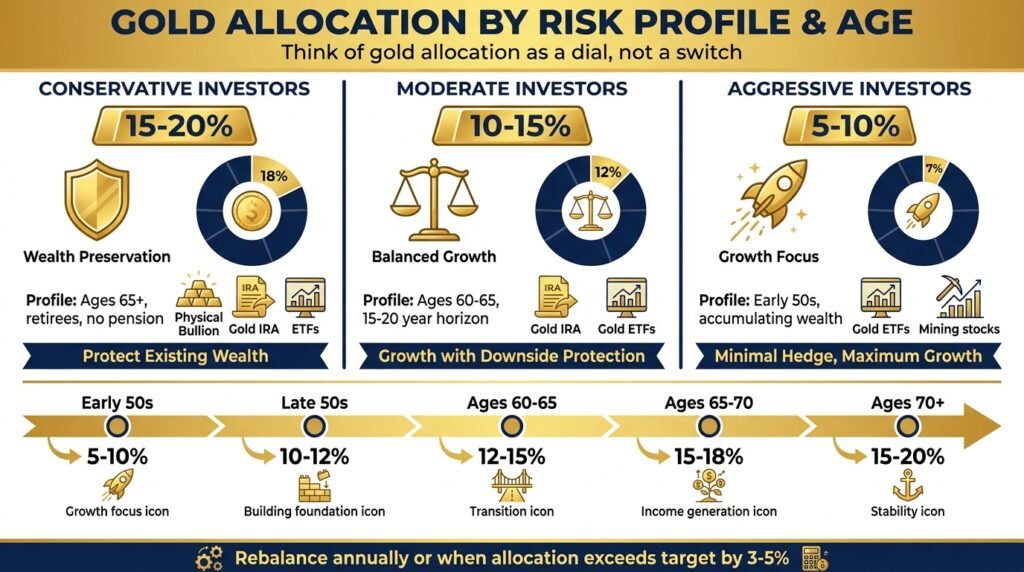
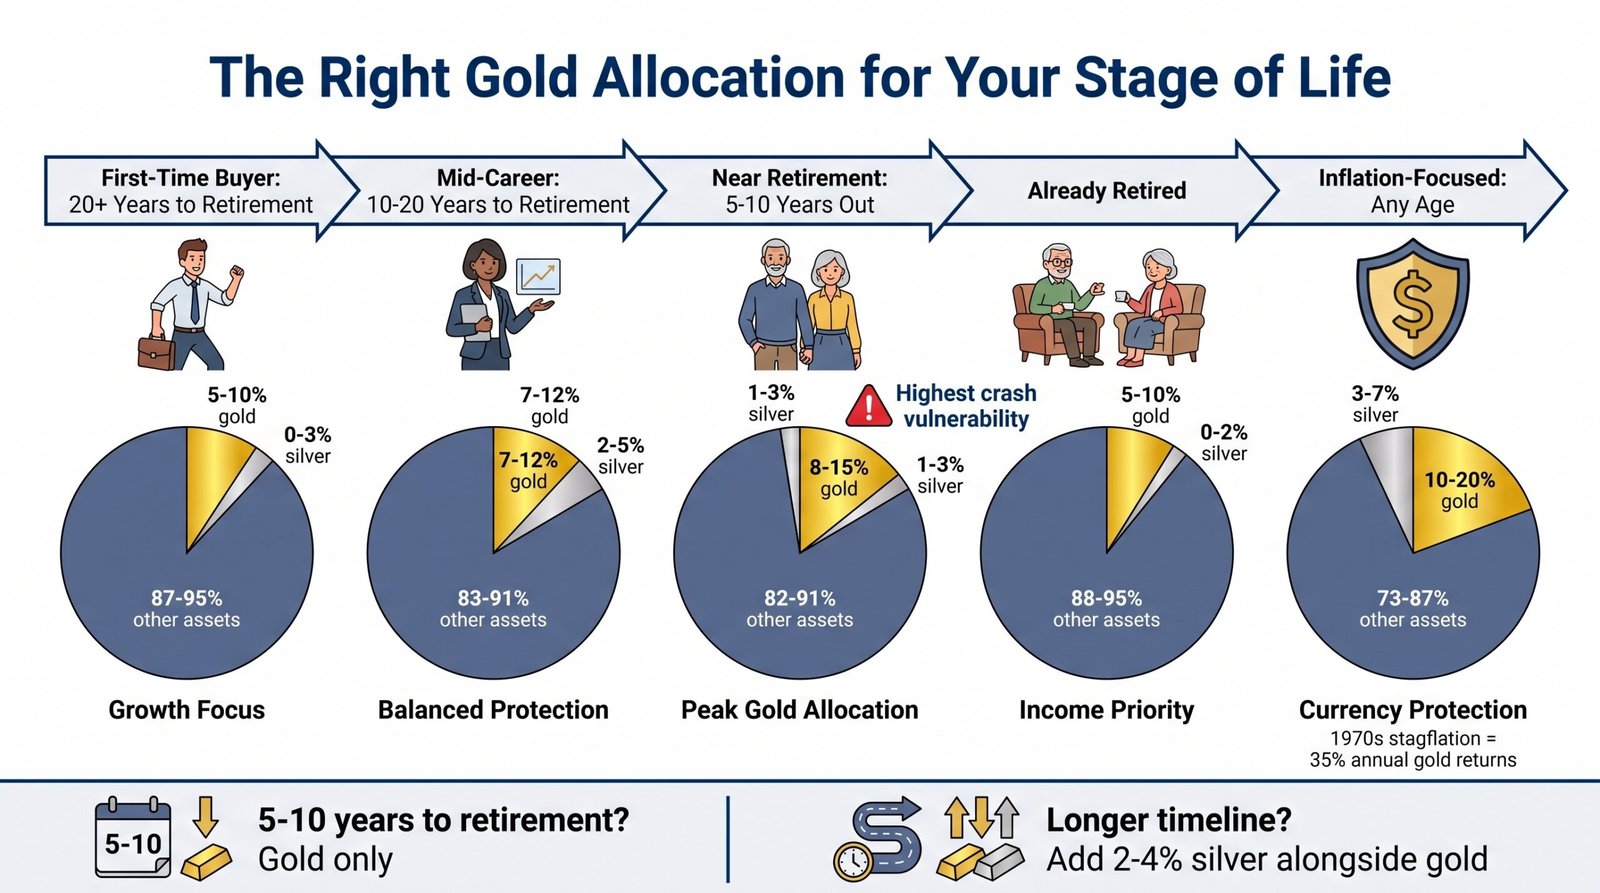
    Age and proximity to retirement change everything about how much gold belongs in your portfolio. The same 10% allocation that makes sense for a 45-year-old might be too conservative for a 65-year-old worried about sequence-of-returns risk, or too aggressive for a 30-year-old who still has decades to ride out market volatility. Here’s how the numbers typically break down across different life stages.

    First-Time Buyer With 20+ Years to Retirement

    If retirement is still two decades or more away, you have the luxury of time on your side. A suggested range here is 5%–10% in gold, with an optional 0%–3% in silver if you want some exposure to its higher-growth potential. At this stage, your portfolio should still be heavily weighted toward growth assets like stocks, with gold serving as a small stabilizing counterweight rather than a central pillar.

    Mid-Career Investor With 10–20 Years Left

    As retirement moves into closer view, it’s reasonable to nudge your gold allocation up slightly, typically 7%–12%, paired with 2%–5% in silver. This is often the stage where investors start paying closer attention to how a major market downturn might affect their timeline, and a slightly larger gold position helps cushion that risk without sacrificing meaningful growth potential.

    Near Retirement: 5–10 Years Out

    This is typically where gold allocations peak, with a suggested range of 8%–15%, alongside a smaller 1%–3% silver position. The reasoning is straightforward: a major market crash five years before retirement is far more damaging than the same crash hitting a 30-year-old, since there’s less time to recover before you need to start drawing on those assets.

    Already Retired and Drawing Income

    Once you’re retired and pulling income from your portfolio, the math shifts again. A suggested range of 5%–10% gold with 0%–2% silver reflects the reality that income-producing assets need to take priority. Gold should serve as insurance at this stage, not an anchor, too much of it, and you risk not generating enough regular cash flow to cover your living expenses.

    Inflation-Focused or Currency-Risk Investors

    Some investors fall outside the standard age-based framework entirely because their primary concern isn’t growth or income; it’s protecting purchasing power against inflation or currency devaluation. For this group, a higher allocation of 10%–20% gold alongside 3%–7% silver is often recommended.

    This profile tends to describe investors who lived through, or closely studied,  the 1970s stagflation era, when gold delivered roughly 35% annualized returns and became one of the best-performing assets of the decade. If currency instability or runaway inflation keeps you up at night, a heavier gold position can offer real peace of mind, even if it means giving up some growth potential elsewhere.

    • Investors within 5–10 years of retirement, or already withdrawing income, should treat gold as their primary or sole precious metal holding.
    • Investors with a longer runway, or for whom precious metals make up a small slice of a broader portfolio, can reasonably add silver at 2%–4% of total portfolio value alongside a core gold position.

    No matter which category you fall into, the underlying principle stays the same: your gold allocation should serve your specific timeline and income needs, not someone else’s.

    Is a Gold IRA Right for You?

    A Gold IRA is not the right move for every investor, but for the right person, it can be one of the most effective tools for building a retirement portfolio that is genuinely resilient to inflation, market crashes, and currency devaluation.

    It makes the most sense if you have a long investment time horizon (ideally 10 or more years), have existing retirement funds of at least $25,000 to $50,000 that justify the fee structure, want diversification beyond stocks and bonds, and are comfortable with a self-directed account that requires more active decision-making than a standard IRA. If you are looking for quick returns, high liquidity, or passive income from dividends and interest, a Gold IRA is not the right primary vehicle. But as one component of a broader, balanced retirement strategy, it is a powerful one.

    Receive a free gold IRA company integrity checklist from Augusta Precious Metals by clicking the banner below.

    Investment Minimums – Personal Considerations

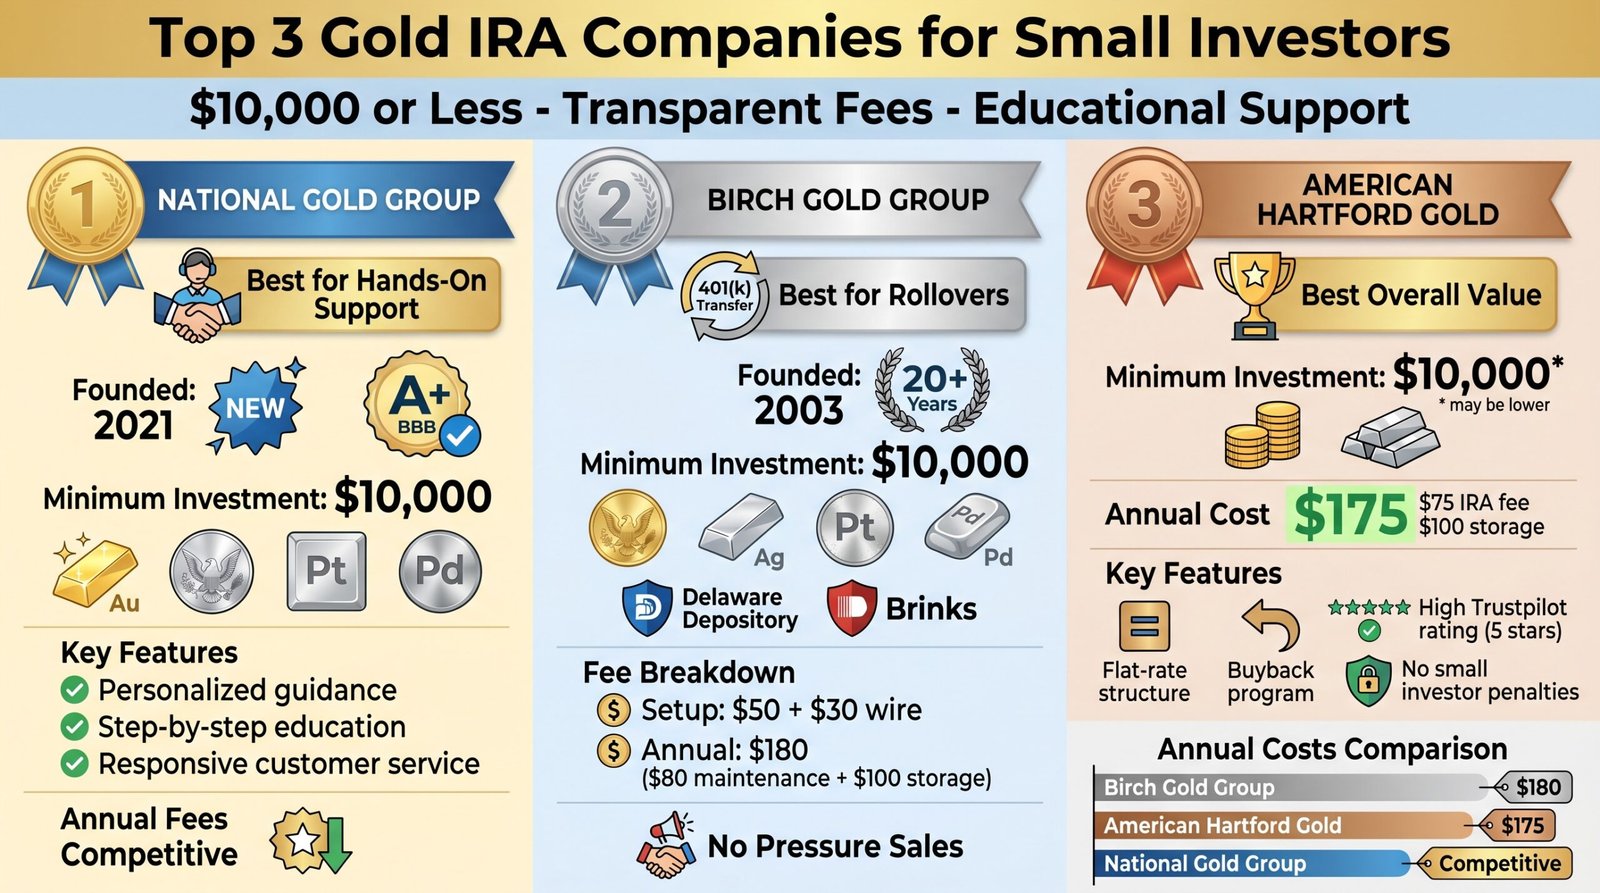
    Certain IRA companies have higher investment minimums than others. If you are a serious investor with a minimum of $50,000, you can take advantage of Augusta Precious Metals’ higher competitive prices, lifelong customer service, and educational resources.

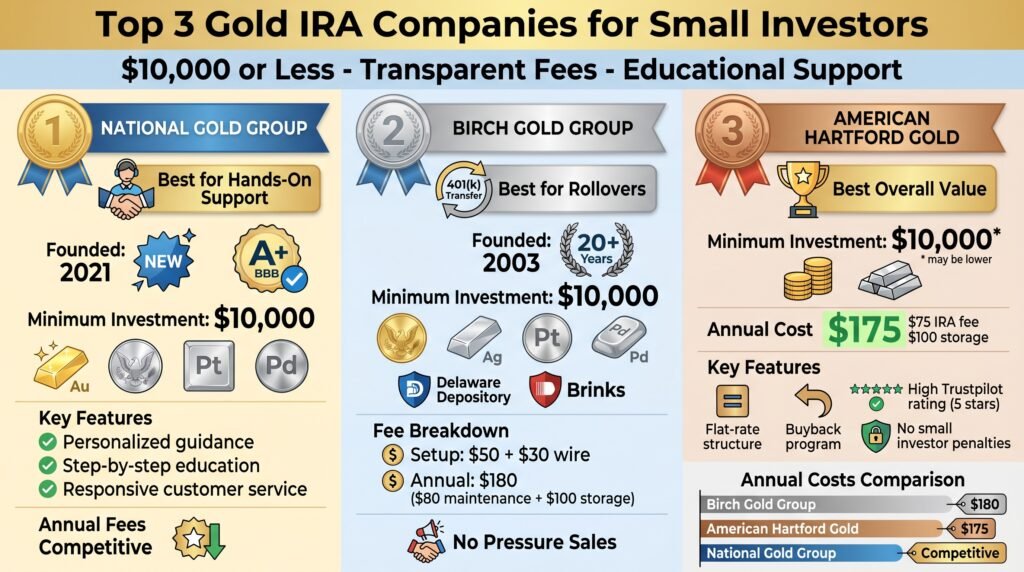
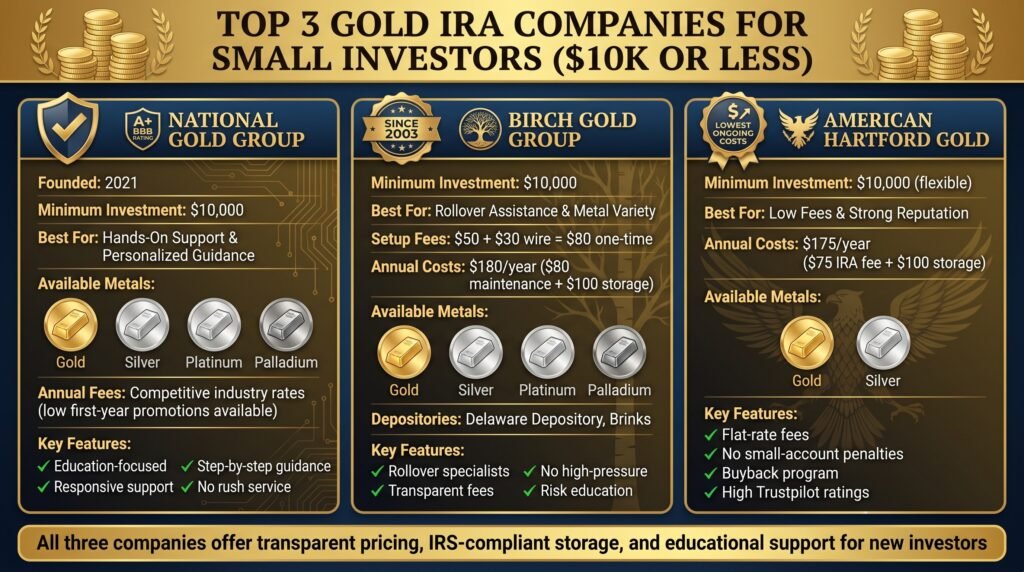
    If you require a lower barrier to entry, both National Gold Group and Birch Gold Group provide a $10,000 investment minimum.

    National Gold Group provides exceptional price transparency and reliable buyback commitment. Birch Gold Group is one of the most established and trusted gold IRA companies, spanning over 20 years, and provides some of the lowest fees in the industry.

    Decide which gold IRA company works for you by clicking the banners below and accessing their free gold IRA guide. Fill out their short contact form to get started.

    Birch Gold Group: Best Gold IRA for Established Trust & Low Fees

    National Gold Group Review

    National Gold Group: Best Gold IRA for Transparency & Buyback

    Read our full list of reviews of the best gold IRA companies that we have carefully researched and vetted here.

    Read more about how to start buying gold for the first time, gold vs. silver, how a Gold IRA Works and What It Costs, and more here.

    Find out whether gold IRAs are a good choice for your retirement needs. Access our Gold IRA calculator. Bookmark this page and perform real-time calculations as you read our reviews.

    Click the banner below to access these calculators and start protecting your wealth today.

    GOLD IRA CALCULATOR
    GOLD IRA CALCULATOR

    Frequently Asked Questions

    If you are still weighing whether a Gold IRA fits your retirement plan, these are the questions most beginners ask before taking the next step.

    Is 10% Gold Too Much for a Retirement Portfolio?

    Not necessarily. A 10% allocation sits comfortably within the range recommended by sources like Morningstar, Sprott Asset Management, and many individual financial planners. Whether it’s appropriate for you specifically depends on your age, income needs, and overall risk tolerance.

    For investors near or in retirement, 10% often falls on the higher end of what’s reasonable once you factor in gold’s lack of income generation; just make sure your income-producing assets remain adequately funded alongside it.

    Can I Hold Physical Gold in My 401(k)?

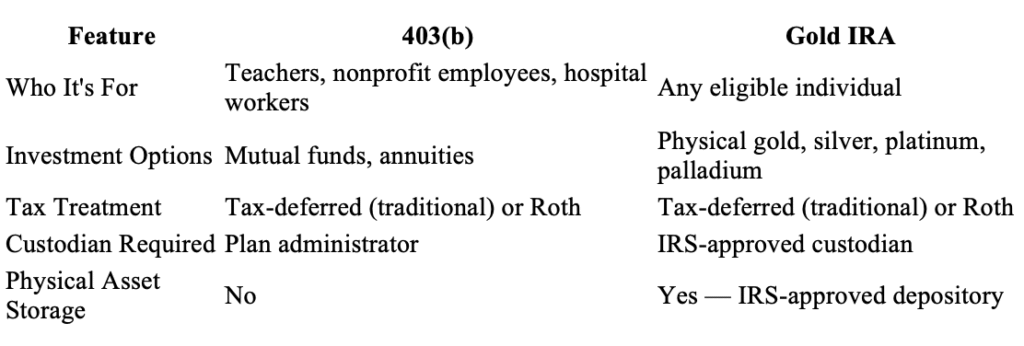
    Most standard employer-sponsored 401(k) plans don’t offer direct physical gold as an investment option. To hold physical precious metals within a tax-advantaged retirement account, you’ll typically need to roll funds into a self-directed Gold IRA, which is specifically structured to allow IRS-approved gold and silver holdings.

    How Do I Move Money into a Gold IRA Without Paying Taxes?

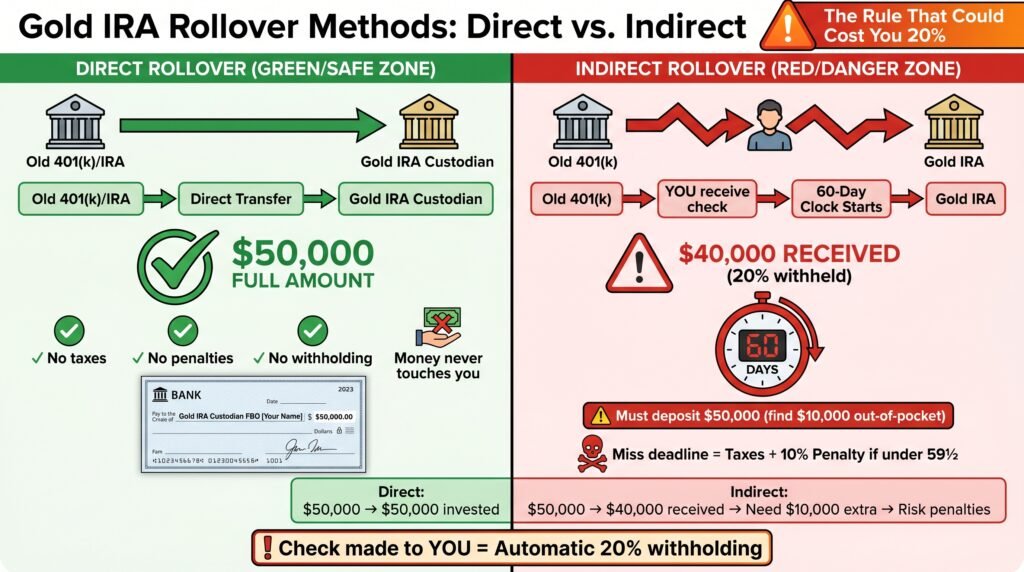
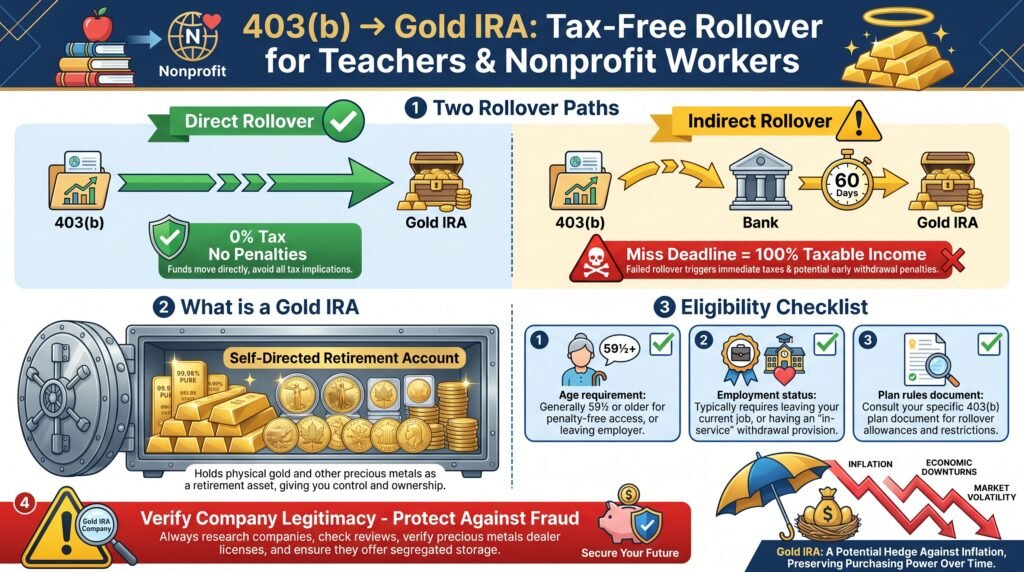
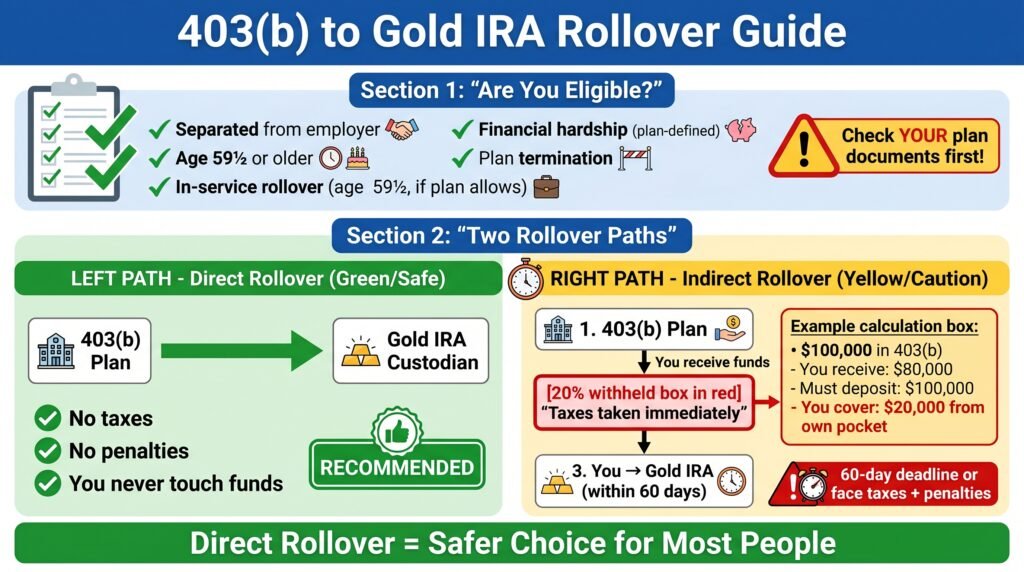
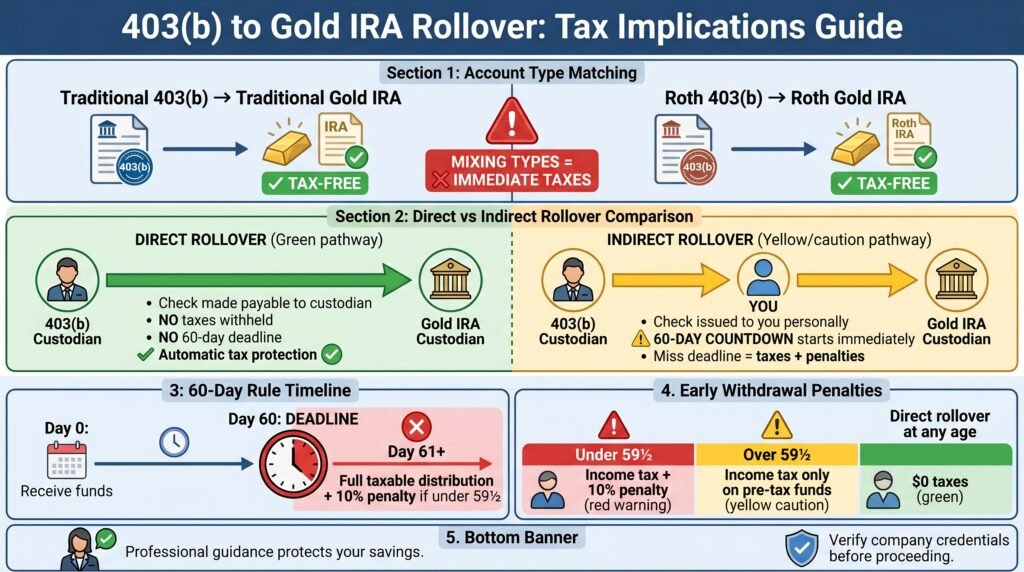
    Most existing 401(k)s, 403(b)s, and traditional IRAs can be rolled into a Gold IRA without triggering any tax consequences, as long as it’s handled correctly. The safest method is a direct, trustee-to-trustee transfer, where funds move straight from your existing custodian to your new Gold IRA custodian without passing through your hands.

    Avoid indirect rollovers if possible; those involve stricter deadlines and carry a higher risk of accidentally triggering taxes or penalties if the paperwork isn’t handled precisely.

    Does Gold Really Protect Against Inflation?

    Over long periods, gold has historically held its purchasing power better than cash, which is why it’s often described as an inflation hedge. During the stagflation era of the 1970s, for example, gold delivered roughly 35% annualized returns, making it one of the best-performing assets of that decade.

    That said, gold is not a guaranteed inflation hedge in the short run. Its relationship with inflation is strong over decades but noisy year to year, so don’t expect it to track every single inflation report in real time.

    Should I Buy Silver Along with Gold for Retirement?

    It depends on your timeline and risk tolerance. Silver has historically delivered higher gains than gold during precious metals bull markets, partly because its price is driven by both monetary demand and industrial use in solar panels, electric vehicles, semiconductors, and medical equipment.
    If you have a longer runway until retirement, adding silver at roughly 2%–5% of your total portfolio alongside a core gold position is a reasonable strategy worth considering. But silver’s volatility, typically two to three times larger than gold’s price swings, makes it a less suitable choice for retirees who are already drawing income and need more stability than growth potential.
    For investors within 5–10 years of retirement, or already withdrawing funds, gold should remain the primary or sole precious metal holding in the portfolio.

    Figuring out your exact number doesn’t have to be a solo project. Augusta Precious Metals works with retirement investors every day to build precious metals strategies that match their specific timeline, income needs, and comfort with risk.

    Get started with a tax-advantaged IRA with Augusta by clicking the banner below.
    Sources:
    Gold IRA Rules and Regulations: LendEDU

    Gold IRA storage rules: IRS requirements for storing precious metals: Yahoo!Finance

    Investments in collectibles in individually directed qualified plan accounts: IRS.gov: Retirement plans FAQs regarding IRAs: IRS.gov

  • How to Spot a Gold IRA Scam: The Skeptic’s Checklist for Vetting Gold IRA Companies in 2026

    How to Spot a Gold IRA Scam: The Skeptic’s Checklist for Vetting Gold IRA Companies in 2026

    How to Spot a Gold IRA Scam
    How to Spot a Gold IRA Scam

    Quick Summary

    Gold IRA scams follow a predictable playbook: fear-based pitches about economic collapse, companies with no verifiable track record, deliberately confusing rollover structures, and vague or hidden fees/custodian details.

    Legitimate providers use IRS-approved custodians and depositories, only sell IRS-eligible metals (e.g., Gold Eagles, Maple Leafs, .995+ bars), disclose all fees in writing (typically $50–150 setup, $75–300/year custodian, $100–300/year storage, 1–5% spread), and welcome direct questions. If a company dodges the six key questions- spread, custodian, depository, agent compensation, IRS eligibility code, and full fee breakdown- walk away.

    Table of Contents

    1. Quick Summary
    2. Fear-Based Claims About Economic Collapse
    3. No Verifiable Business History or Independent Reviews
    4. Complex Structures You Cannot Clearly Explain to Someone Else
    5. No Written Fee Disclosures or Refusal to Identify Custodians and Storage
    6. How Legitimate Gold IRA Investing Actually Works
    7. A Dealer That Checks Out Will Welcome Your Questions, Not Dodge Them
    8. Frequently Asked Questions
    Fear-Based Claims About Economic Collapse
    Fear-Based Claims About Economic Collapse

    1. Fear-Based Claims About Economic Collapse

    “The dollar is collapsing.” “Hyperinflation is coming.” “Your paper assets will be worthless.” These statements are engineered to create emotional urgency, and they are among the most commonly used sales tactics in the gold IRA industry. Fear sells. And in an industry with limited regulatory oversight, there is very little stopping a motivated sales agent from turning market anxiety into a closing tool.

    How Doomsday Marketing Clouds Financial Judgment

    When a sales pitch leads with catastrophic economic predictions, it is designed to make any rational evaluation of the actual product feel secondary. If the world is ending financially, who has time to ask about spreads, custodian fees, or IRS eligibility rules? That is exactly the point. Fear-based framing shifts your attention from due diligence to self-preservation, and in that emotional state, very expensive decisions get made very quickly.

    2. No Verifiable Business History or Independent Reviews

    A gold IRA company that cannot be independently verified is a company you should not trust with your retirement savings. Every legitimate precious metals dealer operating in the United States should have a traceable business history, verifiable physical address, named leadership, and a meaningful record of customer reviews on third-party platforms, not just testimonials hand-picked for their own website.

    The absence of this information is not a minor inconvenience. It is a structural red flag. New companies with no track record, companies operating under recently changed names, and dealers who cannot provide references or verifiable credentials represent serious risk. In an industry where transactions regularly involve six-figure retirement rollovers, anonymity is never acceptable.

    How to Vet a Gold IRA Company Before Handing Over Any Money

    Before engaging with any gold IRA provider, run through this verification checklist systematically. Do not skip steps because a sales agent sounds confident or a website looks professional; visual polish is inexpensive and tells you nothing about trustworthiness.

    • Search the company name on the Better Business Bureau website and review both their rating and the full complaint history
    • Check the Business Consumer Alliance for precious metals dealer ratings and documented disputes
    • Search the CFTC and SEC enforcement databases for any regulatory actions against the company or its principals
    • Look up the company on Trustpilot and Google Reviews, read negative reviews specifically to identify patterns
    • Confirm the physical business address using Google Maps Street View and cross-reference it with state business registration records
    • Ask directly for the name of the IRS-approved custodian they work with and verify that custodian independently
    • Request references from existing clients and actually follow up on them

    A company with nothing to hide will support every single step of this process. Resistance to any part of it, particularly around custodian identity or fee documentation, should stop the conversation entirely until full transparency is provided in writing

    Complex Structures You Cannot Clearly Explain to Someone Else
    Complex Structures You Cannot Clearly Explain to Someone Else

    3. Complex Structures You Cannot Clearly Explain to Someone Else

    There is a reliable rule in financial decision-making: if you cannot explain an investment structure clearly to someone else, you do not understand it well enough to put your retirement savings into it. Gold IRA transactions that involve multiple layers of companies, vague rollover processes, or custodian arrangements that are difficult to trace are not sophisticated; they are designed to obscure what is actually happening to your money.

    Complexity in financial products is frequently a feature, not a bug, for bad actors. The harder a structure is to follow, the easier it is to hide fees, inflate markups, misrepresent IRS rules, and move money through arrangements that benefit the seller far more than the buyer. If a gold IRA company’s process feels confusing after a full explanation, ask them to simplify it. If they cannot, or will not, that is your answer.

    Self-Directed IRA Rollover Scams Regulators Have Specifically Warned About

    Self-directed IRAs give investors the ability to hold alternative assets, including physical gold and silver, inside a tax-advantaged retirement account. That flexibility is legitimate and potentially valuable. But it also creates an environment where bad actors can operate with fewer guardrails than exist in traditional brokerage accounts.

    Regulators have documented a consistent pattern in gold IRA fraud cases involving self-directed IRAs: investors are encouraged to roll over large portions — or in extreme cases, the entirety — of their existing retirement accounts into precious metals without being given a clear picture of the costs, tax implications, or structural risks involved. The rollover process itself is presented as simple and routine when it is anything but.

    The most common misrepresentations made during self-directed IRA rollovers include:

    • Claims that moving 100% of a retirement portfolio into gold is a standard and safe strategy
    • Statements that gold IRAs carry special tax advantages beyond those of other retirement accounts
    • Suggestions that IRA-owned metals can be stored at home — a clear IRS rule violation
    • Assurances that certain coins are protected from government seizure
    • Misrepresentation of the rollover timeline and its tax consequences if mishandled
    • Failure to disclose that self-directed IRA transactions may not carry the same investor protections as securities

    The CFTC Warnings Investors Need to Know

    The Commodity Futures Trading Commission has formally warned investors about gold IRA schemes in which retirement savers were encouraged to move large sums, including full retirement account balances, into precious metals accounts through high-pressure sales tactics. Their 2024 advisory specifically identified patterns of unsolicited contact, urgency-based selling, and misrepresentation of investment safety as hallmarks of fraudulent precious metals operations.

    The CFTC’s warnings are not theoretical. They reflect documented cases where real retirement investors lost significant portions of their savings to schemes that looked, on the surface, like legitimate gold IRA investments. Taking these warnings seriously and applying the red flags they describe to any gold IRA pitch you encounter is not paranoia. It is due diligence.

    Augusta Precious Metals is one example of an established precious metals provider that helps investors navigate the Gold IRA process.

    Receive a free gold IRA company checklist by clicking the banner below. Fill out their short form to get started.
    Free Gold IRA Guide
    Free Gold IRA Guide

    4. No Written Fee Disclosures or Refusal to Identify Custodians and Storage

    A reputable gold IRA provider will furnish written documentation that clearly identifies every cost associated with opening, maintaining, and eventually liquidating your account. This includes the one-time account setup fee (typically $50 to $150), annual IRA custodian fees (commonly $75 to $300 per year), storage fees charged by the approved depository (generally $100 to $300 annually, sometimes calculated as a percentage of holdings), transaction fees on purchases and sales, and any wire transfer or shipping costs associated with physical metal movement.

    If any of these line items are missing, ask for them specifically, and get the answers in writing before proceeding. To avoid potential pitfalls, be sure to familiarize yourself with gold and silver investing scams that could impact your investment.

    Custodian and Storage Requirements the IRS Actually Mandates

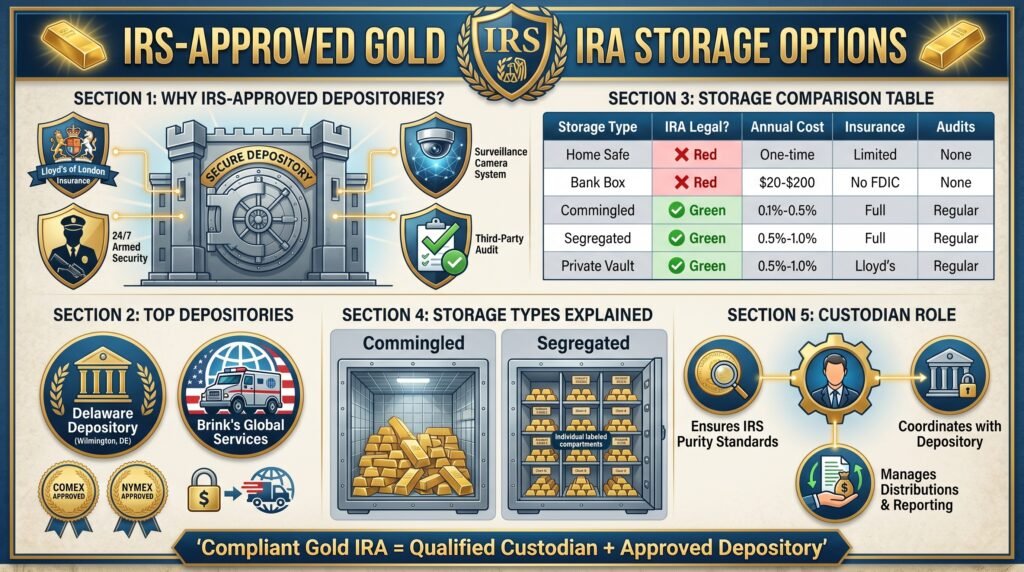
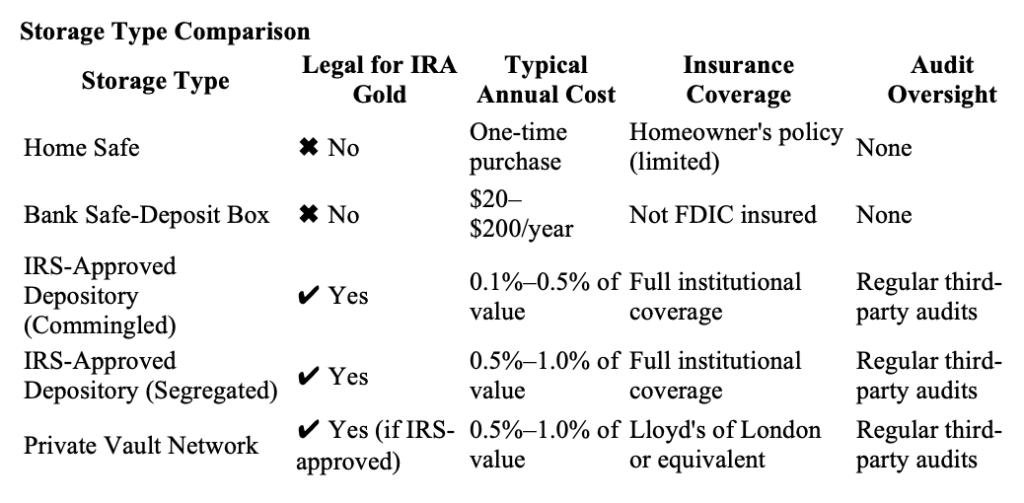
    Under IRS rules, physical gold held inside an IRA must be stored with an IRS-approved custodian, not at your home, not in a personal safe, and not with the dealer who sold it to you. The custodian must be a bank, federally insured credit union, savings and loan association, or another entity specifically approved by the IRS under Internal Revenue Code Section 408(a). Any company suggesting otherwise is either misinformed or deliberately misleading you about tax compliance requirements.

    Approved storage facilities for IRA-held gold include well-established depositories such as the Delaware Depository, Brinks Global Services, and the International Depository Services Group. Your gold IRA company should be able to name its storage partner immediately and provide documentation confirming the arrangement. If the storage location is vague, unnamed, or described as a proprietary facility you cannot independently verify, treat that as a serious compliance and security concern.

    How Legitimate Gold IRA Investing Actually Works
    How Legitimate Gold IRA Investing Actually Works

    How Legitimate Gold IRA Investing Actually Works

    Understanding what a legitimate gold IRA looks like makes it significantly easier to identify when something is off. A properly structured gold IRA follows a clear, documented process, one that involves an IRS-approved custodian, an approved depository, IRS-eligible metal products, and full written disclosure of every fee before any transaction is completed. The entire structure is designed to keep your retirement savings protected under the same tax-advantaged framework as a traditional IRA.

    The Role of an IRS-Approved Custodian

    The custodian is the financial institution responsible for holding your IRA assets, maintaining IRS compliance, processing transactions on your behalf, and providing required account reporting. In a gold IRA, the custodian does not physically hold your gold; that function belongs to the approved depository. But the custodian oversees the entire structure and carries fiduciary responsibility for the account’s regulatory compliance. You should be able to contact your custodian independently and receive direct answers about your account at any time.

    Approved Gold Types for IRA Accounts

    The IRS is specific about which gold products qualify for inclusion in a self-directed IRA. Meeting these standards is non-negotiable for tax compliance. Approved products include:

    • American Gold Eagle coins (the only gold coin allowed at slightly below .999 purity — at .9167 fine gold, due to a specific IRS exception)
    • American Gold Buffalo coins (.9999 fine gold)
    • Canadian Gold Maple Leaf coins (.9999 fine gold)
    • Austrian Gold Philharmonic coins (.9999 fine gold)
    • Australian Gold Kangaroo/Nugget coins (.9999 fine gold)
    • Gold bars and rounds produced by NYMEX- or COMEX-approved refiners meeting .995 minimum fineness

    Any gold product that does not meet these specific purity standards, or that falls into the collectible or numismatic category, is not IRA-eligible. This is not a gray area. The IRS code is unambiguous, and any dealer suggesting otherwise is wrong or deliberately misleading you.

    It is worth noting that even American Gold Eagle coins, which carry a face value and government backing, are valued for IRA purposes based on their gold content, not their numismatic or collector value. The distinction matters because it reinforces why chasing “rare” coins inside a retirement account structure is both financially counterproductive and potentially non-compliant.

    If you are ever uncertain whether a specific product qualifies, the IRS Publication 590-A covers IRA contribution and asset rules in detail, and an independent tax professional can confirm eligibility before any purchase is made. Do not rely solely on the dealer’s word on this question.

    Realistic Costs You Should Expect from a Reputable Provider

    A well-structured gold IRA will involve real costs, and a trustworthy company will present them clearly upfront. Expect a one-time setup fee in the range of $50 to $150, annual custodian fees between $75 and $300, annual storage fees from $100 to $300 (or a percentage of assets under custody), and a dealer spread on purchases typically between 1% and 5% above spot price for standard bullion.

    Any cost structure that deviates dramatically from these ranges, particularly on the spread, warrants direct questioning and written justification before you proceed.

    If you want a full gold IRA integrity checklist from one of the most reputable companies within this space, access their checklist by clicking the banner below and fill out their short contact form to get started.

    A Dealer That Checks Out Will Welcome Your Questions, Not Dodge Them

    The Six Questions Every Gold IRA Investor Should Ask Before Committing:

    1. What is your exact spread above spot price on this product, and will you put that in writing?
    2. Which IRS-approved custodian will hold my account, and how do I contact them directly?
    3. Which approved depository will store my metals, and what are the storage fees?
    4. Is my sales agent paid on commission, and if so, on which products?
    5. Can you provide the specific IRS code that confirms this product is IRA-eligible?
    6. What are every fee, including liquidation costs, associated with this account from open to close?

    These questions are not aggressive or unusual. They are the baseline of informed financial decision-making. A company that responds to any of them with defensiveness, vague language, or redirected sales talk has just told you everything you need to know about how they operate. To understand more about the potential pitfalls, you might want to explore gold and silver investing scams that some investors have faced.

    The right gold IRA company will answer all six questions directly, provide written documentation for each answer, and give you time to review everything with an independent financial advisor before making any commitment. That standard is not exceptionally high; it is simply the minimum that your retirement savings deserve.

    Gold can be a legitimate component of a diversified retirement strategy. The metal itself is not the problem. The problem is an industry where bad actors have learned that fear, urgency, and complexity are effective tools for separating retirement investors from their savings. Every red flag covered in this guide exists because someone used it successfully on an investor who did not see it coming. Now you do.

    If you want a complete gold IRA company integrity checklist, receive Augusta Precious Metals detailed guide by clicking the banner below to get started.

    Gold IRA Investment Guide
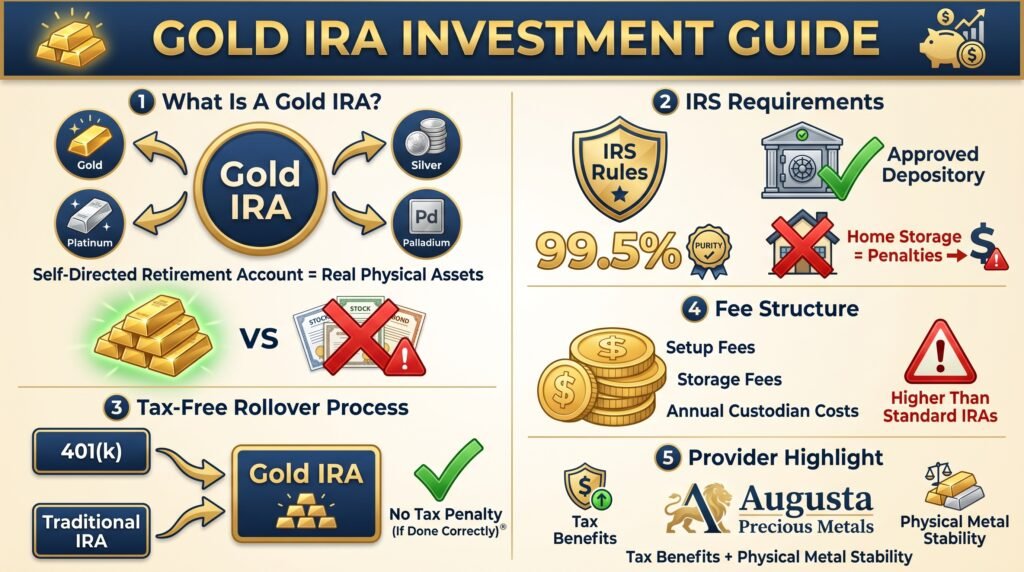
    Gold IRA Investment Guide

    Frequently Asked Questions

    The questions below address the most common points of confusion among investors researching gold IRAs, including several areas where deliberate misinformation is most frequently encountered.

    Each answer reflects current IRS rules and regulatory guidance. Where rules may have changed, or personal circumstances affect the answer, consultation with an independent tax or financial professional is always the recommended next step before taking action.

    Can I roll over my existing 401(k) or IRA into a Gold IRA?

    Yes, rolling over an existing 401(k) or traditional IRA into a gold IRA is a legitimate transaction under IRS rules when executed correctly. A direct rollover, where funds move directly from your existing custodian to the new gold IRA custodian without passing through your hands, is the cleanest method and avoids triggering any immediate tax liability or early withdrawal penalties.

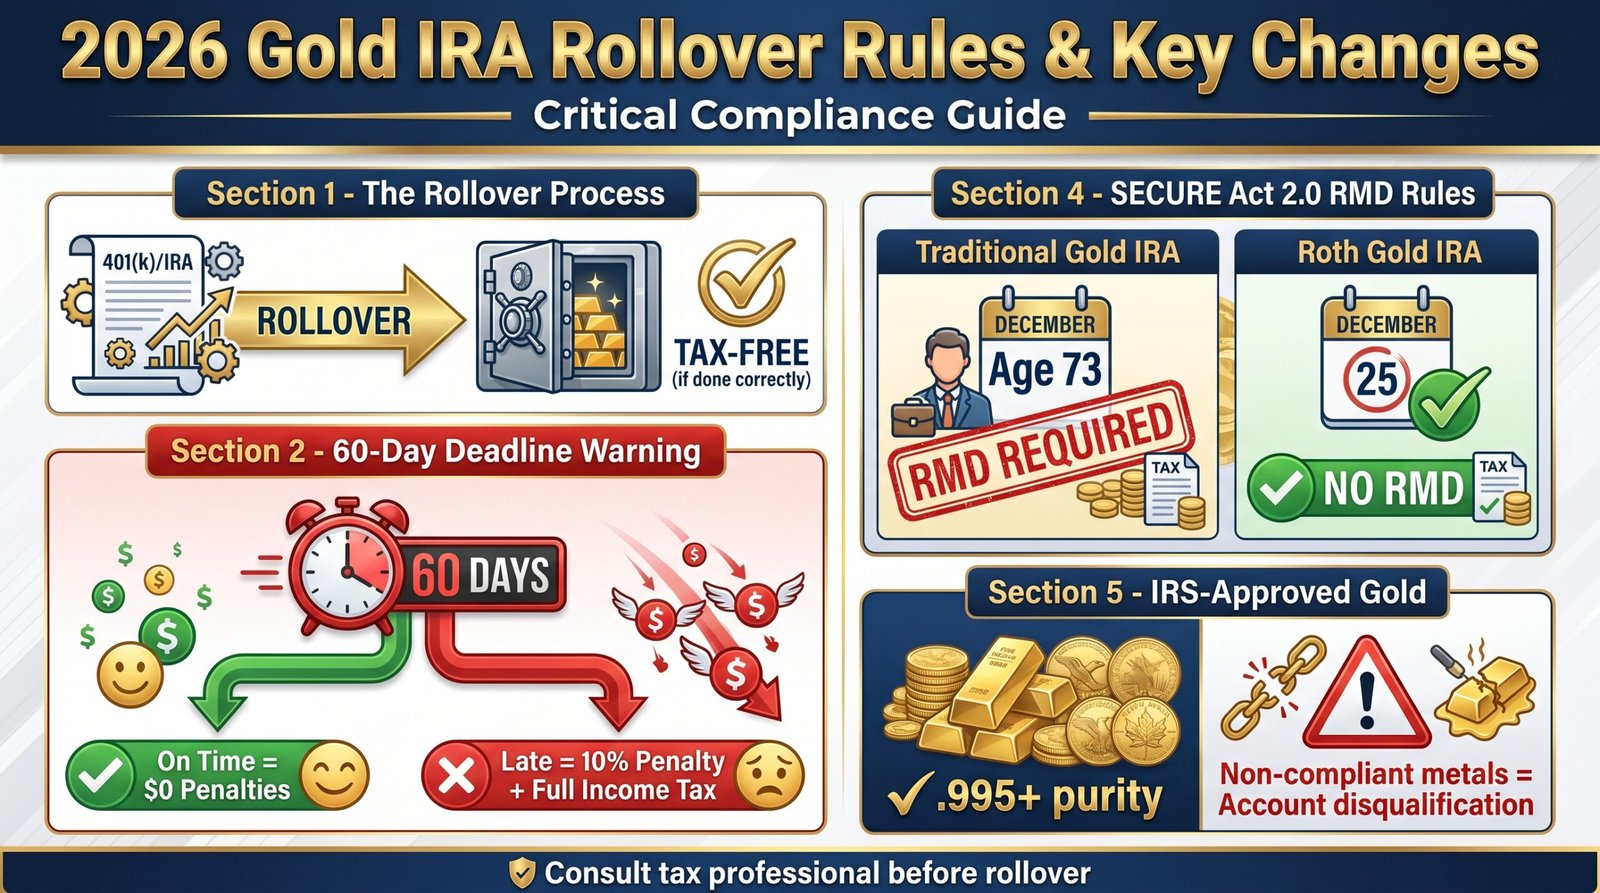
    An indirect rollover, where you receive the funds personally and then deposit them into the new account, must be completed within 60 days to avoid the distribution being treated as taxable income and potentially subject to early withdrawal penalties if you are under 59½.

    What matters most in evaluating a rollover offer is not whether it is technically possible but whether the company presenting it is giving you a complete and accurate picture of the costs, timeline, tax implications, and the specific products your rollover funds will purchase.

    What fees should I expect from a reputable Gold IRA company?

    A reputable gold IRA will involve several distinct fee categories that a legitimate provider will disclose fully in writing before any transaction. Account setup fees typically run between $50 and $150 as a one-time charge. Annual IRA custodian fees generally range from $75 to $300 per year, depending on the custodian and account size. Storage fees charged by the approved depository commonly fall between $100 and $300 annually, though some depositories charge a percentage of assets under storage instead of a flat fee.

    Transaction fees apply when buying or selling metals inside the account. Wire transfer fees and shipping or insurance costs may apply when metals are moved. And the dealer spread, the markup above spot price on each purchase, should always be disclosed as a specific percentage before any purchase is confirmed. Any fee structure that cannot be fully documented in writing before you commit funds is a red flag requiring immediate clarification.

    Has the CFTC issued warnings about Gold IRA scams?

    Yes. The Commodity Futures Trading Commission has formally issued warnings about fraudulent and deceptive practices in the precious metals and gold IRA space.

    Their advisories have specifically identified patterns of investor harm involving self-directed IRA rollovers, pressure-based sales tactics, and misleading representations about the safety and structure of gold IRA investments.

    -Investors being encouraged to roll over entire retirement account balances into precious metals

    -High-pressure sales tactics creating artificial urgency around rollover decisions

    -Misrepresentation of gold IRAs as uniquely safe, protected, or government-backed investments

    -Unsolicited outreach through phone calls, email, and online communities targeting retirement-age investors

    -False claims about IRS rules, including suggestions that home storage of IRA-owned metals is permitted

    -Promotion of numismatic or rare coins as superior IRA investments without disclosing markup structures

    The CFTC’s 2024 advisory specifically flagged the pattern of investors being encouraged to complete rollovers quickly without fully understanding the costs or structural implications involved. These warnings reflect documented cases, not theoretical risks, where retirement investors experienced significant financial harm through schemes that presented themselves as legitimate gold IRA services.

    The CFTC operates the SmartCheck tool at SmartCheck.gov, which allows investors to verify whether a company or individual is registered with the CFTC and to check for any regulatory actions or fraud alerts associated with them.

    Using this resource before engaging with any gold IRA company is a straightforward step that costs nothing and could save your retirement savings.-

    Can I store Gold IRA metals at home?

    No. This is one of the most frequently misrepresented rules in the gold IRA space, and the answer from the IRS is unambiguous. Physical metals held inside an IRA must be stored with an IRS-approved custodian arrangement, specifically, at an approved third-party depository.

    Storing IRA-owned gold at home, in a personal safe, in a bank safe deposit box in your own name, or anywhere outside of an IRS-approved depository constitutes a distribution of the asset from the IRA. That distribution triggers immediate income tax on the full value of the metals plus a 10% early withdrawal penalty if you are under age 59½.

    Any company or promoter suggesting that a home storage gold IRA is a legal IRS-approved structure is either wrong or deliberately misleading you — and following that advice can result in a significant and irreversible tax liability.

    What should written fee disclosures from a Gold IRA company include?

    A complete written fee disclosure from a reputable gold IRA company should itemize every cost associated with opening, maintaining, transacting within, and eventually closing or liquidating your account.

    This means the one-time account setup fee, the annual custodian fee, the annual storage fee (specified as either a flat rate or percentage of assets), transaction fees for purchases and sales, wire transfer fees, shipping and insurance costs for metal movement, and the dealer’s spread above spot price on each product type available for purchase. Nothing should be described in vague terms like “competitive pricing” or “industry-standard fees” without specific numbers attached.

    Liquidation costs are particularly important to request in writing upfront, because many investors focus on purchase fees and do not consider what it will cost to sell their gold when the time comes.

    A company that is transparent about liquidation pricing, including whether they offer buyback programs and at what price relative to spot, is demonstrating a level of honesty about the full transaction cycle that commission-driven operations typically avoid. If any fee category is missing from the written disclosure you receive, request it specifically and do not proceed until it is documented in writing.

    How do I report a suspected Gold IRA scam?

    If you believe you have encountered or been victimized by a fraudulent gold IRA operation, report it to multiple regulatory bodies simultaneously. File a complaint with the Commodity Futures Trading Commission through their online portal at cftc.gov/complaint. Report to the Federal Trade Commission at ReportFraud.ftc.gov.

    File a complaint with your state’s attorney general’s office, which often has a dedicated consumer protection or securities fraud division. If the scheme involved securities or investment advice, report it to the SEC at sec.gov/tcr. Contact the Internet

    Crime Complaint Center (IC3) at ic3.gov if the fraud involved online communications. Document everything, save all emails, record call details, and retain all written materials and contracts before filing reports, as this documentation will support any investigation that follows.

    Sources:

    Augusta Precious Metals – 5 Questions to Ask Before Choosing a Gold IRA Company

    USA Today: Gold and silver investing scams: Red flags and how to protect yourself
    https://www.usatoday.com/story/money/investing/gold-and-silver-investing-scams/88744022007/

  • Gold IRA Red Flags and Sales Tactics to Avoid – Top 5 Warning Signs (2026 Guide)

    Gold IRA Red Flags and Sales Tactics to Avoid – Top 5 Warning Signs (2026 Guide)

    Gold IRA Red Flags and Sales Tactics to Avoid – Top 5 Warning Signs
    Gold IRA Red Flags and Sales Tactics to Avoid – Top 5 Warning Signs

    Quick Summary

    • Not all gold IRA companies operate transparently; hidden markups, commission-driven agents, and pressure tactics are common warning signs that your retirement savings are at risk.
    • The CFTC has issued formal warnings about gold IRA schemes that push full retirement account rollovers into precious metals using fear-based sales pitches.
    • Legitimate gold IRA investments require IRS-approved custodians, third-party storage, and clear written fee disclosures; any company that skips these steps is a major red flag.
    • One of the most overlooked dangers is the push toward numismatic or “rare” coins, which carry massive markups and are generally not IRA-eligible under IRS rules.
    • Keep reading to discover the nine specific warning signs, including one fee structure almost no one asks about that can quietly cost you tens of thousands of dollars.

    The gold IRA industry has a serious problem, and it is not the metal itself; it is the salespeople selling it.

    As economic uncertainty keeps more retirement-focused Americans looking for ways to protect their savings, the gold IRA market has grown, and so has the number of bad actors operating inside it.

    Platforms like Augusta Precious Metals have highlighted how complex gold IRA structures make it easier for dishonest dealers to obscure fees, misrepresent IRS rules, and pressure investors into decisions they later regret. Understanding these red flags is not optional; it is essential for protecting your financial future.

    If you are researching gold IRAs or advising clients who are, this guide breaks down every major warning sign in plain terms so you can make, or recommend, decisions with full clarity.

    Table of Contents

    1. Quick Summary
    2. Guaranteed or “Risk-Free” Returns on Gold
    3. High-Pressure Tactics That Rush Your Decision
    4. Markups Far Above the Spot Price of Gold
    5. Pushing Rare or Numismatic Coins Over Bullion
    6. Unsolicited Gold IRA Offers Through Email, Phone, or Online Ads
    7. Frequently Asked Questions

    1. Guaranteed or “Risk-Free” Returns on Gold

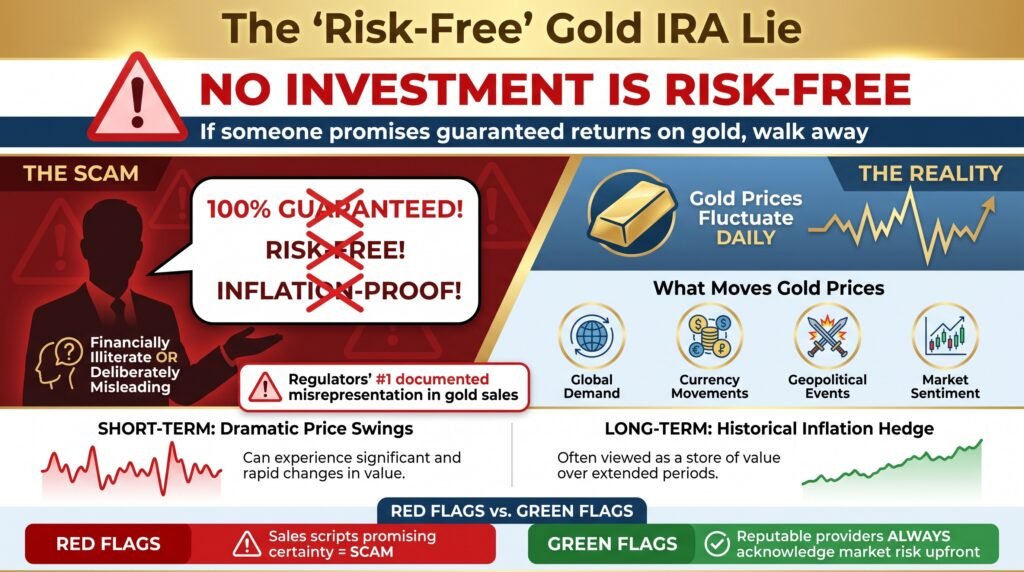
    No investment is risk-free. Full stop. Gold prices fluctuate daily based on global demand, currency movements, geopolitical events, and market sentiment. Any company or sales agent who describes a gold IRA as a “guaranteed” or “risk-free” investment is either financially illiterate or deliberately misleading you, and neither option is acceptable when your retirement savings are involved. To understand more about these practices, you can read about gold and silver investing scams.

    This is one of the most common misrepresentations documented by regulators. Sales scripts frequently include language designed to make gold sound uniquely protected or inflation-proof in absolute terms. While gold has historically served as a hedge against inflation over long time horizons, short-term price swings can be dramatic. The pitch of certainty is the lie. A reputable provider will always acknowledge market risk clearly and upfront.

    2. High-Pressure Tactics That Rush Your Decision

    If a gold IRA company is pushing you to act today, that pressure is a sales weapon, not a service. Legitimate investments do not expire overnight, and no credible financial product requires a same-day decision on your retirement savings.

    Why Urgency Is a Weapon, Not a Service

    High-pressure sales tactics in the gold IRA space typically sound like: “This price is only available until the end of business today,” or “The window to protect your IRA is closing fast.” These statements are engineered to bypass your rational evaluation process. The CFTC has specifically flagged scenarios where investors were encouraged to complete rollovers quickly without fully understanding the costs or structure involved, a pattern that consistently results in financial harm.

    Pressure combined with fear is especially effective on retirement-age investors who feel they are running out of time to protect their savings. Sales agents in commission-driven environments are trained to exploit that anxiety. Recognizing the tactic for what it is- a closing technique, not a genuine warning- gives you the power to step back and evaluate objectively.

    What Legitimate Dealers Do Instead

    Reputable gold IRA companies encourage you to take your time, review all documents, consult an independent financial advisor, and ask as many questions as you need. They provide written materials, clear fee schedules, and straightforward answers without manufactured urgency. If a company welcomes your questions and does not rush a single step of the process, that is a green flag, and it is rarer than it should be.

    Markups Far Above the Spot Price of Gold
    Markups Far Above the Spot Price of Gold

    3. Markups Far Above the Spot Price of Gold

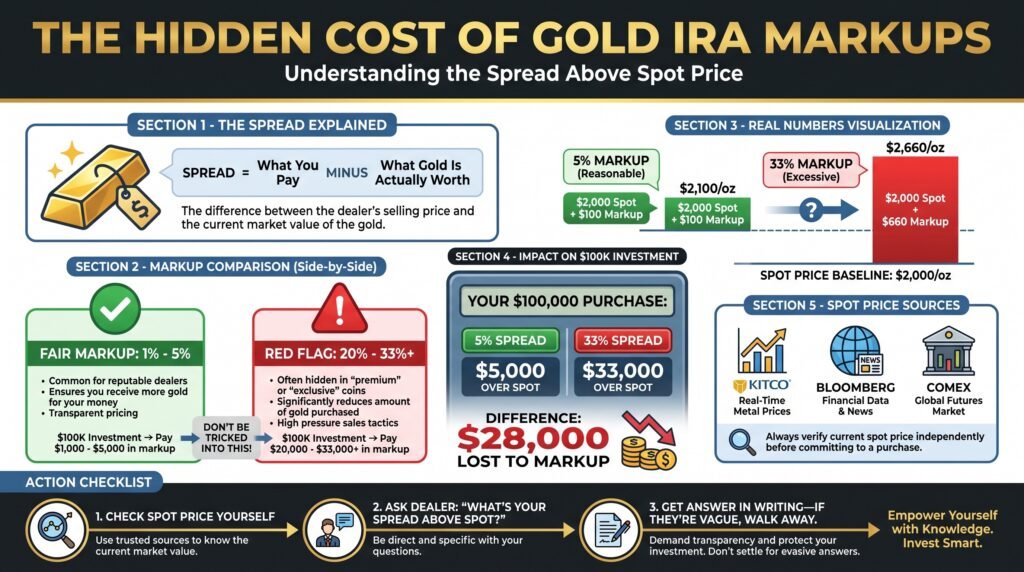
    The spread, the difference between what you pay for gold and what it is actually worth on the open market, is where many investors quietly lose significant money without ever realizing it. Most gold IRA companies are not eager to discuss this number. That silence should tell you something.

    Reputable dealers typically charge a spread somewhere in the range of 1% to 5% above the spot price for standard bullion products. When that number climbs to 20%, 30%, or higher, which happens more often than most investors expect, the math on your investment changes dramatically before your gold even arrives in storage.

    Real-World Markup Example:
    Spot price of gold: $2,000 per troy ounce
    Dealer price with 5% spread: $2,100 per ounce: reasonable and transparent
    Dealer price with 33% spread: $2,660 per ounce: a red flag requiring immediate scrutiny
    On a $100,000 purchase, that difference represents $28,000 in hidden costs before any fees are applied.

    What Is the Spot Price and Why It Matters

    The spot price is the current market price at which gold can be bought or sold for immediate delivery. It is publicly available in real time through financial platforms like Kitco, Bloomberg, and the COMEX exchange. Every gold IRA transaction should be priced in direct reference to this number. When a company is vague about how their pricing relates to spot, or refuses to show you the calculation, walk away.

    How to Check If You Are Being Overcharged

    Before committing to any gold IRA purchase, pull the current spot price from a neutral third-party source. Then ask your dealer directly: “What is your spread above spot price on this product?” A trustworthy company will answer immediately and in writing. If the response is evasive, indirect, or buried in marketing language about “exclusive pricing,” treat that as a serious warning sign and request full written disclosure before proceeding.

    Augusta Precious Metals is one example of an established precious metals provider that helps investors navigate the Gold IRA process.

    Receive a free gold IRA company checklist by clicking the banner below. Fill out their short form to get started.
    Free Gold IRA Guide
    Free Gold IRA Guide

    4. Pushing Rare or Numismatic Coins Over Bullion

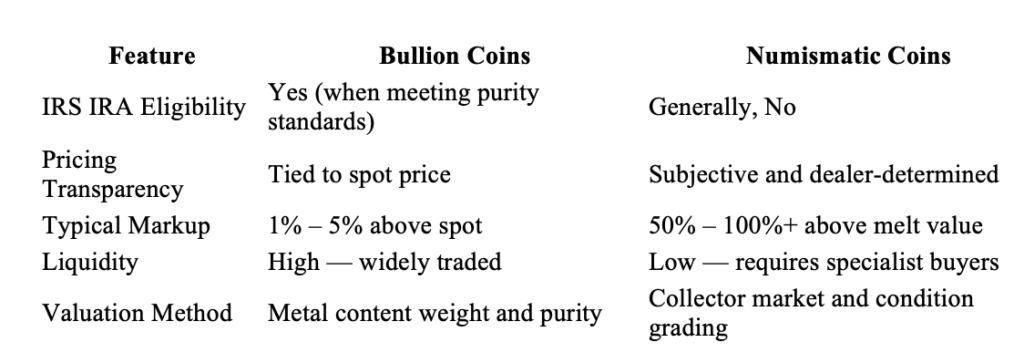
    One of the most sophisticated bait-and-switch tactics in the gold IRA industry involves steering investors away from standard bullion coins and toward “rare,” “exclusive,” or “collector” coins, also known as numismatic coins. The pitch often sounds compelling: these coins are supposedly more valuable, harder to find, or even protected from government seizure. Nearly all of these claims are misleading at best.

    What the sales agent is less likely to mention is that numismatic coins carry markups that can reach 100% or more above their actual metal content value, and that the IRS generally does not allow collectible coins inside a gold IRA. Pushing these products into a retirement account structure is not just a financial red flag; it can create serious tax compliance problems for the investor.

    The Difference Between Numismatic and Bullion Coins for IRA Investors

    Bullion coins derive their value primarily from their precious metal content. Their price tracks closely with the spot price of gold or silver. Numismatic coins derive value from rarity, historical significance, and collector demand, factors that are highly subjective, illiquid, and nearly impossible to verify independently without expert appraisal. Be aware of potential gold and silver investing scams when considering these options.

    IRS-approved bullion coins for gold IRAs include the American Gold Eagle (at specific purity levels), the Canadian Gold Maple Leaf, the Austrian Philharmonic, and gold bars or rounds meeting a minimum purity standard of .995 fine gold. If a dealer is pushing anything outside of these clearly defined categories, ask for the specific IRS code citation that makes that product eligible, and expect a very uncomfortable silence in response.

    Why Collectible Coins Are a Common Bait-and-Switch Tool

    The profit margin on numismatic coins is vastly higher than on standard bullion. A sales agent earning commission has enormous financial incentive to move you toward a $3,000 “rare” coin with $800 in actual gold content rather than a standard bullion coin priced at a 3% premium. The language around these products is carefully crafted to make exclusivity feel like protection. It is not. It is a margin play at your expense.

    Any unsolicited mention of coins being “rare,” “limited edition,” “government seizure-proof,” or “insider access” products should trigger immediate skepticism. These phrases exist in sales scripts specifically because they work on investors who are not yet familiar with how gold IRA eligibility rules actually function.

    5. Unsolicited Gold IRA Offers Through Email, Phone, or Online Ads

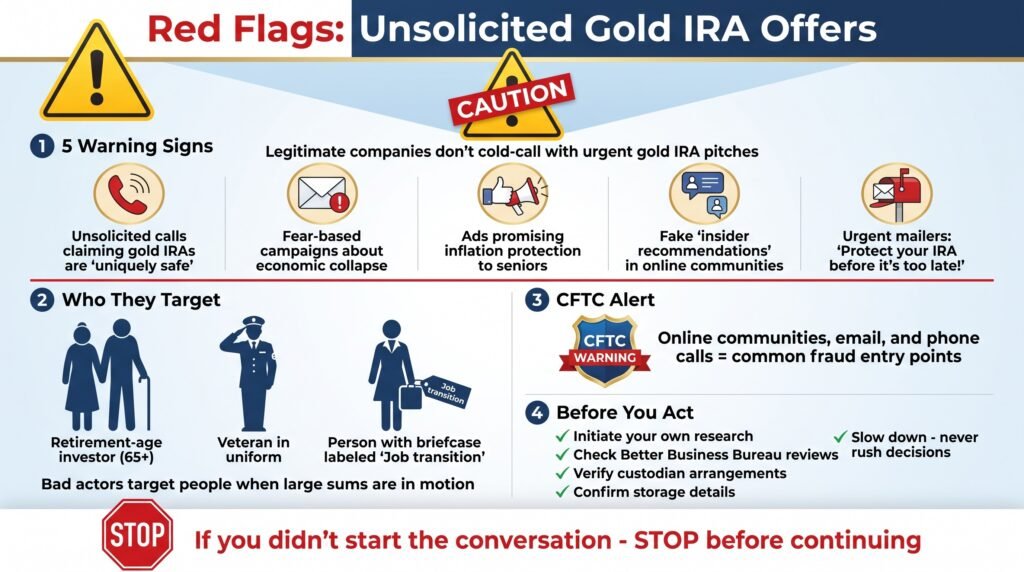
    Legitimate financial companies do not cold-call retirement investors with urgent gold IRA pitches. If you received an offer you did not seek out, through a phone call, an unsolicited email, a social media advertisement, or an online community post, treat it with significant caution. The CFTC has specifically identified targeted marketing through online communities, email outreach, and phone calls as a common entry point for gold IRA fraud schemes.

    • Unsolicited phone calls promoting gold IRAs as uniquely safe retirement vehicles
    • Email campaigns using economic fear language to drive rollover decisions
    • Social media ads targeting older adults with promises of inflation protection
    • Online community posts presenting gold IRA companies as insider recommendations
    • Mailers or postcards with urgent language about protecting your IRA “before it’s too late”

    The targeting is not random. Bad actors in this space specifically pursue retirement-age investors, veterans, and individuals who have recently experienced job changes or major life transitions, moments when large sums of money are in motion and decisions are being made quickly. If you did not initiate the conversation, slow down before you continue it.

    Even if the company behind an unsolicited offer turns out to be legitimate, the tactic itself reflects a sales culture that prioritizes acquisition over your best interests. Start your own research on your own terms. Independent reviews, third-party verification through the Better Business Bureau, and direct confirmation of custodian and storage arrangements should always come before any money moves.

    Learn about 4 additional, but lesser-known, red flags to be aware of when selecting a gold IRA company here.

    If you want a full gold IRA integrity checklist from one of the most reputable companies within this space, access their checklist by clicking the banner below and fill out their short contact form to get started.

    Frequently Asked Questions

    The questions below address the most common points of confusion among investors researching gold IRAs, including several areas where deliberate misinformation is most frequently encountered.

    Each answer reflects current IRS rules and regulatory guidance. Where rules may have changed, or personal circumstances affect the answer, consultation with an independent tax or financial professional is always the recommended next step before taking action.

    What is a Gold IRA and how does it differ from a regular IRA?

    A gold IRA is a self-directed individual retirement account that holds physical precious metals, such as gold bullion coins or bars, instead of or in addition to traditional paper assets like stocks, bonds, and mutual funds. It operates under the same IRS tax rules as a traditional or Roth IRA, including the same contribution limits, distribution rules, and required minimum distribution schedules.

    The key structural difference is that a gold IRA requires a specialized IRS-approved custodian who is set up to manage alternative assets, and it requires an approved third-party depository to physically store the metals. You cannot use a standard brokerage account to hold physical gold inside an IRA, and you cannot store IRA-owned gold yourself.

    The tax treatment of a gold IRA depends on whether it is structured as a traditional IRA or a Roth IRA. In a traditional gold IRA, contributions may be tax-deductible, and growth is tax-deferred until withdrawal. In a Roth gold IRA, contributions are made with after-tax dollars, and qualified withdrawals in retirement are tax-free.
    One critical distinction that is frequently misrepresented by gold IRA sales agents: a gold IRA does not offer any special or additional tax advantages beyond those of any other IRA structure. The tax benefits come from the IRA wrapper, not from the gold itself. Any pitch suggesting otherwise is inaccurate.

    Are Gold IRAs a safe investment?

    Gold IRAs are not inherently safe or unsafe; the answer depends entirely on how they are structured, who is managing them, and what products are inside the account. Physical gold held inside a properly structured self-directed IRA with an IRS-approved custodian and an approved depository is a legitimate retirement investment. The danger is not the metal. The danger is the industry built around selling it, where misleading tactics, hidden markups, and pressure-based sales practices create significant financial risk for investors who do not know what to look for.

    Over very long-time horizons, gold has preserved purchasing power reasonably well, but it has also experienced extended periods of flat or declining value. A well-managed gold IRA with transparent fees, IRS-eligible products, and realistic expectations about performance can serve a legitimate diversification role inside a retirement portfolio. An overpriced, poorly disclosed gold IRA sold through high-pressure tactics can quietly destroy retirement savings.

    What is the spot price of gold and why does it matter when buying?

    The spot price of gold is the current market price at which one troy ounce of gold can be bought or sold for immediate delivery on the open market. It is determined continuously by trading activity on major commodities exchanges, including the COMEX division of the New York Mercantile Exchange and the London Bullion Market Association.

    The spot price is publicly available in real time through financial data platforms including Kitco, Bloomberg, and Reuters, and it changes throughout the trading day based on global supply and demand dynamics, currency movements, interest rate expectations, and broader market sentiment. Understanding these dynamics can help you avoid gold investing scams.

    For gold IRA investors, the spot price is the essential reference point for evaluating every purchase. The spread, the amount above spot that a dealer charges for a specific coin or bar, is where your actual cost lives. A reputable dealer will charge a transparent, documented spread typically in the range of 1% to 5% above spot for standard bullion products.

    When that spread is hidden, vague, or dramatically higher than market norms, the investor absorbs the difference as an immediate loss on the value of their investment. Before completing any gold IRA purchase, pull the current spot price from a neutral third-party source and calculate exactly what premium above spot you are being asked to pay, then get that number confirmed in writing.

    How do I know if a gold IRA company is legitimate?

    Gold IRA Company Legitimacy Checklist:

    ✓ Verifiable physical business address confirmed through independent sources
    ✓ Named leadership with traceable professional backgrounds
    ✓ Accredited with the Better Business Bureau with a clear complaint history
    ✓ Listed and reviewed on Business Consumer Alliance
    ✓ No enforcement actions in CFTC or SEC regulatory databases
    ✓ Named IRS-approved custodian that can be contacted independently
    ✓ Named approved storage depository with documented fee schedule
    ✓ Full written fee disclosure provided before any transaction
    ✓ Spread above spot price disclosed in writing on request
    ✓ No pressure tactics, manufactured urgency, or fear-based language

    Legitimacy in the gold IRA space is confirmed through independent verification, not through a company’s own marketing materials, website testimonials, or the confidence of its sales agents. Any company can build a professional-looking website and script a compelling phone pitch. What separates legitimate operations from fraudulent ones is their willingness to be verified externally at every level of their business.

    The Better Business Bureau and Business Consumer Alliance are your first stops. Search the company name, not just the brand, but any parent company or doing-business-as names associated with it. Read the full complaint history, not just the rating. A company with an A+ rating but thirty unresolved complaints about billing disputes or delivery problems is telling you something important through that complaint record that the letter grade does not capture.

    Next, confirm the custodian. Every gold IRA requires an IRS-approved custodian, and a legitimate company will name that custodian immediately and without hesitation.

    Finally, run the company name and its principals through the CFTC’s enforcement database and the SEC’s EDGAR and enforcement records. Regulatory actions, consent orders, and fraud findings are public record. If anything comes up, walk away without further engagement. If nothing comes up, you have at least confirmed the absence of a documented regulatory history, which combined with all other verification steps, gives you a reasonable foundation for further evaluation.

    If you want a complete gold IRA company integrity checklist, receive Augusta Precious Metals detailed guide by clicking the banner below to get started.

    Gold IRA Investment Guide
    Gold IRA Investment Guide

    Sources:

    Augusta Precious Metals – 5 Questions to Ask Before Choosing a Gold IRA Company

    USA Today: Gold and silver investing scams: Red flags and how to protect yourself
    https://www.usatoday.com/story/money/investing/gold-and-silver-investing-scams/88744022007/

  • Top 3 Gold IRA Companies in 2026 for Small Investors (Under $25K)in 2026

    Top 3 Gold IRA Companies in 2026 for Small Investors (Under $25K)in 2026

    Top 3 Gold IRA Companies for Small Investors (Under $10,000)
    Top 3 Gold IRA Companies for Small Investors (Under $10,000)

    Quick Summary

    You don’t need $25K to open a gold IRA — National Gold Group, Birch Gold Group, and American Hartford Gold all accept accounts starting around $10,000. National Gold Group is best for personalized guidance; Birch Gold Group excels at rollover support and metal variety; American Hartford Gold wins on low ongoing costs (~$175/year) and a flat-fee structure that doesn’t penalize smaller investors. Before opening, factor in that flat annual fees (~$175–$180) represent ~1.8% of a $10K account, so a long-term hold strategy and planned contributions make the most sense.

    Table of Contents

    1. Quick Summary
    2. The best gold IRA providers that welcome accounts under $10,000 and won’t turn you away for being a smaller investor.
    3. Top 3 Gold IRA Companies for Small Investors
      • 1. National Gold Group
      • 2. Birch Gold Group
      • 3. American Hartford Gold
    4. How to Choose the Right Provider for Your Situation
    5. Taking the Next Step
    6. Frequently Asked Questions

    The best gold IRA providers that welcome accounts under $10,000 and won’t turn you away for being a smaller investor.

    A common mistake many people make is assuming that you need $25,000 or more to open a gold IRA and that anything less isn’t worth the effort. However, if you can identify companies that specifically welcome smaller accounts and offer transparent fee structures, you can get real precious metals diversification with $10,000 or less.

    You might be avoiding gold IRAs entirely because you keep seeing high minimums advertised everywhere, and these barriers can lead to postponing diversification indefinitely or feeling shut out of precious metals investing altogether.

    Instead, you can focus on the handful of reputable firms that have built their business model around serving smaller investors, which quickly leads to actual precious metals in your retirement account as well as peace of mind that you’re not missing out on this asset class.

    In this guide, you’ll explore the three best gold IRA companies with low investment minimums that have helped thousands of investors get started with modest balances.

    This material includes detailed fee breakdowns from many independent review sources and shows you how to choose the right provider for your situation. After you read through these options, ask yourself: do you have any doubt that you can open a gold IRA with $10,000 or less?

    People who haven’t explored this market recently often believe they could never use a gold IRA with their current savings level. They couldn’t be more wrong.

    You actually can separate the marketing hype from the real accessibility of these accounts.

    The transparent approach helps whether you’re rolling over a small 401(k) or making your first IRA contribution. The core principle is proven to be effective across different account sizes.

    Often, the peace of mind from the diversification in later years will multiply what you invest in setup time and modest fees today.

    Sometimes, far better.

    Top 3 Gold IRA Companies for Small Investors
    Top 3 Gold IRA Companies for Small Investors

    Top 3 Gold IRA Companies for Small Investors

    These three companies stand out for actually welcoming investors with $10,000 or less, maintaining transparent fee structures, and providing solid educational support throughout the process.

    National Gold Group Review
    National Gold Group Review

    1. National Gold Group

    Best for hands-on support and personalized guidance

    National Gold Group is the newest of these three companies, founded in 2021, but it has already earned an A+ rating with the Better Business Bureau and shows up consistently in independent reviews as a strong option for smaller investors.

    The company sets its minimum at $10,000 for both physical metals purchases and precious metals IRAs, which puts it squarely in reach for moderate investors. According to Retirement Living and other review sources, National Gold emphasizes personalized customer service and ongoing account support.

    What makes National Gold particularly appealing if you’re new to precious metals is the focus on education and guidance. Representatives walk you through each step of opening your account, selecting appropriate metals, and understanding the storage and insurance arrangements.

    Multiple reviews highlight responsive customer service and a willingness to answer questions without rushing you through the process.

    The fee structure follows industry standards with competitive annual maintenance and storage costs. The company promotes low first-year fees and sometimes offers promotional waivers for larger accounts, though you should verify current terms when you contact them.

    You can invest in gold, silver, platinum, and palladium through National Gold, working with approved custodians and depositories that meet IRS requirements. The company focuses on helping you build a mix of metals based on your specific situation as opposed to pushing any single product.

    Because it’s newer, you won’t find the same decades-long track record you get with Birch Gold Group. However, current customer feedback is consistently positive, and the company appears on many “best of” lists for 2025 and 2026.

    Start your gold IRA or rollover account today with National Gold Group by filling out their short form to receive their free guide by clicking the banner below.
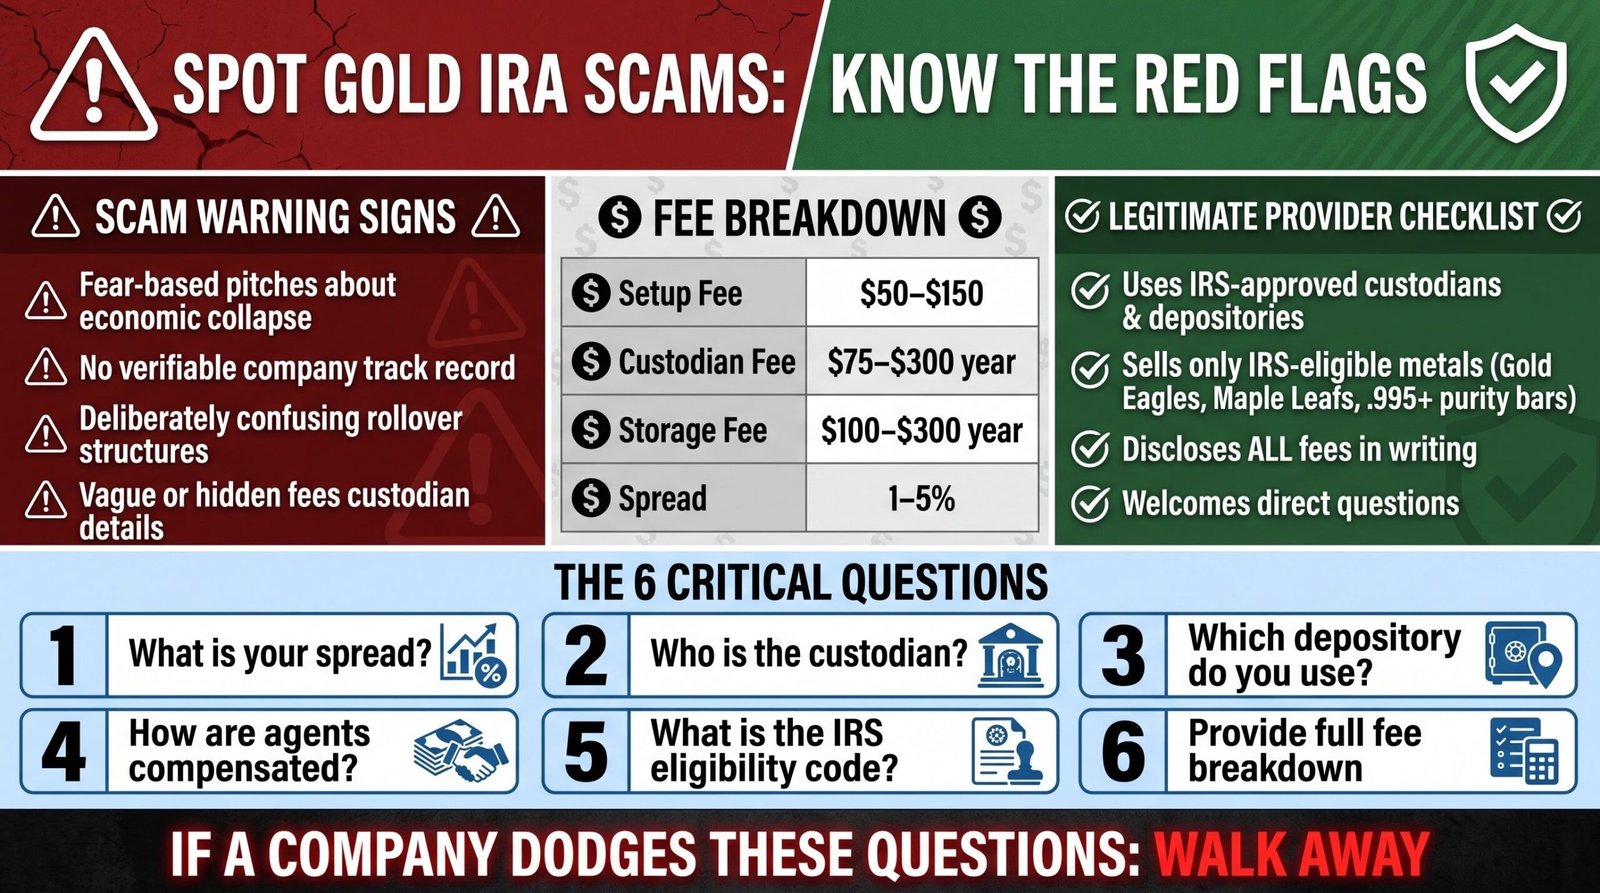
    National Gold Group Review
    Birch Gold Group
    Birch Gold Group

    2. Birch Gold Group

    Best for rollover assistance and many precious metal options

    Birch Gold Group has operated since 2003 and built a solid track record helping people roll over existing retirement accounts into precious metals IRAs. They set their minimum at exactly $10,000, which is confirmed by many independent review sites, including Retirement Living and Investing.com.

    If you have funds spread across old employer 401(k) plans or traditional IRAs, Birch provides hands-on support to navigate the rollover process. They work with several qualified custodians and use well-known depositories like Delaware Depository and Brink’s for secure storage of your metals.

    The fee structure is transparent and typical for the industry. You’ll pay a one-time $50 account setup fee and a $30 wire transfer fee when you open your account.

    After that, expect about $80 per year in maintenance fees and roughly $100 annually for storage, bringing your total ongoing cost to about $180 per year.

    One advantage Birch Gold offers is access to gold, silver, platinum, and palladium, as long as they meet IRS purity standards. That gives you more diversification options within your precious metals allocation compared with companies that only focus on gold and silver.

    The company emphasizes investor education and takes time to explain both the potential benefits and risks of precious metals investing. Multiple reviewers note that representatives don’t use high-pressure tactics and focus on helping you understand what you’re buying.

    To get started protecting your hard-earned retirement savings with Birch Gold Group, visit their official site and fill out their short form to receive a free gold IRA guide by clicking the banner below.
    american hartford gold
    American Hartford Gold

    3. American Hartford Gold

    Best overall for low ongoing costs and strong reputation

    American Hartford Gold makes it straightforward to open a precious metals IRA with around $10,000, and some sources indicate they have no formal minimum for self-directed gold IRAs. The company built its reputation on transparent pricing and keeping annual costs manageable for smaller accounts.

    American Hartford typically charges an annual IRA fee of just $75 for accounts up to $100,000, plus about $100 per year for depository storage. That puts your total ongoing cost at around $175 annually, which is competitive across the industry.

    The company often offers promotions that waive first-year fees for larger purchases, though you shouldn’t count on those applying to a $10,000 account.

    What really sets American Hartford apart is that they don’t punish you for being a smaller investor. You get the same flat-rate fee structure as someone with a six-figure account, which means the percentage cost is higher for you, but you’re not paying scaled-up fees or facing the lowest balance penalties.

    You can hold IRS-approved gold and silver products from major mints, and the company maintains a buyback program if you need to liquidate your metals later. Their customer service ratings are consistently high, with strong marks on Trustpilot and positive feedback about the educational approach they take with new investors.

    To take advantage of American Hartford Gold’s trusted reputation and service, by clicking the banner below.
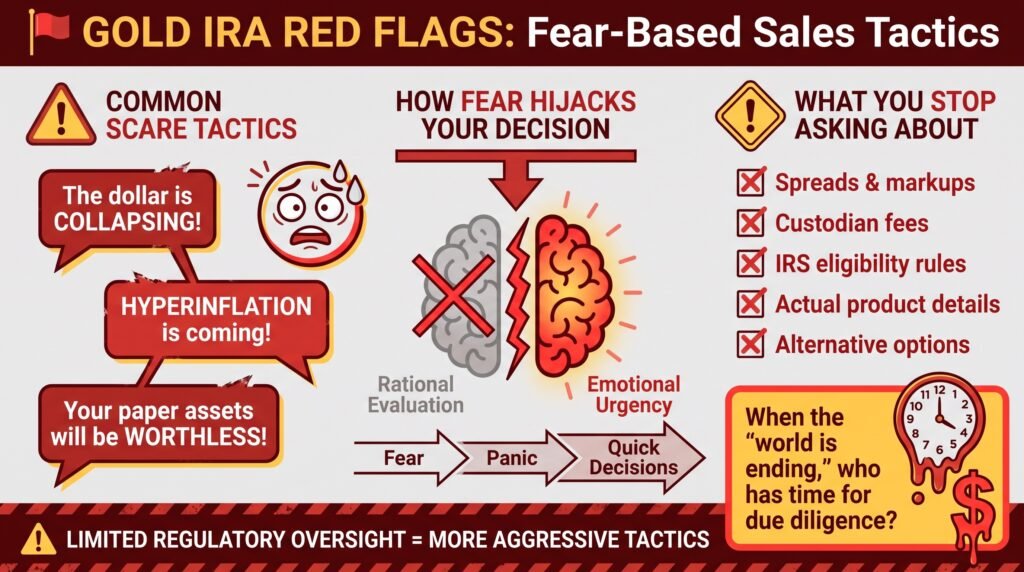
    AHG-2026-Free-Imfo-Guide-1024x572
    AHG-2026-Free-Imfo-Guide-1024×572

    How to Choose the Right Provider for Your Situation

    When you’re working with $10,000 or less, the math matters differently than it does for larger accounts. A $180 annual fee represents 1.8% of a $10,000 account but only 0.18% of a $100,000 account.

    That means you need to think about your timeline and contribution plans.

    If you plan to hold your gold IRA for many years and expect to add contributions over time, the percentage cost gradually shrinks, and the diversification benefit can outweigh the fee impact. If you’re planning to open a $10,000 account and never add to it, you need to factor in that ongoing cost when deciding whether a gold IRA makes sense for you.

    All three of these companies use similar custodial and storage arrangements. Your metals will be held in an IRS-approved depository with insurance and security.

    You won’t physically possess the metals while they’re in your IRA, but you can typically arrange delivery or liquidation when you reach retirement age.

    The main differences come down to customer service style, exact fee amounts, and how much hand-holding you want during the process.

    National Gold Group gives you a more personalized, guided experience if that matters to you.

    Birch Gold Group provides excellent rollover support and more metal choices.

    American Hartford Gold offers the best combination of low fees and a strong reputation.

    Taking the Next Step

    The practical move is to contact your top choice directly and ask specific questions about opening an account at your exact balance. Get written confirmation of all fees, including setup costs, annual maintenance, storage charges, and any potential transaction fees for buying or selling metals.

    Compare what you receive in writing with the fee ranges described here. If something doesn’t match, ask for clarification before you commit.

    Reputable companies will provide clear documentation and won’t pressure you to decide immediately.

    Most of these firms will assign you a representative who walks you through opening a self-directed IRA with their preferred custodian, initiating a rollover or transfer from your existing retirement account, selecting IRS-approved metals, and completing the purchase. The entire process typically takes a few weeks from start to finish.

    Receive a free gold investing guide from the gold IRA company that is right for you by clicking the banners below. Fill out their short contact form to get started.

    National Gold Group Free IRA Guide
    National Gold Group: Best Gold IRA for Transparency & Buyback
    Birch Gold Group Silver IRA
    Birch Gold Group: Best Gold IRA for Established Trust & Low Fees
    AHG-2026-Free-Imfo-Guide-1024x572
    American Hartford Gold: Best for Low Ongoing Costs and Strong Reputation

    Frequently Asked Questions

    Can you really open a gold IRA with less than $10,000?

    Yes, several companies, including American Hartford Gold, accept accounts at or near $10,000, and some have no stated minimum for self-directed IRAs. The challenge isn’t usually the minimum itself but rather the fee percentage on smaller balances.
     
    With flat annual fees around $175 to $180, you’re looking at roughly 1.8% of a $10,000 account going to fees each year.
     
    That’s workable if you plan to hold long-term and add to the account, but it’s a meaningful percentage to consider when deciding whether a gold IRA makes sense for your situation.

    How do gold IRA fees affect small accounts differently?

    Gold IRA companies typically charge flat annual fees for maintenance and storage as opposed to percentage-based fees. A $180 annual fee costs you the same whether your account holds $10,000 or $100,000.
     
    For smaller accounts, that represents a higher percentage cost.
    The trade-off is that you get access to the same services, security, and diversification benefits as larger investors. You can offset the percentage impact by planning to grow your account over time through extra contributions or rollovers.

    What metals can you hold in a gold IRA?

    The IRS sets strict purity requirements for metals in self-directed IRAs.
     
    For gold, you need .995 fineness or higher.
     
    Silver must be .999 pure.
     
    Platinum and palladium must meet .9995 purity.
     
    Common approved products include American Gold Eagles, Canadian Gold Maple Leafs, Austrian Gold Philharmonics, and gold bars from approved refiners.
     
    The companies listed here work with IRS-approved metals and can guide you toward products that qualify.
     
    Collectible coins, numismatic items, and certain commemorative pieces don’t qualify for IRA holding.
     

    Is a gold IRA better than buying physical gold outside an IRA?

    Each approach has different benefits. A gold IRA gives you tax advantages since your investment grows tax-deferred in a traditional IRA or tax-free in a Roth IRA.
    You can roll over existing retirement funds without triggering taxes.
     
    The downsides are annual fees, restrictions on which metals qualify, and the requirement to store metals in an approved depository as opposed to at home.
    Buying physical gold outside an IRA gives you direct possession, no annual storage fees, and more flexibility in what you buy, but you lose the tax advantages and typically buy with after-tax dollars.

    How long does it take to open a gold IRA?

    The timeline from initial contact to having metals in your account typically runs two to four weeks. You’ll spend a few days opening the self-directed IRA with the custodian, then start your rollover or transfer, which can take one to two weeks, depending on your current retirement account provider.
     
    Once funds arrive, selecting and purchasing your metals usually happens within a few days.
     
    Some steps can overlap, and urgent situations might move faster, but plan on a few weeks for the complete process.

    Can you add to your gold IRA after you open it?

    Yes, you can make extra contributions to your gold IRA, subject to annual IRA contribution limits set by the IRS. For 2025, the limit is $7,000 for people under 50 and $8,000 for those 50 and older.
     
    You can also roll over extra funds from other qualified retirement accounts at any time.
     
    Many investors start with a smaller balance and gradually build their precious metals allocation over several years. Adding to your account over time helps reduce the percentage impact of flat annual fees.

    What happens to your gold IRA if the company goes out of business?

    Your metals are held in an IRS-approved depository, not by the gold dealer or IRA company. If the company you purchased through goes out of business, your metals stay safely stored in your name at the depository.
     
    You would work with your IRA custodian to engage a different dealer for any future transactions or to arrange a transfer to another provider.
     
    The separation between the dealer, custodian, and depository provides important protection. This is why working with established companies that use well-known custodians and depositories matters for peace of mind.

    References

    1. Retirement Living, “American Hartford Gold Review (2026)”
    2. Money.com, “American Hartford Gold Group Gold IRA Review”
    3. Retirement Living, “Birch Gold Group Review (2026)”
    4. Investing.com, “Birch Gold Group Review 2026”
    5. Retirement Living, “National Gold Group Review (2026)”
    6. ConsumerAffairs, “The Best Gold IRA Companies (2026 Guide)”
    7. Bankrate, “The Best Gold IRA Companies: Where To Set Up A Gold IRA”
  • Beginners Guide to Investing in and Diversifying with Gold(2026) (5–20% Rule Explained)

    Beginners Guide to Investing in and Diversifying with Gold(2026) (5–20% Rule Explained)

    Gold Investment Allocation for Retirement Portfolio- Best Strategies & Tips
    Gold Investment Allocation for Retirement Portfolio- Best Strategies & Tips

    Quick Summary

    • Most financial advisors recommend allocating between 5% and 20% of your retirement portfolio to gold, depending on your risk profile and timeline.
    • Gold behaves differently from stocks and bonds, making it one of the most effective diversification tools available to retirees.
    • A Gold IRA offers tax-deferred growth using IRS-approved bullion, but the rules are stricter than most people realize.
    • Your ideal gold allocation should shift as you age, with retirees 70 and older often benefiting from a higher weighting toward capital preservation.
    • There are four distinct ways to hold gold in a retirement portfolio, each with different cost structures, tax treatments, and risk levels.

    Gold isn’t just a shiny metal; it’s one of the most time-tested tools for protecting retirement wealth when everything else starts to wobble.

    For retirees and pre-retirees navigating market uncertainty, rising inflation, and decades of living expenses ahead, knowing how to use gold strategically can mean the difference between a comfortable retirement and one spent hoping the market recovers in time.

    Augusta Precious Metals specializes in helping everyday investors understand exactly how precious metals fit into a long-term financial plan, and the gold IRA guide pulls from that same practical, no-nonsense approach to owning physical gold in a tax-advantaged way.

    Table of Contents

    1. Quick Summary
    2. Gold Belongs in Your Retirement Portfolio: Here’s Exactly How Much
    3. How Your Risk Profile and Age Determine Your Gold Allocation
    4. Gold as a Hedge Against Inflation and Currency Risk
    5. The Right Gold Allocation Comes Down to Your Specific Situation
    6. Frequently Asked Questions

    Gold Belongs in Your Retirement Portfolio: Here’s Exactly How Much

    The debate isn’t really whether gold belongs in a retirement portfolio. It’s how much. Get that number wrong in either direction: too little, and you’re exposed; too much, and you’ve sacrificed growth, and your retirement security takes a real hit.

    The 5-20% Rule Most Financial Advisors Recommend

    Most financial advisors recommend keeping between 5% and 20% of your retirement portfolio in gold, with the sweet spot for most people landing around 10% to 15%. Some recent analysis has pointed to an optimal allocation closer to 18% for retirees without a pension, specifically because gold offsets the absence of guaranteed income. The range is wide because personal factors, age, income needs, existing assets, and risk tolerance all pull the number in different directions.

    For a retiree with a solid pension and Social Security covering core expenses, 5% to 10% in gold may be plenty. For someone relying entirely on a self-managed portfolio to fund 25 or 30 years of retirement, pushing toward 15% to 20% is a reasonable defensive move. The key is that no single number fits everyone, and adjusting over time is just as important as the initial allocation.

    Why Gold Behaves Differently Than Stocks and Bonds

    Gold has a low or negative correlation with stocks and bonds, which is the technical way of saying it tends to move independently — and often in the opposite direction during market stress. When equity markets dropped sharply during the 2008 financial crisis, gold prices climbed. When inflation surged in the 1970s, and again in the early 2020s, gold held and grew its purchasing power while fixed-income investments lost ground in real terms.

    This independence is what makes gold genuinely useful in a portfolio rather than just a feel-good hedge. Adding an asset that doesn’t move in lockstep with your other holdings reduces overall portfolio volatility without necessarily reducing long-term returns — a powerful combination for anyone who can’t afford to ride out a multi-year market correction.

    How Gold Protects Purchasing Power Over Decades

    Inflation is the slow leak in any retirement plan. A 3% annual inflation rate cuts your purchasing power nearly in half over 25 years. Retirees living on fixed income streams feel this erosion directly — the same dollar buys fewer groceries, less healthcare, less of everything over time.

    Gold has historically maintained its purchasing power over long periods, even when paper currencies have not. This isn’t about gold making you rich — it’s about gold keeping you whole. For a retiree facing a 20- to 30-year time horizon, even a modest allocation to gold helps offset what inflation quietly takes away year after year.

    Here’s a simple look at how a balanced retirement portfolio might be structured with gold included:

    How Your Risk Profile and Age Determines Your Gold Allocation
    How Your Risk Profile and Age Determine Your Gold Allocation

    How Your Risk Profile and Age Determine Your Gold Allocation

    Your risk tolerance isn’t just about how you feel about market swings; it’s about how much volatility your retirement income can actually absorb. Someone with a pension, Social Security, and rental income can afford to be aggressive with their investment portfolio. Someone living entirely off their savings cannot. That difference shapes everything, including how much gold makes sense.

    Think of gold allocation as a dial, not a switch. You’re not choosing between having gold or not; you’re choosing how loud to turn it up based on your specific financial picture.

    Conservative Investors: 15-20% Allocation for Wealth Preservation

    Conservative investors, typically those who prioritize not losing money over growing it, tend to benefit most from a higher gold allocation. A 15% to 20% weighting in gold provides meaningful protection against both market downturns and inflation without requiring the investor to time the market or take on equity risk they’re not comfortable with.

    A practical example: a 70-year-old retiree without a pension, living on portfolio withdrawals and Social Security, might hold 18% in gold split between physical bullion and a gold ETF. The rest of the portfolio sits in dividend-paying stocks and short-duration bonds. This structure prioritizes capital preservation while still generating income, exactly what a conservative retirement portfolio needs.

    • Primary goal: Protect existing wealth from erosion
    • Gold vehicles: Physical bullion, Gold IRA, gold ETFs
    • Rebalancing frequency: Annually or when gold exceeds target by 3-5%
    • Best suited for: Retirees 65+, no pension, high sensitivity to loss

    Moderate Investors: 10-15% Allocation for Balanced Growth

    Moderate investors want growth but aren’t willing to absorb large drawdowns. A 10% to 15% gold allocation gives this group meaningful downside protection while keeping the bulk of the portfolio in assets with stronger long-term return potential. This is the most common allocation range among retirees with a 15- to 20-year planning horizon.

    For a 62-year-old with a mix of 401(k) assets, some bond exposure, and a moderate risk appetite, putting 12% into gold, split between a Gold IRA and gold ETFs, hits the right balance. It adds stability without sacrificing the growth potential needed to fund a long retirement.

    Aggressive Investors: 5-10% Allocation as a Minimal Hedge

    Aggressive investors who are comfortable with equity risk and have a longer time horizon typically use gold as a minimal hedge rather than a core holding. A 5% to 10% allocation is enough to provide some inflation protection and reduce portfolio correlation without meaningfully dragging down returns in a bull market.

    This approach works well for investors in their early 50s who are still accumulating wealth and have time to recover from market downturns. The gold position essentially acts as an insurance policy — you hope you never need it, but you’re glad it’s there when you do.

    Best suited for: Pre-retirees in their 50s, high risk tolerance, diversified income sources

    Primary goal: Growth with a minimal safety net

    Gold vehicles: Gold ETFs, gold mining stocks

    Rebalancing frequency: Annually

    How Age and Retirement Timeline Affect Gold Allocation

    Early 50s: Still accumulating: use gold as a 5-10% hedge while growth assets do the heavy lifting

    Late 50s: Begin building the foundation: shift toward 10-12% as retirement approaches

    Ages 60-65: Transition phase: prioritize capital preservation, consider 12-15% allocation

    Ages 65-70: Early retirement: income generation becomes critical, gold anchors the defensive side

    Ages 70+: Late retirement: stability over growth, 15-20% may be appropriate depending on income sources.

    The Best Ways to Hold Gold in a Retirement Portfolio

    Not all gold is created equal when it comes to retirement planning. The way you hold gold determines your tax treatment, liquidity, storage responsibilities, and overall cost. Each method has genuine advantages and real trade-offs that matter depending on your situation.

    There are four main ways retirees hold gold, and many seasoned investors use a combination of two or more to balance the benefits of each.

    Physical Gold: Coins, Bars, and Storage Considerations

    Owning physical gold, whether American Gold Eagles, Canadian Maple Leafs, or gold bars, gives you direct, tangible ownership of the asset. There’s no counterparty risk, no fund manager, and no platform that can go bankrupt and take your holdings with it. For retirees who’ve lived through enough market crises to distrust financial institutions, physical gold has a particular appeal.

    The trade-offs are real, though. Physical gold requires secure storage, either a home safe or a third-party vault, which adds ongoing costs. Selling it also takes more effort than clicking a button in a brokerage account. Premiums over spot price are common when buying coins and smaller bars, and you’ll want to work with a reputable dealer to avoid overpaying.

    For IRS purposes, physical gold held outside a retirement account is classified as a collectible and taxed at a maximum capital gains rate of 28%, higher than the standard long-term capital gains rate for stocks. That tax difference is worth factoring into your allocation decisions.

    Gold ETFs and Mutual Funds: Low-Cost Paper Exposure

    Gold ETFs like the SPDR Gold Shares (GLD) and iShares Gold Trust (IAU) track the spot price of gold and trade on major stock exchanges just like shares of stock. They’re the most accessible and lowest-cost way to add gold exposure to a retirement portfolio, with expense ratios typically below 0.40%. You can hold them inside a traditional IRA, Roth IRA, or standard brokerage account without any special custodian requirements.

    Gold Mining Stocks: Higher Risk, Higher Reward Potential

    Gold mining stocks, companies like Newmont Corporation (NEM) and Barrick Gold (GOLD), give you leveraged exposure to gold prices. When gold rises 10%, a well-run mining company might see its stock climb 20% or more, because the profit margin expands faster than the underlying commodity price. That leverage cuts both ways, though; mining stocks can fall hard and fast when gold prices drop or when operational problems hit.

    For retirement portfolios, gold mining stocks are best used as a small satellite position rather than a core gold holding. They introduce company-specific risk, management risk, and geopolitical risk that physical gold and ETFs simply don’t carry. If you’re going to use them, consider a gold miners ETF like the VanEck Gold Miners ETF (GDX) to spread that risk across multiple companies rather than betting on a single name.

    Gold IRAs: Tax-Deferred Growth With IRS-Approved Bullion

    A Gold IRA is a self-directed Individual Retirement Account that holds physical gold — but with strict IRS rules about what qualifies. The gold must meet a minimum purity of .995 fineness, must be stored in an IRS-approved depository (not your home), and must be held through a qualified custodian. Approved coins include the American Gold Eagle, American Gold Buffalo, and Canadian Gold Maple Leaf, among others.

    The main benefit is tax treatment. Like a traditional IRA, contributions may be tax-deductible, and growth is tax-deferred until withdrawal. A Roth Gold IRA allows for tax-free growth if you meet the income requirements. Either way, a Gold IRA lets your gold position grow without annual tax drag, a significant advantage over a 20- to 30-year retirement horizon.

    Your chosen Gold IRA company is not the same as your custodian; it is the dealer that guides you through the process, helps you select IRS-approved metals, and connects you with a custodian and depository. Choosing the right one upfront saves you from costly mistakes later.

    Look for companies with long operating histories, transparent fee structures, and strong third-party reviews. A company that pressures you into making a quick decision or upsells you into rare or collectible coins is a red flag; collectibles are not IRS-approved for Gold IRAs and can disqualify your account.

    Augusta Precious Metals is one example of an established precious metals provider that helps investors navigate the Gold IRA process, offering IRS-approved coins and bars along with educational resources for beginners who are just getting started with precious metals retirement planning.

    Click the banner below to visit Augusta’s official site and receive a free gold IRA guide. Fill out their short form to get started.

    Gold as a Hedge Against Inflation and Currency Risk

    Inflation and currency debasement are the two slow-moving threats that most retirement plans are least prepared for, and gold is one of the few assets specifically designed to counter both.

    Understanding exactly how and when gold delivers on that inflation-hedging promise helps you hold the position with conviction rather than second-guessing it every time a financial headline makes it look overpriced.

    What History Shows About Gold During High Inflation Periods

    During the high-inflation decade of the 1970s, gold prices surged from approximately $35 per ounce to over $800 per ounce by 1980, a gain that dramatically outpaced the inflation rate of that era. More recently, when U.S. inflation hit multi-decade highs in 2021 and 2022, gold maintained its purchasing power even as bonds lost significant real value.

    The pattern isn’t perfect — gold doesn’t always move immediately with inflation data, but over multi-year periods of sustained inflation, its track record as a purchasing power preserver is well-established.

    How Gold Performs When the U.S. Dollar Weakens

    Gold is priced in U.S. dollars, which means when the dollar weakens against other currencies, gold prices in dollar terms typically rise. This inverse relationship isn’t a coincidence; it’s structural. As the dollar loses purchasing power relative to other currencies or relative to goods and services, the dollar price of gold adjusts upward to reflect the same underlying value. For retirees whose savings are denominated in dollars, gold provides a built-in counterweight to currency depreciation.

    Key Relationship — U.S. Dollar vs. Gold:

    • Dollar strengthens → Gold prices typically face short-term pressure
    • Dollar weakens → Gold prices typically rise in dollar terms
    • Federal Reserve expands money supply → Long-term upward pressure on gold
    • Geopolitical uncertainty rises → Safe-haven demand pushes gold higher
    • Real interest rates turn negative → Gold becomes more attractive vs. bonds

    The Right Gold Allocation Comes Down to Your Specific Situation

    There is no universally correct percentage of gold for a retirement portfolio, but there is a correct process for finding your number. Start with your income sources. If Social Security and a pension cover your basic living expenses, your investment portfolio can afford to take more risk and needs less gold.

    If your portfolio is your only income source, the defensive allocation, including gold, needs to be more substantial. Layer in your age, your withdrawal timeline, your inflation sensitivity, and your tax situation, and the right allocation starts to take shape. For most retirees, that number lands somewhere between 10% and 20%, with the specific point within that range determined by the factors above.

    What matters most is that your gold allocation is intentional, sized correctly for your situation, diversified across more than one form of gold ownership, held primarily inside tax-advantaged accounts, and rebalanced annually. Do those five things consistently, and gold will do exactly what it’s designed to do in a retirement portfolio: protect what you’ve built while everything else handles growth and income.

    Learn how to own physical gold in a tax-advantaged way without the need or liability of storing the precious metal in your residence. Click the banner below to access Augusta Precious Metals’ free gold IRA guide on their official site. Fill out their short contact form to get started.

    Receive a free gold IRA company integrity checklist from Augusta Precious Metals by clicking the banner below and filling out their short contact form.

    Investment Minimums – Personal Considerations

    Certain IRA companies have higher investment minimums than others. If you are a serious investor with a minimum of $50,000, you can take advantage of Augusta Precious Metals’ higher competitive prices, lifelong customer service, and educational resources.

    If you require a lower barrier to entry, both National Gold Group and Birch Gold Group provide a $10,000 investment minimum.

    National Gold Group provides exceptional price transparency and a reliable buyback commitment. Birch Gold Group is one of the most established and trusted gold IRA companies, spanning over 20 years, and provides some of the lowest fees in the industry.

    Decide which gold IRA company works for you; access their free gold IRA guide by clicking on the banner below.

    Birch Gold Group: Best Gold IRA for Established Trust & Low Fees

    National Gold Group Review

    National Gold Group: Best Gold IRA for Transparency & Buyback

    Frequently Asked Questions

    Retirees and pre-retirees ask a consistent set of questions when they start thinking seriously about adding gold to their retirement strategy. The answers below reflect the practical reality of how gold actually behaves in a retirement context, not theory, not marketing, but the specific mechanics that matter when real money and real retirement security are on the line.

    What percentage of my retirement portfolio should be in gold?

    Most financial advisors recommend between 5% and 20% of a retirement portfolio in gold, with 10% to 15% being the most common range for moderate-risk retirees.

    Conservative retirees without guaranteed income sources like a pension often benefit from the higher end of that range, 15% to 20%, while aggressive investors with diversified income streams may be comfortable at 5% to 10%. The right number depends on your age, income needs, risk tolerance, and whether you’re still accumulating wealth or actively drawing it down.

    Does gold actually protect against inflation in retirement?

    Yes, over multi-year and multi-decade periods, gold has consistently maintained its purchasing power against inflation. During the 1970s-inflationary decade, gold dramatically outpaced the inflation rate. During the post-COVID inflation surge of 2021 and 2022, gold held value even as bond prices fell in real terms.

    The protection isn’t perfect year-to-year — gold can lag inflation in the short term — but as a long-term store of purchasing power, its track record is stronger than most fixed-income alternatives. For retirees facing 20 to 30 years of inflation exposure, even a partial hedge through a 10% to 15% gold allocation meaningfully reduces the long-term erosion of buying power.

    Is a Gold IRA better than buying physical gold directly?

    Gold IRA vs. Physical Gold: Key Comparison
    Tax Treatment: A Gold IRA offers tax-deferred (traditional) or tax-free (Roth) growth; physical gold outside an IRA is taxed as a collectible at up to 28% on gains

    Storage: A Gold IRA requires an IRS-approved depository; physical gold allows a home safe or private vault

    Accessibility: Gold IRA withdrawals are subject to IRA rules and potential penalties before age 59½; physical gold can be accessed at any time

    Setup complexity: Gold IRA requires a custodian, depository, and IRS-compliant bullion; physical gold can be purchased directly from a dealer

    Annual costs: Gold IRA carries custodian and storage fees ($200–$500/year, typically); physical gold storage varies based on method

    Best for: A Gold IRA suits long-term tax-advantaged growth; physical gold suits investors who want direct access and no account structure.

    Neither option is universally better; they serve different purposes. A Gold IRA is the superior choice for long-term retirement savings where tax efficiency matters most. The tax-deferred growth over a 20- to 30-year retirement horizon can significantly compound the value of your gold position compared to holding it in a taxable account, where gains are hit at 28% each time you rebalance.

    Physical gold held outside a retirement account makes sense as a complementary holding for retirees who want a portion of their gold to be immediately accessible without navigating IRA withdrawal rules. Think of it as the liquid emergency layer of your gold allocation — the portion you can convert to cash quickly and without account restrictions if an unexpected major expense arises.

    For most retirees, the optimal approach is a combination: the bulk of the gold allocation held inside a Gold IRA for tax efficiency, with a smaller physical gold position held outside the account for direct access and liquidity. This split captures the tax advantages of the IRA structure while preserving the direct-ownership benefits that physical gold uniquely provides.

    If you are ready to explore how physical precious metals can strengthen your retirement strategy, Augusta Precious Metals offers a full range of IRS-approved gold and silver products along with expert guidance to help you build a Gold IRA that works for your long-term goals.

    Free Gold IRA Guide
    Free Gold IRA Guide

    Sources:

    The Role of Gold in a Balanced Retirement Portfolio: A Strategic Guide

    https://metalsedge.com

    How Much Gold Should I Hold in My Retirement Portfolio?

    Could Investing in Gold Add a New Dimension to Your Portfolio?

    https://www.morganstanley.com/articles/investing-in-gold

  • Can I Store My Gold IRA at Home? IRS Rules Explained (2026)

    Can I Store My Gold IRA at Home? IRS Rules Explained (2026)

    Home IRA Gold Storage Rules and the Legal Truth
    Home IRA Gold Storage Rules and the Legal Truth

    Quick Summary

    Home storage of IRA gold is illegal; the IRS strictly prohibits keeping precious metals from a self-directed IRA in your home, a personal safe, or a safe-deposit box.

    Violations can trigger full IRA disqualification, meaning all assets in the account become immediately taxable plus subject to early withdrawal penalties.

    Personally owned gold (outside of an IRA) can legally be stored at home; the restriction only applies to IRA-owned precious metals.

    A real court case involving a Rhode Island couple illustrates just how costly ignoring these rules can be, and the outcome may surprise you.

    IRS-approved depositories and licensed custodians are the only compliant way to store gold held inside a retirement account.

    Table of Contents

    1. Quick Summary
    2. The IRS Says No to Home Gold IRA Storage: Here’s What That Means for You
    3. IRS Rules on Physical Gold IRA Storage
    4. The Real Legal Consequences of Storing IRA Gold at Home
    5. IRS-Approved Alternatives to Home Gold Storage
    6. How to Set Up a Compliant Gold IRA
    7. Home Storage Gold IRAs Are Illegal: Protect Your Retirement Now
    8. Frequently Asked Questions

    The IRS Says No to Home Gold IRA Storage: Here’s What That Means for You

    Storing your gold IRA at home seems like a smart move for control and security, until the IRS gets involved.

    Gold IRAs have grown in popularity as investors look for ways to protect wealth against inflation and economic uncertainty. The appeal of holding physical gold is real. But many investors make a critical mistake: they assume that because they own the gold, they can store it wherever they want. That assumption is wrong, and it can cost you everything you’ve saved.

    The IRS has very specific rules about where IRA-owned precious metals must be kept, and your home is not on the approved list. Augusta Precious Metals is a trusted authority in precious metals and regularly helps investors navigate these exact compliance challenges. Understanding the distinction between what you legally can and cannot do with IRA gold is the single most important thing you can do to protect your retirement.

    IRS Rules on Physical Gold IRA Storage
    IRS Rules on Physical Gold IRA Storage

    IRS Rules on Physical Gold IRA Storage

    The IRS treats physical gold inside a self-directed IRA as a retirement asset, not personal property. That classification comes with strict custody and storage requirements that every gold IRA holder must follow.

    Why the IRS Prohibits Home Storage of IRA Gold

    The core reason home storage is prohibited comes down to the legal structure of an IRA itself. When gold is held inside an IRA, it is owned by the account, not by you personally. Because of that distinction, you cannot take physical possession of it without triggering what the IRS considers a distribution.

    Taking a distribution means the IRS views that gold as money you’ve withdrawn from your retirement account. If you’re under 59½, that comes with a 10% early withdrawal penalty on top of ordinary income taxes owed on the full value. Even if you’re over 59½, taking possession by storing it at home still violates the custodial rules governing IRAs and can disqualify the entire account.

    What Qualifies as an Approved Storage Facility

    The IRS requires that all precious metals held in a self-directed IRA be stored at an approved financial institution. According to IRS regulations, that institution must qualify as a “bank” under the Internal Revenue Code, and the definition is narrower than most people expect.

    To meet the legal threshold, the storage facility must be one of the following approved depositories.

    • A federally licensed bank
    • A federally insured credit union
    • A savings and loan association
    • A licensed trust company regulated by a state or federal authority
    • An IRS-approved non-bank depository (such as a specialized precious metal vault)

    A home safe, a personal safe-deposit box, or any privately controlled storage space does not qualify, even if it is physically secure. The law is not about the quality of storage; it’s about institutional oversight and regulatory compliance.

    Licensed Banks, Credit Unions, and Trust Companies as Valid Custodians

    Valid custodians are institutions that carry regulatory oversight, meaning they are accountable to state or federal authorities for how they manage client assets. This oversight is exactly what the IRS wants in place when retirement assets are involved. A licensed trust company, for example, must maintain specific capitalization requirements, undergo regular audits, and operate under fiduciary standards, protections that simply do not exist when gold sits in a home safe.

    The Real Legal Consequences of Storing IRA Gold at Home

    The consequences of home gold IRA storage are not theoretical; they are financial, legal, and in some cases, criminal.

    The Rhode Island Couple Court Case: A Cautionary Tale

    One of the most cited real-world examples of home IRA gold storage gone wrong involves a couple from Rhode Island who held physical gold coins purchased through their self-directed IRA in home storage. They believed they had found a legal workaround, specifically, a misinterpretation of a provision in federal law that they thought permitted personal custody of IRA-owned metals. They were wrong.

    The IRS ruled that the home storage of those coins constituted a distribution. The entire value of the metals was treated as taxable income for the year they took possession, and the couple faced both the tax liability on the full amount and substantial penalties. The court sided with the IRS. This case has since become a widely referenced cautionary example of what happens when investors either misread or ignore IRS storage requirements for gold IRAs.

    Tax Penalties and IRA Disqualification Risks

    Beyond individual penalties, home storage can trigger full IRA disqualification. When an IRA is disqualified, every asset inside it is treated as distributed in the tax year of disqualification, not just the improperly stored gold. That means the entire account balance becomes taxable at once.

    Here is what investors can face when IRA gold is stored at home:

    • Immediate income tax on the full fair market value of the IRA assets
    • 10% early withdrawal penalty if the account holder is under age 59½
    • Loss of all tax-deferred or tax-free growth accumulated in the account
    • Potential IRS audit and investigation into other tax filings
    • In extreme cases, criminal charges related to tax evasion if intent to conceal is established

    IRS-Approved Alternatives to Home Gold Storage

    For IRA-owned gold, the only compliant path forward is using an IRS-approved depository through a qualified custodian, and fortunately, there are strong options available that provide both security and peace of mind.

    How Approved Depositories Protect Your Investment

    IRS-approved depositories are purpose-built facilities designed specifically to store precious metals under strict regulatory oversight. These are not ordinary bank vaults. They are specialized institutions that maintain Lloyd’s of London or comparable insurance coverage, 24/7 armed security, advanced surveillance systems, and regular third-party audits to verify holdings. For more information on storing precious metals, you can visit this guide on storing precious metals owned by your self-directed IRA.

    Two of the most widely used IRS-approved precious metals depositories in the United States are the Delaware Depository and Brink’s Global Services. The Delaware Depository, located in Wilmington, Delaware, is one of the most respected in the industry; it is licensed, bonded, and insured, and it holds COMEX and NYMEX approval. These are not abstract credentials; they represent layers of verified accountability that protect your retirement assets.

    Most approved depositories offer two types of storage: segregated storage and commingled storage. Segregated storage means your specific gold bars or coins are stored separately and identified as yours alone. Commingled (or non-segregated) storage means your metals are stored alongside other clients’ metals of the same type and purity. Segregated storage typically costs more but provides a direct chain of ownership to your specific metals.

    Both Birch Gold Group and Augusta Precious Metals are gold IRA companies that partner with Delaware Depository as well as Brink’s Global Services.

    Decentralized Private Vault Storage as an Alternative

    Some investors look beyond traditional depositories toward decentralized private vault networks, a growing segment of the precious metals storage industry. These facilities operate independently of the traditional banking system while still meeting IRS approval requirements for IRA storage.

    Private vault networks like Citadel Global Depository Services offer storage across multiple geographic locations, which appeals to investors concerned about systemic risk or single-point-of-failure scenarios. Geographic diversification of your stored gold means that a localized disaster, political event, or institutional failure at one location does not put your entire holding at risk.

    The costs for private vault storage vary, but investors should expect annual fees ranging from roughly 0.5% to 1% of the asset value for segregated storage, depending on the facility and total value stored. Commingled storage runs lower, often between 0.1% and 0.5% annually. These fees are typically billed through your IRA custodian.

    Storage Type Comparison
    Storage Type Comparison

    How a Custodian Keeps Your Gold IRA Compliant

    A qualified IRA custodian is not just a paperwork processor; they are the compliance backbone of your entire gold IRA. They are responsible for ensuring that every metal purchased meets IRS purity standards, that all transactions are properly reported, and that storage arrangements remain within approved facilities at all times. Without a custodian, a self-directed IRA cannot legally function.

    Your custodian coordinates directly with the approved depository on your behalf, handling the logistics of metal transfers, storage fee payments, and annual account reporting to the IRS. When you want to take a qualified distribution from your gold IRA later in life, your custodian manages that process too, either liquidating the metals and sending cash, or in some cases arranging for physical delivery of the metals to you once the distribution is properly processed

    How to Set Up a Compliant Gold IRA

    Setting up a gold IRA the right way from the start eliminates the compliance risks that trap so many investors. The process is more straightforward than most people expect, but the details matter.

    The first step is selecting a reputable self-directed IRA custodian or gold IRA company that works with a approved custodian that specializes in alternative assets, specifically precious metals.

    Not all IRA custodians handle physical gold; traditional brokerage custodians like Fidelity or Vanguard typically do not. You need a custodian that has established relationships with IRS-approved depositories and experience managing precious metals accounts. For more insights, check out this article on storing your gold IRA.

    Choosing a Reputable Gold IRA Company

    Your Gold IRA company is not the same as your custodian; it is the dealer that guides you through the process, helps you select IRS-approved metals, and connects you with a custodian and depository. Choosing the right one upfront saves you from costly mistakes later.

    Look for companies with long operating histories, transparent fee structures, and strong third-party reviews. A company that pressures you into making a quick decision or upsells you into rare or collectible coins is a red flag; collectibles are not IRS-approved for Gold IRAs and can disqualify your account.

    Augusta Precious Metals is one example of an established precious metals provider that helps investors navigate the Gold IRA process, offering IRS-approved coins and bars along with educational resources for beginners who are just getting started with precious metals retirement planning.

    Visit Augusta’s official site and receive a free gold IRA guide by clicking the banner below and filling out their short form.

    Once your chosen gold IRA company is in place and your account is funded, either through a new contribution, a rollover from an existing IRA, or a 401(k) rollover, you work with an approved precious metals dealer to select qualifying metals. Your custodian then coordinates the purchase and directs the metals to your chosen IRS-approved depository. At no point should the metals pass through your hands.

    Here is a step-by-step overview of the compliant gold IRA setup process:

    1. Choose a self-directed IRA company experienced in precious metals accounts and working with trusted custodians
    2. Open your self-directed IRA and complete required identity verification and account documentation
    3. Fund the account via a new contribution, IRA rollover, or 401(k) rollover
    4. Select an IRS-approved precious metals dealer to source qualifying metals
    5. Choose your IRS-approved depository and storage type (segregated or commingled)
    6. Direct your custodian to complete the purchase; metals ship directly to the depository
    7. Receive account confirmation and depository storage documentation for your records

    Metals That Legally Qualify for a Gold IRA

    Not every gold product qualifies for inclusion in an IRA. The IRS sets minimum purity standards that metals must meet, and only specific coins and bars make the cut. Gold must meet a minimum fineness of .995 (99.5% pure) to qualify, with one notable exception being the American Gold Eagle coin, which at .9167 fineness, is explicitly approved by the IRS despite falling below that threshold.

    Home Storage Gold IRAs Are Illegal: Protect Your Retirement Now

    The bottom line is simple: storing IRA-owned gold at home is illegal under IRS rules, full stop. No creative workaround, no home LLC structure, and no misreading of federal law changes that fact, as the Rhode Island couple learned in court. The only way to hold physical gold in a retirement account and keep all of your tax advantages intact is to work with a qualified custodian and store your metals at an IRS-approved depository. Your retirement is too important to gamble on a storage shortcut that the IRS has already litigated and won.

    Visit Augusta’s official site and receive a free gold IRA guide by clicking the banner below.
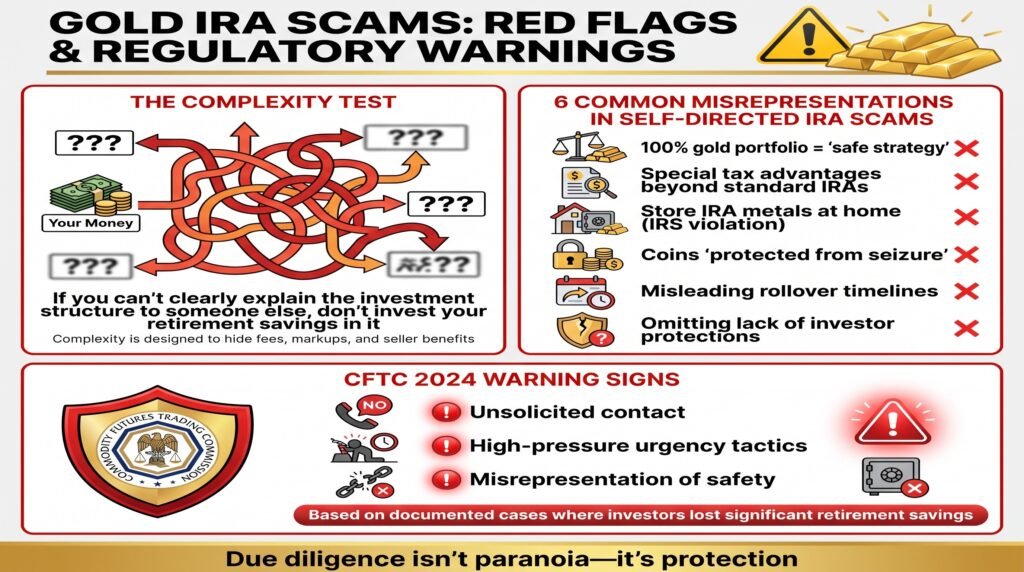
    Investment Minimums – Personal Considerations

    Certain IRA companies have higher investment minimums than others. If you are a serious investor with a minimum of $50,000, you can take advantage of Augusta Precious Metals’ higher competitive prices, lifelong customer service, and educational resources.

    If you require a lower barrier to entry, both National Gold Group and Birch Gold Group provide a $10,000 investment minimum.

    National Gold Group provides exceptional price transparency and reliable buyback commitment. Birch Gold Group is one of the most established and trusted gold IRA companies, spanning over 20 years, and provides some of the lowest fees in the industry.

    Decide which gold IRA company works for you and access their free gold IRA guide by clicking the banners below.

    Birch Gold Group: Best Gold IRA for Established Trust & Low Fees

    National Gold Group Review

    National Gold Group: Best Gold IRA for Transparency & Buyback

    Frequently Asked Questions

    Here are answers to the most common questions investors ask about home IRA gold storage rules and legal compliance.

    Can I store my gold IRA at home?

    Answer: No. The IRS prohibits home storage of IRA-owned gold. Taking physical possession of the metals, even in a personal safe, counts as a taxable distribution and can trigger income tax if you are under age 59½.

    There is a 10% early withdrawal penalty imposed and disqualification of the entire IRA. IRA gold must be held at an IRS-approved depository through your custodian.

    What is an IRS-approved depository for gold IRAs?

    An IRS-approved depository is a specialized, regulated storage facility that meets the IRS’s definition of a qualifying institution for the custody of retirement account assets. These facilities maintain institutional-grade security, including 24/7 armed monitoring, advanced surveillance, full insurance coverage, and regular independent audits of their holdings.

    Well-known IRS-approved depositories used by gold IRA investors include the Delaware Depository in Wilmington, Delaware, which holds COMEX and NYMEX approval, and Brink’s Global Services, one of the most recognized names in high-value asset transportation and storage.
    Your gold IRA company will typically have established relationships with one or more of these facilities and will coordinate storage on your behalf.

    Can I store personally owned gold at home?

    Yes, if the gold was purchased with personal funds and is not part of any IRA or retirement account, you are the direct legal owner and can store it anywhere you choose.

    A home safe, a bank safe-deposit box, or a private vault are all legal options for personally owned precious metals. The IRS restrictions on storage only apply to gold that is owned by a retirement account. The critical distinction is always legal ownership: IRA-owned gold belongs to the account, while personally purchased gold belongs directly to you.

    What types of gold qualify for an IRA?

    The IRS requires gold held in a self-directed IRA to meet a minimum fineness of .995 (99.5% purity). Qualifying gold products include the American Gold Buffalo coin (24 karat, .9999 fine), Canadian Gold Maple Leaf coins (.9999 fine), Austrian Gold Philharmonic coins (.9999 fine), and most IRS-approved gold bars and rounds produced by NYMEX- or COMEX-approved refiners.

    The one notable exception to the .995 fineness rule is the American Gold Eagle coin. At .9167 fineness, it technically falls below the standard purity threshold,  but the IRS explicitly approves it for IRA inclusion by statute, making it one of the most popular IRA-eligible gold coins available.

    Collectible coins, rare numismatic coins, and gold jewelry do not qualify for IRA inclusion regardless of their gold content. When in doubt, your custodian and precious metals dealer can confirm whether a specific product meets IRS eligibility requirements before any purchase is made. Working with established dealers who specialize in IRA-eligible metals removes the guesswork entirely and keeps your account on solid legal ground.

    For more information on why you shouldn’t store IRA precious metals at home, you can consult resources like Augusta Precious Metals by accessing their free gold IRA guide.

    Read our full list of reviews of the best gold IRA companies that we have carefully researched and vetted here.

    Find out whether gold IRAs are a good choice for your retirement needs. Access our Gold IRA calculator. Bookmark this page and perform real-time calculations as you read our reviews.

    Click the banner below to access these calculators and start protecting your wealth today.

    GOLD IRA CALCULATOR
    GOLD IRA CALCULATOR

    If you are ready to explore how physical precious metals can strengthen your retirement strategy, Augusta Precious Metals offers a full range of IRS-approved gold and silver products along with expert guidance to help you build a Gold IRA that works for your long-term goals. Click the banner below to get started.

    Sources:
    Gold IRA Rules and Regulations: LendEDU

    Gold IRA storage rules: IRS requirements for storing precious metals: Yahoo!Finance

    Investments in collectibles in individually directed qualified plan accounts: IRS.gov

    Retirement plans FAQs regarding IRAs: IRS.gov

    US Money Reserve

  • Gold IRA Rollover Rules: Changes and Mistakes That Could Cost You Thousands in 2026

    Gold IRA Rollover Rules: Changes and Mistakes That Could Cost You Thousands in 2026

    2026 Gold IRA Rollover Rules Changes & Key Insights
    2026 Gold IRA Rollover Rules Changes & Key Insights

    Quick Summary

    A Gold IRA rollover lets you move funds from a 401(k) or existing IRA into a self-directed account holding physical precious metals, completely tax-free if done correctly in 2026.

    Missing the 60-day indirect rollover deadline triggers a 10% early withdrawal penalty plus ordinary income tax on the full balance, a mistake that can cost tens of thousands of dollars.

    In 2026, contribution limits have increased: $7,500 for those under 50, and $8,600 for those 50 and older using the catch-up provision.

    SECURE Act 2.0 rules now require Traditional Gold IRA holders to begin Required Minimum Distributions at age 73, Roth Gold IRAs have no such requirement.

    Not all gold is IRS-approved; keep reading to find out exactly which coins and bars qualify, and which ones will disqualify your entire account.

    Table of Contents

    1. Quick Summary
    2. Gold IRA Rollovers Are Changing in 2026: Here’s What You Need to Know First
    3. Direct vs. Indirect Rollovers: The Rule That Could Cost You 20%
    4. 2026 IRS Contribution Limits for Gold IRAs
    5. SECURE Act 2.0 Distribution Rules Now in Effect
    6. Home Storage of IRA Gold Is Still Illegal in 2026
    7. MAGI Phase-Out Ranges and Tax Implications in 2026
    8. How to Execute a Gold IRA Rollover in 2026
    9. The Bottom Line on Gold IRA Rollover Rules in 2026
    10. Frequently Asked Questions

    Gold IRA Rollovers Are Changing in 2026: Here’s What You Need to Know First

    The rules governing Gold IRA rollovers have never been more consequential than they are right now. With macroeconomic uncertainty pushing record numbers of investors away from traditional paper assets, Gold IRA rollover activity has surged sharply in 2026, according to a research report by Gold Silver News. That surge brings both opportunity and risk because the IRS rules governing these accounts are unforgiving, and a single procedural mistake can turn a tax-free transfer into a taxable distribution.

    Whether you’re moving funds from a former employer’s 401(k) or reallocating an existing Traditional IRA, understanding the mechanics of how these rollovers work in 2026 is the difference between preserving your retirement wealth and watching a chunk of it disappear in penalties and taxes.

    Direct vs. Indirect Rollovers: The Rule That Could Cost You 20%

    This is the most critical distinction in the entire Gold IRA rollover process, and it’s the one most investors get wrong. There are two methods: a direct rollover and an indirect (60-day) rollover. The method you choose determines whether your full account balance makes it into your new Gold IRA, or whether 20% of it gets withheld before you ever see it.

    How a Direct Rollover Protects Your Full Account Value

    In a direct rollover, the funds move directly from your existing plan administrator or IRA custodian to your new Gold IRA custodian. You never touch the money. The check is made payable to the new custodian, not to you,  and there is no tax withholding, no penalty, and no reportable income event. This is the cleanest, safest way to execute a Gold IRA rollover in 2026.

    A practical example: an investor transferring $50,000 from a former employer’s 401(k) into a self-directed Gold IRA via direct rollover receives the full $50,000 deposited into the new account. That full amount is immediately available to purchase IRS-approved metals. Nothing is lost to withholding.

    The 60-Day Indirect Rollover Window and Its Penalties

    With an indirect rollover, your plan administrator sends the distribution check directly to you. You then have exactly 60 calendar days to deposit the full amount into your new Gold IRA. Miss that deadline by even one day, and the IRS treats the entire distribution as ordinary taxable income, plus a 10% early withdrawal penalty if you’re under age 59½. There are no extensions and very few exceptions.

    Why the Check Must Never Be Made Out to You

    When a 401(k) distribution is paid directly to you, your employer’s plan administrator is required by law to withhold 20% for federal taxes upfront. That means if you’re rolling over $50,000, you only receive $40,000. To complete a valid rollover, you must deposit the full $50,000 into your Gold IRA within 60 days, which means you’d need to pay the missing $10,000 out of pocket. This is why a direct rollover is almost always the superior choice.

    2026 IRS Contribution Limits for Gold IRAs

    Rollovers do not count toward your annual contribution limits, but new contributions do. Here’s what the IRS allows in 2026:

    The $7,500 Standard Limit and Who It Applies To

    For investors under the age of 50, the 2026 IRS contribution limit for a Gold IRA is $7,500 per year. This applies whether your account is structured as a Traditional Gold IRA or a Roth Gold IRA. This limit is per person, not per account, meaning if you hold both a Traditional and a Roth IRA, your combined contributions across both accounts cannot exceed $7,500.

    The $8,600 Catch-Up Contribution for Ages 50 and Over

    If you’re 50 or older, the IRS allows an additional catch-up contribution, bringing your total annual limit to $8,600 in 2026. This provision exists specifically to help those closer to retirement age accelerate their precious metals accumulation within a tax-advantaged structure. If you haven’t been maximizing this, 2026 is the year to start.

    How the Combined Limit Works Across Traditional and Roth IRAs

    The $7,500 (or $8,600 catch-up) limit is an aggregate limit. Splitting contributions between a Traditional Gold IRA and a Roth Gold IRA is permitted, but the combined total cannot exceed the annual cap. Exceeding the limit triggers a 6% excise tax on the excess amount for every year it remains in the account, an easily avoidable but surprisingly common mistake.

    SECURE Act 2.0 Distribution Rules Now in Effect

    The SECURE Act 2.0 introduced phased changes to Required Minimum Distribution ages that are now actively shaping how Gold IRA holders plan their withdrawals. Understanding exactly when your RMDs kick in, and how to potentially eliminate them, is one of the highest-leverage decisions you can make in retirement planning right now.

    Required Minimum Distributions Starting at Age 73

    Under SECURE Act 2.0, individuals born between 1951 and 1959 must begin taking Required Minimum Distributions from their Traditional Gold IRA at age 73. For those born in 1960 or later, the RMD start age shifts to age 75, though that provision doesn’t become effective until 2033. Missing an RMD triggers a penalty of 25% of the amount that should have been withdrawn, reduced to 10% if corrected promptly within a two-year correction window. Your custodian is required to calculate your RMD annually, but the legal responsibility to take it on time falls on you.

    Augusta Precious Metals is one example of an established traditional precious metals IRA and can help investors navigate the Gold IRA process with educational resources and competitive prices.

    Visit Augusta’s official site and receive a free gold IRA guide by clicking the banner below and filling out their short form.

    Why Roth Gold IRAs Have No RMD Requirement

    This is one of the most powerful and underutilized advantages of the Roth Gold IRA structure. Roth accounts carry no RMD requirement during the original account holder’s lifetime, which means your physical gold holdings can continue compounding tax-free indefinitely.

    When you pass, your beneficiaries inherit the account with the tax-free status intact, though they are subject to the 10-year distribution rule under SECURE Act 2.0. For investors who don’t need retirement income from this account and want to maximize estate transfer efficiency, the Roth Gold IRA is often the stronger structure.

    Bear in mind, contributions for traditional gold IRAs are funded with pre-tax dollars. Contributions may be tax-deductible for the year you make them.

    Roth gold IRA contributions are funded with after-tax dollars. You do not get an upfront tax deduction for your contributions.

    Select the account type that works for your specific needs.

    Home Storage of IRA Gold Is Still Illegal in 2026

    This is a point worth stating plainly: you cannot store IRA-owned gold at home, in a personal safe, or in a safe-deposit box in your name. Some marketing in the precious metals industry promotes so-called “home storage Gold IRAs” as a legal structure; they are not. The IRS requires that all physical metals held inside a Gold IRA be stored in an IRS-approved, insured depository managed by a qualified trustee or custodian.

    Taking physical possession of your IRA metals, for any reason other than a qualified distribution, is treated by the IRS as a full taxable distribution of the assets you received. Popular approved depositories include Brink’s Global Services, Delaware Depository, and International Depository Services (IDS). Your Gold IRA custodian will facilitate the transfer of purchased metals directly to one of these facilities; you should never be handling the metals in transit yourself.

    MAGI Phase-Out Ranges and Tax Implications in 2026

    Your Modified Adjusted Gross Income (MAGI) directly determines both your ability to contribute to a Roth Gold IRA and whether your Traditional Gold IRA contributions are tax-deductible. These aren’t minor technical details; they can mean the difference between a fully deductible contribution and one that provides zero immediate tax benefit.

    Both Traditional and Roth Gold IRAs are subject to income-based restrictions, but the rules work differently for each. Traditional IRA deductibility is affected by whether you (or your spouse) are covered by a workplace retirement plan. Roth IRA eligibility is based purely on income, with no workplace plan variable involved.

    How MAGI Affects Your Roth Gold IRA Eligibility

    In 2026, single filers with a MAGI below the phase-out threshold can make a full Roth Gold IRA contribution. Once your income enters the phase-out range, your contribution limit begins to reduce proportionally. Once you exceed the upper limit of the phase-out range, you are completely ineligible to contribute to a Roth Gold IRA for that tax year.

    One workaround that remains available in 2026 is the backdoor Roth IRA conversion, making a non-deductible Traditional IRA contribution and then immediately converting it to a Roth. This strategy requires careful execution to avoid the pro-rata rule triggering unintended taxes, and it’s worth coordinating with a tax advisor before proceeding.

    Traditional Gold IRA Deductibility Based on Income

    Traditional Gold IRA Deductibility Based on Income
    Traditional Gold IRA Deductibility Based on Income

    If neither you nor your spouse participates in a workplace retirement plan, your Traditional Gold IRA contributions are fully deductible regardless of your income level. This is a significant advantage for self-employed investors or those whose employers don’t offer retirement benefits.

    If you are covered by a workplace plan, your deduction begins to phase out once your MAGI crosses the IRS threshold for your filing status. Contributions above the deductible limit can still be made as non-deductible Traditional IRA contributions, but you’ll want to track your cost basis carefully using IRS Form 8606 to avoid being taxed again on that money at distribution.

    One important planning note: even if your contribution isn’t deductible, the gold held inside the account still grows tax-deferred until withdrawal. That continued shelter from annual capital gains taxes on precious metals, which are typically taxed at the higher collectibles rate of 28% when held outside an IRA, is a meaningful advantage even without the upfront deduction.

    Getting clarity on your MAGI position before the contribution deadline is one of the most impactful steps you can take before year-end. Running the numbers with a tax professional in Q3 or Q4 gives you time to adjust contributions, execute a conversion, or explore alternative strategies before the window closes.

    How to Execute a Gold IRA Rollover in 2026

    The actual mechanics of a Gold IRA rollover are straightforward when you follow the right sequence. Most rollovers from a 401(k) to a Gold IRA take approximately 2 to 3 weeks from initiation to completion, longer than a standard IRA-to-IRA transfer because the 401(k) plan administrator, your employer, and the new custodian all need to coordinate. Knowing each step in advance prevents delays and costly mistakes.

    Here is the complete process as it stands in 2026:

    1. Choosing a Reputable Gold IRA Company

    Your Gold IRA company is not the same as your custodian; it is the dealer that guides you through the process, helps you select IRS-approved metals, and connects you with a custodian and depository. Choosing the right one upfront saves you from costly mistakes later.

    Look for companies with long operating histories, transparent fee structures, and strong third-party reviews. A company that pressures you into making a quick decision or upsells you into rare or collectible coins is a red flag; collectibles are not IRS-approved for Gold IRAs and can disqualify your account.

    Augusta Precious Metals is one example of an established precious metals provider that helps investors navigate the Gold IRA process, offering IRS-approved coins and bars along with educational resources for beginners who are just getting started with precious metals retirement planning.

    Visit Augusta’s official site and receive a free gold IRA guide by clicking the banner below.
    2. Choose an IRS-Compliant Self-Directed IRA Company

    Not every IRA company supports physical precious metals. You need a self-directed IRA (SDIRA) custodian that is specifically authorized to hold alternative assets, including gold bullion. Verify that your chosen company works with a custodian that is IRS-approved and has established relationships with IRS-compliant depositories. Review their ratings on the Better Business Bureau (BBB), Trustpilot, and Google before committing.

    Certain IRA companies have higher investment minimums than others. If you are a serious investor with a minimum of $50,000, you can take advantage of Augusta Precious Metals’ higher competitive prices, lifelong customer service, and educational resources.

    If you require a lower barrier to entry, both National Gold Group and Birch Gold Group provide a $10,000 investment minimum.

    National Gold Group provides exceptional price transparency and reliable buyback commitment. Birch Gold Group is one of the most established and trusted gold IRA companies, spanning over 20 years, and provides some of the lowest fees in the industry.

    Decide which gold IRA company works for you by accessing their free gold IRA guide by clicking the banners below and filling out their short contact form.

    Birch Gold Group: Best Gold IRA for Established Trust & Low Fees

    National Gold Group Review

    National Gold Group: Best Gold IRA for Transparency & Buyback

    Initiate a Direct Rollover From Your 401(k) Administrator

    Contact your current 401(k) plan administrator and request a direct rollover to your new Gold IRA custodian. Specifically request that the distribution check be made payable to your new custodian, not to you personally. This single instruction is what prevents the mandatory 20% federal withholding from reducing your transfer amount.

    Your new custodian will typically provide a rollover request letter or transfer form that you submit to your 401(k) administrator to initiate the process. Keep copies of every document submitted and follow up within 5 to 7 business days if you have not received confirmation that the transfer is in progress.

    4. Select IRS-Approved Metals and an Approved Depository

    Once funds arrive in your new self-directed IRA, you direct your custodian to purchase specific IRS-approved metals on your behalf. Your custodian executes the purchase and arranges for direct shipment to an approved depository; you never take physical possession of the metals during this stage. Confirm the specific coins or bars you’re purchasing meet IRS purity standards before the order is placed, and request written confirmation of depository assignment and storage allocation once the transaction clears.

    5. Confirm Regulated Storage and Receive Account Documentation

    Once your metals have been purchased and delivered to the approved depository, request written confirmation from both your custodian and the depository facility.

    This documentation should include the specific metals held, their weight and purity, your account number, and the storage allocation type, either segregated (your metals stored separately from other clients’ holdings) or commingled (stored together with other clients’ equivalent holdings). Segregated storage costs more but provides cleaner asset identification, which matters significantly at distribution time.

    The Bottom Line on Gold IRA Rollover Rules in 2026

    The rules governing Gold IRA rollovers in 2026 reward investors who understand the mechanics and penalize those who don’t. A direct rollover executed correctly costs you nothing in taxes or penalties and preserves every dollar of your retirement savings for precious metals acquisition. An indirect rollover mishandled by a single day, or a check made payable to you instead of your custodian, can wipe out years of tax-advantaged growth in a single transaction.

    The contribution limits, SECURE Act 2.0 distribution rules, IRS-approved metals requirements, and MAGI phase-out thresholds are all working parts of the same system. Each one interacts with the others, which is why a piecemeal understanding of these rules is genuinely dangerous. The investors who are positioning themselves most effectively in 2026 are treating their Gold IRA as an integrated component of a broader retirement architecture, not as a standalone product.

    Know your rollover type. Verify your metals. Choose a custodian with a verified compliance record. Confirm your storage. And if any step in that process is unclear, get it answered before you move a single dollar, because in the world of IRS retirement regulations, the cost of a mistake is always higher than the cost of asking the right question in advance.

    If you are ready to explore how physical precious metals can strengthen your retirement strategy, Augusta Precious Metals offers a full range of IRS-approved gold and silver products along with expert guidance to help you build a Gold IRA that works for your long-term goals. Click the banner below to get started.

    Frequently Asked Questions

    The most common questions about Gold IRA rollovers in 2026 center on tax treatment, timing rules, product eligibility, and contribution limits. Here are the answers to the questions investors ask most, answered directly, without the usual industry hedging.

    Can I Roll Over My Entire 401(k) Into a Gold IRA Without Paying Taxes?

    Yes, provided you execute a direct rollover from your 401(k) plan administrator to your new Gold IRA custodian. In a direct rollover, the funds transfer between institutions without ever touching your hands, which means no taxable distribution is triggered and no 20% federal withholding is applied. The full balance of your 401(k) arrives intact in your new self-directed IRA.

    The tax-free treatment applies regardless of the dollar amount being transferred, and the rollover does not count toward your annual IRA contribution limit. The key is ensuring the distribution check is made payable to your new custodian, not to you personally. If the check comes to you, the 20% withholding kicks in automatically and you’re on the clock for the 60-day redeposit window.

    What Happens If I Miss the 60-Day Indirect Rollover Deadline?

    Missing the 60-day deadline on an indirect rollover converts your rollover into a taxable distribution. The full amount of the distribution is added to your ordinary income for that tax year, and if you’re under age 59½, a 10% early withdrawal penalty is applied on top of the income tax owed.

    There is no standard grace period, and the IRS grants waivers only in very specific hardship circumstances, such as medical emergencies, natural disasters, or financial institution errors. The simplest way to eliminate this risk is to use a direct rollover instead.

    How Many Times Per Year Can I Roll Over Into a Gold IRA?

    The IRS’s one-rollover-per-year rule applies specifically to indirect (60-day) rollovers between IRAs. You are limited to one indirect rollover per 12-month period across all your IRA accounts combined, not per account. If you execute a second indirect IRA-to-IRA rollover within the same 12-month window, the second rollover is treated as a taxable distribution.

    Direct rollovers and trustee-to-trustee transfers are not subject to this limitation. You can execute an unlimited number of direct rollovers or direct transfers in a given year without triggering the one-rollover rule. This is another reason why direct rollovers are the preferred mechanism; they give you flexibility to move funds multiple times within a year if your strategy requires it.

    The 12 months are measured from the date you received the funds in the indirect rollover, not from January 1 of the calendar year. So if you received an indirect rollover distribution on March 15, 2026, you cannot initiate another indirect IRA-to-IRA rollover until March 16, 2027.

    Does a Gold IRA Rollover Count Toward My Annual Contribution Limit?

    No. A rollover, whether direct or indirect, does not count toward your annual IRA contribution limit. The IRS treats rollovers as transfers of existing retirement funds, not as new contributions. This means you can roll over $50,000, $200,000, or your entire 401(k) balance into a Gold IRA in 2026 without affecting your ability to also make a separate annual contribution of up to $7,500 (or $8,600 if you’re 50 or older) to that same account or another IRA.

    This distinction is one of the most valuable aspects of the rollover mechanism. It allows investors approaching retirement to consolidate large employer-sponsored plan balances into a self-directed Gold IRA while simultaneously continuing to make regular annual contributions, maximizing both the transfer efficiency and the ongoing tax-advantaged accumulation potential of the account.

    The one exception worth noting is a Roth conversion, which is treated differently from a rollover for tax purposes. Converting a Traditional Gold IRA balance to a Roth Gold IRA triggers ordinary income tax on the converted amount in the year of conversion, but it also does not count as a contribution toward the annual limit. Roth conversions have no dollar cap, giving high-income investors a pathway to Roth Gold IRA accumulation that bypasses the standard income eligibility restrictions.

    Click the banner below to access these calculators and start protecting your wealth today.

    GOLD IRA CALCULATOR
    GOLD IRA CALCULATOR

    Sources:

    Gold IRA storage rules: IRS requirements for storing precious metals: Yahoo!Finance

    Investments in collectibles in individually directed qualified plan accounts: IRS.gov

    Retirement plans FAQs regarding IRAs: IRS.gov

  • Gold IRA Investing in 2026: Why Demand Is Surging and How to Choose the Best Gold IRA Company for Your Retirement

    Gold IRA Investing in 2026: Why Demand Is Surging and How to Choose the Best Gold IRA Company for Your Retirement

    Gold IRA Investing- Why Demand Is Surging and How to Choose the Best Gold IRA Company for Your Retirement
    Gold IRA Investing: Why Demand Is Surging and How to Choose the Best Gold IRA Company for Your Retirement

    Quick Summary

    Gold IRA demand is surging in 2026 due to persistent inflation, geopolitical uncertainty, and fully enacted SECURE Act 2.0 provisions prompting investors to rethink retirement strategy. A Gold IRA offers tax-advantaged exposure to physical gold, portfolio diversification, and protection against currency debasement, but choosing the right company is critical.

    Look for IRS-authorized custodians, transparent fee structures, and strong third-party reviews. Only IRS-approved metals (99.5%+ purity) qualify, and your metals must be stored in an approved depository — never at home.

    Top providers like Augusta Precious Metals, Birch Gold Group, and National Gold Group offer different minimums and strengths to fit your situation.


    Table of Contents

    1. Quick Summary
    2. Why Has Gold IRA Rollover Demand Surged in 2026?
    3. How to Evaluate a Gold IRA Provider Before You Commit
    4. How to Execute a Gold IRA Rollover in 2026
    5. Which Gold Products Are Actually IRS-Approved
    6. FAQ

    Why Has Gold IRA Rollover Demand Surged in 2026?

    According to Gold Silver News’ 2026 research report, Gold IRA rollover activity has risen sharply this year, with demand for physical asset-backed retirement accounts accelerating at a pace not seen in recent cycles. This isn’t speculative momentum; it reflects a structural shift in how retirement investors are thinking about portfolio resilience and purchasing power preservation.

    The macroeconomic environment driving this shift is layered. Persistent inflation concerns, ongoing geopolitical instability, and growing skepticism about the long-term stability of dollar-denominated paper assets have all contributed to a renewed interest in physical gold as a retirement allocation. Investors who watched equity-heavy portfolios absorb volatility in recent years are now actively seeking assets with lower correlation to stock market performance.

    What makes 2026 particularly significant is that the structural retirement planning landscape has also changed. The SECURE Act 2.0 provisions now fully in effect, have prompted investors to reassess distribution timing, Roth conversion strategies, and legacy planning, all areas where a Gold IRA can play a meaningful role. The rules are clearer, the custodian infrastructure is more developed, and the investor education gap has narrowed considerably compared to five years ago.

    • Inflation hedging: Physical gold has historically maintained purchasing power during inflationary periods, making it a logical allocation for long-duration retirement accounts.
    • Portfolio diversification: Gold’s low correlation to equities and bonds reduces overall portfolio volatility when included as a strategic allocation.
    • Tax-advantaged accumulation: Holding gold inside an IRA structure shelters gains from the 28% collectibles capital gains tax rate that applies to metals held in taxable accounts.
    • Estate planning efficiency: Roth Gold IRAs in particular offer tax-free inheritance for beneficiaries, making them a powerful multi-generational wealth transfer tool.
    • Currency debasement protection: Investors concerned about long-term dollar purchasing power view gold as a structural hedge against monetary policy risk.

    The investors moving into Gold IRAs in 2026 aren’t chasing a trend; they’re making deliberate structural decisions about where they want their retirement wealth to sit over the next decade. That distinction matters, because it means the due diligence required goes beyond simply opening an account and buying the first approved coin on the list.

    How to Evaluate a Gold IRA Provider Before You Commit

    The surge in Gold IRA rollover activity in 2026 has attracted both reputable firms and predatory operators into the space. Choosing the wrong provider doesn’t just cost you in fees; it can expose your retirement savings to compliance failures, hidden markups on metals, and custodians who aren’t actually IRS-authorized. The evaluation process deserves as much attention as the rollover mechanics themselves.

    A legitimate Gold IRA provider will be transparent about their fee structure from the first conversation. Setup fees, annual custodial fees, storage fees, and transaction fees should all be disclosed in writing before you sign anything. If a provider is vague about costs, pushes urgency, or leads with promises of guaranteed returns on gold, treat those as immediate disqualifying signals.

    BBB, Trustpilot, and Google Reviews as Verification Tools

    Start your vetting process with third-party review platforms. A strong Better Business Bureau (BBB) rating, ideally A or A+, combined with consistent positive reviews on Trustpilot and Google, gives you a multi-source picture of how a provider actually operates with real clients. Look specifically at how the company responds to negative reviews, not just the volume of positive ones. A provider that engages professionally with complaints signals institutional accountability.

    Beyond reviews, verify that the custodian is registered with the appropriate regulatory bodies. Self-directed IRA custodians are typically regulated by state banking authorities or the IRS, and their approval status should be independently verifiable. Never rely solely on a provider’s own claims about their compliance status.

    Red Flags to Watch for in Provider Selection

    Some of the most damaging Gold IRA mistakes investors make in 2026 start with provider selection, not the rollover process itself. Watch for these specific warning signs before you hand over your retirement funds:

    • Pressure tactics pushing you to act before you’ve reviewed all documentation
    • Promotions of home storage Gold IRAs as a legal, IRS-compliant option
    • Vague or verbal-only fee disclosures with no written schedule provided
    • No clear disclosure of which depository your metals will be stored in
    • Metals offered at prices significantly above spot price without explanation
    • No verifiable BBB, Trustpilot, or Google review presence
    • Claims of guaranteed returns or recession-proof performance

    Any provider worth working with will actively encourage you to take your time, ask questions, and compare options. The ones who push back on that approach are telling you everything you need to know.

    Choosing a Reputable Gold IRA Company

    Your Gold IRA company is not the same as your custodian; it is the dealer that guides you through the process, helps you select IRS-approved metals, and connects you with a custodian and depository. Choosing the right one upfront saves you from costly mistakes later.

    Look for companies with long operating histories, transparent fee structures, and strong third-party reviews. A company that pressures you into making a quick decision or upsells you into rare or collectible coins is a red flag; collectibles are not IRS-approved for Gold IRAs and can disqualify your account.

    Augusta Precious Metals is one example of an established precious metals provider that helps investors navigate the Gold IRA process, offering IRS-approved coins and bars along with educational resources for beginners who are just getting started with precious metals retirement planning.

    Visit Augusta’s official site and receive a free gold IRA guide by clicking the banner below.
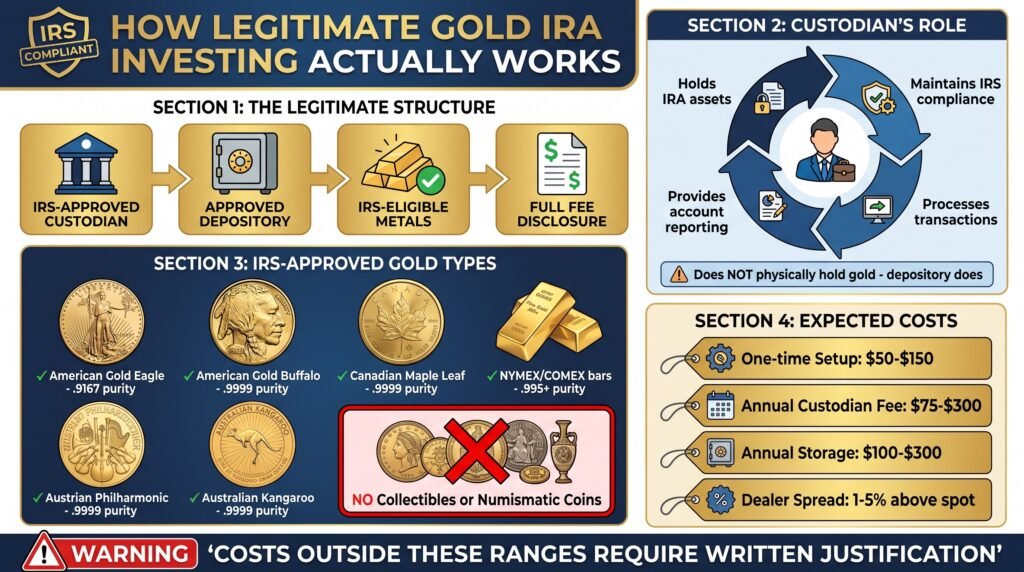
    How to Execute a Gold IRA Rollover in 2026

    The actual mechanics of a Gold IRA rollover are straightforward when you follow the right sequence. Most rollovers from a 401(k) to a Gold IRA take approximately 2 to 3 weeks from initiation to completion, longer than a standard IRA-to-IRA transfer because the 401(k) plan administrator, your employer, and the new custodian all need to coordinate. Knowing each step in advance prevents delays and costly mistakes.

    1. Choose an IRS-Compliant Self-Directed IRA Custodian

    Not every IRA custodian supports physical precious metals. You need a self-directed IRA (SDIRA) custodian that is specifically authorized to hold alternative assets, including gold bullion.

    Verify that your chosen custodian is IRS-approved, maintains transparent fee structures, and has established relationships with IRS-compliant depositories. Review their ratings on the Better Business Bureau (BBB), Trustpilot, and Google before committing.

    2. Initiate a Direct Rollover from Your 401(k) Administrator

    Contact your current 401(k) plan administrator and request a direct rollover to your new Gold IRA custodian. Specifically request that the distribution check be made payable to your new custodian, not to you personally. This single instruction is what prevents the mandatory 20% federal withholding from reducing your transfer amount.

    Your new custodian will typically provide a rollover request letter or transfer form that you submit to your 401(k) administrators to initiate the process. Keep copies of every document submitted and follow up within 5 to 7 business days if you have not received confirmation that the transfer is in progress.

    3. Select IRS-Approved Metals and an Approved Depository

    Once funds arrive in your new self-directed IRA, you direct your custodian to purchase specific IRS-approved metals on your behalf. Your custodian executes the purchase and arranges for direct shipment to an approved depository; you never take physical possession of the metals during this stage.

    Confirm the specific coins or bars you’re purchasing meet IRS purity standards before the order is placed, and request written confirmation of depository assignment and storage allocation once the transaction clears.

    4. Confirm Regulated Storage and Receive Account Documentation

    Once your metals have been purchased and delivered to the approved depository, request written confirmation from both your custodian and the depository facility.

    This documentation should include the specific metals held, their weight and purity, your account number, and the storage allocation type, either segregated (your metals stored separately from other clients’ holdings) or commingled (stored together with other clients’ equivalent holdings). Segregated storage costs more but provides cleaner asset identification, which matters significantly at the time of distribution.

    Which Gold Products Are Actually IRS-Approved

    Not all gold qualifies for an IRA. The IRS has strict purity and sourcing requirements, and purchasing a non-compliant product inside your IRA can result in the entire account being treated as a taxable distribution. The standard purity requirement for gold bullion is 99.5% fineness (0.995) or higher.

    There is one notable exception to the 99.5% rule: the American Gold Eagle coin, which is only 91.67% pure (22 karat) but is specifically authorized by the IRS as an approved IRA investment due to its status as U.S. legal tender. Every other coin must meet the 99.5% threshold.

    24K Coins: American Buffalo and Canadian Maple Leaf

    The American Gold Buffalo (24K, 99.99% pure) and the Canadian Gold Maple Leaf (24K, 99.99% pure) are both fully IRS-compliant for Gold IRA inclusion in 2026. These are among the most widely held coins in self-directed precious metals IRAs because of their recognized purity, global liquidity, and broad custodian acceptance. The South African Krugerrand, by contrast, does not meet IRS standards and is explicitly prohibited.

    Approved Bars from Accredited Refiners Like PAMP Suisse

    Gold bars are eligible when they meet the 99.5% purity standard and are produced by an NYMEX- or COMEX-approved refiner or assayer, or a national government mint. PAMP Suisse bars are among the most widely accepted in the industry.

    Custodians typically maintain resources listing IRS-compliant refiners and products; always verify your specific bar or coin with your custodian before purchasing inside the account.

    What Gets Disqualified and Why

    The most common disqualifying factors come down to purity and sourcing. Gold that falls below the 99.5% fineness threshold, with the sole exception of the American Gold Eagle, cannot be held in an IRA. Collectible coins, numismatic coins, and gold jewelry are explicitly prohibited regardless of their market value or gold content. The IRS draws a hard line between investment-grade bullion and collectibles.

    Purchasing a disqualified asset inside your Gold IRA doesn’t just result in that single item being removed; the IRS can treat the entire transaction as a taxable distribution. That means the full value of the purchase could be added to your taxable income for that year, plus the 10% early withdrawal penalty if you’re under 59½. Always verify compliance with your custodian before executing any purchase inside the account.

    If you are ready to explore how physical precious metals can strengthen your retirement strategy, Augusta Precious Metals offers a full range of IRS-approved gold and silver products along with expert guidance to help you build a Gold IRA that works for your long-term goals.

    Investment Minimums – Personal Considerations

    Certain IRA companies have higher investment minimums than others. If you are a serious investor with a minimum of $50,000, you can take advantage of Augusta Precious Metals’ higher competitive prices, lifelong customer service, and educational resources.

    If you require a lower barrier to entry, both National Gold Group and Birch Gold Group provide a $10,000 investment minimum.

    National Gold Group provides exceptional price transparency and reliable buyback commitment. Birch Gold Group is one of the most established and trusted gold IRA companies, spanning over 20 years, and provides some of the lowest fees in the industry.

    Decide which gold IRA company works for you by clicking the banners below and accessing their free gold IRA guide. Fill out their short contact form to get started.

    Birch Gold Group: Best Gold IRA for Established Trust & Low Fees

    National Gold Group Review

    National Gold Group: Best Gold IRA for Transparency & Buyback

    Summary

    Gold IRA demand has reached a notable inflection point in 2026, driven by a confluence of macroeconomic pressures and structural shifts in retirement planning. Persistent inflation, geopolitical instability, and growing skepticism toward dollar-denominated assets have pushed investors toward physical gold as a long-term portfolio anchor. The full implementation of SECURE Act 2.0 has further accelerated this trend, prompting a fresh reassessment of distribution strategies, Roth conversions, and legacy planning — all areas where a Gold IRA can play a meaningful role.

    The core benefits driving adoption include inflation hedging, portfolio diversification, tax-advantaged accumulation inside an IRA structure, and protection against currency debasement. Roth Gold IRAs in particular are gaining traction as multi-generational wealth transfer tools, offering tax-free inheritance for beneficiaries.

    However, the surge in demand has also attracted predatory operators into the space. Choosing the right provider requires rigorous due diligence — verifying IRS-authorized custodians, scrutinizing fee disclosures, checking BBB and Trustpilot ratings, and avoiding any company that promotes home storage IRAs or guarantees returns. Red flags in provider selection are often more costly than mistakes made during the rollover itself.

    Executing a Gold IRA rollover involves four key steps: selecting an IRS-compliant self-directed IRA custodian, initiating a direct rollover from your 401(k) administrator, purchasing IRS-approved metals, and confirming regulated depository storage. Only metals meeting the IRS 99.5% purity threshold qualify — with the American Gold Eagle as the sole exception – and all holdings must be stored at an approved depository, never at home.

    For investors ready to act, providers like Augusta Precious Metals (best for investors with $50K+), Birch Gold Group (best for established trust and low fees), and National Gold Group (best for transparency and buyback) each offer distinct strengths depending on your investment size and priorities.

    Frequently Asked Questions

    Why is Gold IRA demand surging in 2026?

    A combination of persistent inflation, geopolitical instability, and the full implementation of SECURE Act 2.0 provisions has prompted investors to seek more resilient retirement allocations. Physical gold’s low correlation to equities and its historical role as a purchasing power hedge have made Gold IRAs an increasingly deliberate choice — not a speculative one.

    What’s the difference between a Gold IRA company and a custodian?

    A Gold IRA company (or dealer) guides you through the process, helps you select IRS-approved metals, and connects you with a custodian and depository. The custodian is the IRS-authorized institution that actually holds your account. You need both — and vetting each separately is essential before committing.

    What gold products are approved for a Gold IRA?

    Gold must meet a minimum purity of 99.5% fineness. IRS-approved options include the American Gold Buffalo, Canadian Gold Maple Leaf, and bars from NYMEX/COMEX-approved refiners like PAMP Suisse. The American Gold Eagle is the one exception — it’s only 91.67% pure but is IRS-approved due to its U.S. legal tender status. Collectibles, numismatic coins, and jewelry are prohibited.

    Can I store my Gold IRA metals at home?

    No. Home-storage Gold IRAs are not a legitimate IRS-compliant option despite being promoted by some providers. Your metals must be held at an IRS-approved depository. Taking personal possession of the metals before a qualified distribution triggers a taxable event and potential penalties.

    How long does a 401(k) to Gold IRA rollover take?

    Most rollovers take approximately 2 to 3 weeks from initiation to completion. The timeline is longer than a standard IRA-to-IRA transfer because the 401(k) plan administrator, employer, and new custodian all need to coordinate. Always request a direct rollover — payable to your new custodian, not to you — to avoid mandatory 20% federal tax withholding.


    Sources:
    Gold IRA Rules and Regulations: LendEDU

    Gold IRA storage rules: IRS requirements for storing precious metals: Yahoo!Finance

    Investments in collectibles in individually directed qualified plan accounts: IRS.gov: Retirement plans FAQs regarding IRAs: IRS.gov

  • 403(b) to Gold IRA Rollover – What Teachers & Nonprofits Need to Know (2026 Guide)

    403(b) to Gold IRA Rollover – What Teachers & Nonprofits Need to Know (2026 Guide)

    403(b) to Gold IRA Rollover - What Teachers & Nonprofits Need to Know (2026 Guide)
    403(b) to Gold IRA Rollover – What Teachers & Nonprofits Need to Know (2026 Guide)

    Quick Summary

    • Teachers and nonprofit workers can roll over a 403(b) into a gold IRA completely tax-free using a direct rollover, with no penalties and no taxable events.
    • A gold IRA is a self-directed retirement account that holds physical precious metals like gold bullion and coins approved by the IRS.
    • Not everyone qualifies immediately; your eligibility depends on your age, employment status, and your plan’s specific rollover rules.
    • The 60-day rule for indirect rollovers is a hard deadline; miss it, and the IRS treats the entire amount as taxable income.
    • There’s a critical step in choosing a gold IRA company that most guides skip over, and it could save you from losing your entire retirement savings to fraud.

    Rolling over your 403(b) into a gold IRA is one of the most powerful moves a teacher or nonprofit worker can make to protect retirement savings from inflation, and it can be done completely tax-free.

    Augusta Precious Metals is a leading precious metals company that specializes in helping educators and nonprofit professionals navigate gold IRA rollovers with confidence. Whether you’re just starting to research your options or ready to make the move, understanding the full process puts you in control of your financial future.

    Table of Contents

    1. Quick Summary
    2. Teachers and Nonprofit Workers Can Roll Over a 403(b) Into a Gold IRA Tax-Free
    3. You Must Meet These Eligibility Requirements Before You Roll Over
    4. Here Are the Step-by-Step Instructions for a 403(b) to Gold IRA Rollover
    5. Tax Implications You Need to Know Before You Roll Over
    6. Start Your 403(b) Gold IRA Rollover with Confidence
    7. Frequently Asked Questions

    Teachers and Nonprofit Workers Can Roll Over a 403(b) Into a Gold IRA Tax-Free

    Most people assume moving retirement funds is complicated, taxable, or risky. The truth is, when done correctly through a direct rollover, transferring your 403(b) into a gold IRA triggers zero taxes and zero penalties. Your money simply moves from one tax-advantaged account to another, with the added protection of physical gold backing your retirement.

    What a Gold IRA Actually Is

    A gold IRA is a self-directed individual retirement account that holds physical precious metals instead of, or alongside, traditional paper assets like stocks and mutual funds. Unlike a standard IRA, a gold IRA requires an IRS-approved custodian and an approved depository to store the physical metals on your behalf. You never personally hold the gold; it lives in a secure, insured facility.

    The metals allowed inside a gold IRA must meet strict IRS purity standards. Gold must be at least 99.5% pure, which includes products like the American Gold Eagle coin, Canadian Gold Maple Leaf, and gold bars produced by NYMEX- or COMEX-approved refiners. Silver, platinum, and palladium are also permitted under similar purity requirements.

    How a 403(b) Differs From a 401(k)

    A 403(b) is an employer-sponsored retirement plan specifically designed for employees of public schools, universities, hospitals, and nonprofit organizations. It functions similarly to a 401(k) in terms of contribution limits and tax-deferred growth, but it’s tailored to the unique employment structures of the education and nonprofit sectors.

    One key difference is that 403(b) plans are often more restrictive in their investment options, frequently limiting participants to annuities and mutual funds. This is precisely why so many educators and nonprofit workers look to roll over into a self-directed gold IRA; it opens the door to asset classes their 403(b) simply doesn’t offer.

    Why Educators Are Turning to Gold for Retirement Security

    Teacher pension systems across the country have faced funding shortfalls for years, leaving many educators uncertain about what their retirement will actually look like. Gold has historically held its value during economic downturns, stock market crashes, and periods of high inflation, making it an attractive complement to an otherwise volatile retirement portfolio.

    When the purchasing power of the dollar erodes, physical gold tends to move in the opposite direction. For a teacher or nonprofit worker whose pension may already be underfunded, adding gold to a self-directed IRA creates a meaningful layer of financial protection that paper assets simply can’t replicate. Learn about the real benefits of a gold IRA here, such as inflation hedging, portfolio diversification, and much more

    You Must Meet These Eligibility Requirements Before You Roll Over
    You Must Meet These Eligibility Requirements Before You Roll Over

    You Must Meet These Eligibility Requirements Before You Roll Over

    Before you contact a gold IRA company or start any paperwork, you need to confirm you actually qualify for a rollover. Moving forward without checking eligibility first is one of the most common and costly mistakes people make.

    Age, Employment Status, and Other Qualifying Conditions

    The IRS allows 403(b) rollovers under several qualifying conditions. You are generally eligible if you have separated from your employer, reached age 59½, experienced a financial hardship as defined by your plan, or your plan is being terminated. Some plans also allow in-service rollovers for participants who are still employed but have reached a certain age, typically 59½.

    It’s critical to check your specific 403(b) plan documents before assuming you qualify. Each plan has its own rules, and some may have additional restrictions or waiting periods. Contact your plan administrator directly and ask specifically whether your account is eligible for a rollover and what documentation they require.

    Direct vs. Indirect Rollover: Which One Protects You From Penalties

    A direct rollover means the funds move straight from your 403(b) plan administrator to your new gold IRA custodian. You never touch the money. This is the safest method because it eliminates any risk of triggering taxes or penalties; the IRS does not treat a direct rollover as a distribution.

    An indirect rollover works differently. Your plan administrator sends the funds directly to you, and you have 60 days to deposit the full amount into your new gold IRA.

    Here’s the catch: your plan administrator is required to withhold 20% for federal taxes upfront. That means if you have $100,000 in your 403(b), you’ll only receive $80,000.

    To avoid a taxable event, you must deposit the full $100,000 into your gold IRA within 60 days, including the $20,000 that was withheld, using your own funds. For most people, a direct rollover is the clear choice.

    Here Are the Step-by-Step Instructions for a 403(b) to Gold IRA Rollover

    The actual rollover process is more straightforward than most people expect, but the order of operations matters. Skipping steps or rushing the paperwork can create delays, tax complications, or worse. Follow this sequence carefully.

    1. Choose a Reputable Gold IRA Company

    Your Gold IRA company is not the same as your custodian; it is the dealer that guides you through the process, helps you select IRS-approved metals, and connects you with a custodian and depository. Choosing the right one upfront saves you from costly mistakes later.

    Look for companies with long operating histories, transparent fee structures, and strong third-party reviews. A company that pressures you into making a quick decision or upsells you into rare or collectible coins is a red flag; collectibles are not IRS-approved for Gold IRAs and can disqualify your account.

    Augusta Precious Metals is one example of an established precious metals provider that helps investors navigate the Gold IRA process, offering IRS-approved coins and bars along with educational resources for beginners who are just getting started with precious metals retirement planning.

    Visit Augusta’s official site and receive a free gold IRA guide by clicking the banner below. Fill out their short form to get started.
    Before committing to any company, ask these questions directly:

    • What are your setup, storage, and annual maintenance fees?
    • Which custodians and depositories do you work with?
    • What IRS-approved metals do you carry?
    • Do you offer buyback programs if I need to liquidate?

    2. Select an IRS-Compliant Custodian

    A custodian is the IRS-approved financial institution that works with your chosen gold IRA company and is responsible for administering your gold IRA and keeping your account compliant. The company handles the paperwork, record-keeping, and coordination with the depository where your physical metals are stored. Your gold IRA company will typically have preferred custodian partners they can recommend, but you always have the right to choose your own.

    Custodian fees vary and typically include an account setup fee, annual maintenance fee, and storage fees for the physical metals. Make sure you get a full fee schedule in writing before committing to any custodian.

    3. Contact Your 403(b) Plan Administrator

    • Ask whether your account is eligible for a rollover under your current employment and age status
    • Request the specific rollover or distribution forms required by your plan
    • Confirm whether your plan requires a signature guarantee or notarization on any documents
    • Ask for the exact wire transfer instructions or mailing address for your new gold IRA custodian
    • Get a timeline; ask how long the fund transfer typically takes once paperwork is submitted

    This step tends to take longer than people anticipate. Some 403(b) plan administrators process rollover requests within a few business days, while others, particularly large institutional plans, can take two to four weeks just to process the initial paperwork.

    Stay proactive and follow up regularly. Keep records of every conversation, including the date, the representative’s name, and what was discussed. This paper trail protects you if anything goes wrong during the transfer.

    4. Complete the Rollover Paperwork

    Once your chosen gold IRA company and 403(b) administrators are aligned, you’ll complete transfer authorization forms from both sides. Your gold IRA custodian will provide a new account application along with a transfer request form that authorizes the movement of funds directly from your 403(b). Double-check every detail, account numbers, legal names, and transfer amounts, before submitting. A single error can delay the process by weeks.

    5. Fund Your Gold IRA and Choose Your Metals

    Once the funds arrive in your gold IRA, you’ll work with your gold IRA company to select which IRS-approved precious metals to purchase. Your options include gold bullion bars, gold coins like the American Gold Eagle or the Canadian Gold Maple Leaf, and similar approved silver, platinum, or palladium products. Your custodian will then purchase the metals on your behalf and arrange for secure storage at an IRS-approved depository.

    The entire process, from opening your gold IRA to having metals stored in your account, typically takes several weeks to more than a month, depending on how quickly your 403(b) plan administrator processes the transfer. Patience here is important. Rushing the process or pressuring any party to move faster than their compliance procedures allow can introduce errors that are difficult to correct.

    Tax Implications You Need to Know Before You Roll Over

    The tax treatment of your rollover depends entirely on how you execute it and what type of 403(b) you have. Getting this wrong doesn’t just cost you money; it can trigger IRS penalties that take years to recover from.

    If your 403(b) is a traditional pre-tax account, rolling it into a traditional gold IRA is a non-taxable event when done as a direct rollover. If your 403(b) has a Roth component, it must roll into a Roth gold IRA to maintain that tax-free status. Mixing these up creates an immediate taxable event on the converted amount.

    How Direct Rollovers Keep the Transaction Tax-Free

    In a direct rollover, the funds never pass through your hands. Your 403(b) plan administrator wires the money or sends a check made payable directly to your new gold IRA custodian, without any withholding. Because you never receive the funds as a distribution, the IRS does not classify the transaction as taxable income.

    This is the single most important reason to choose a direct rollover over an indirect one. The tax protection is automatic and built into the mechanism of the transfer itself. There’s no filing required, no special election to make; the structure of the transaction does the work for you.

    Make sure to confirm in writing with your 403(b) administrator that the transfer will be processed as a direct rollover and that the check or wire is made payable to your custodian, not to you personally. This one detail is the difference between a tax-free transfer and an unexpected tax bill.

    The 60-Day Rule for Indirect Rollovers

    If you choose an indirect rollover, or if a direct rollover somehow results in a check being issued to you, the IRS gives you exactly 60 days to deposit the full original amount into your new gold IRA. Miss that deadline by even one day and the entire amount is treated as a taxable distribution, subject to income tax plus a 10% early withdrawal penalty if you’re under age 59½. The IRS grants very few exceptions to this rule, and “I forgot” is not one of them.

    Early Withdrawal Penalties and How to Avoid Them

    The 10% early withdrawal penalty applies to any distribution taken from a 403(b) before age 59½ that isn’t rolled over correctly. The simplest way to avoid it is to execute a direct rollover and never take personal possession of the funds. If you’re over 59½, the penalty no longer applies, but income taxes on pre-tax funds still do unless the money moves into another tax-deferred account.

    Why Working With a Tax Professional Is Worth It

    The IRS rules around retirement account rollovers are detailed, and the stakes are high enough that professional guidance pays for itself many times over. A seasoned gold IRA company familiar with self-directed IRAs can review your specific 403(b) plan documents, confirm your rollover strategy is structured correctly, and help you avoid the kinds of mistakes that trigger audits or penalties.

    This is especially important if you have both traditional and Roth contributions in your 403(b), have made after-tax contributions, or your plan includes employer matching funds with vesting schedules. Each of these factors affects how your rollover should be structured, and getting it right from the start is far easier than trying to fix it after the fact.

    How to Verify a Gold IRA Company Is Legitimate

    The gold IRA industry attracts both legitimate and predatory companies. Before you hand over your life savings to any firm, take the time to independently verify their credentials. A few minutes of due diligence can protect decades of retirement savings. Read more about what to look for when considering a gold IRA company for your 403(b) rollover.

    If you want a quick start guide, access Augusta Precious Metals’ free gold IRA company integrity checklist by clicking the banner below.
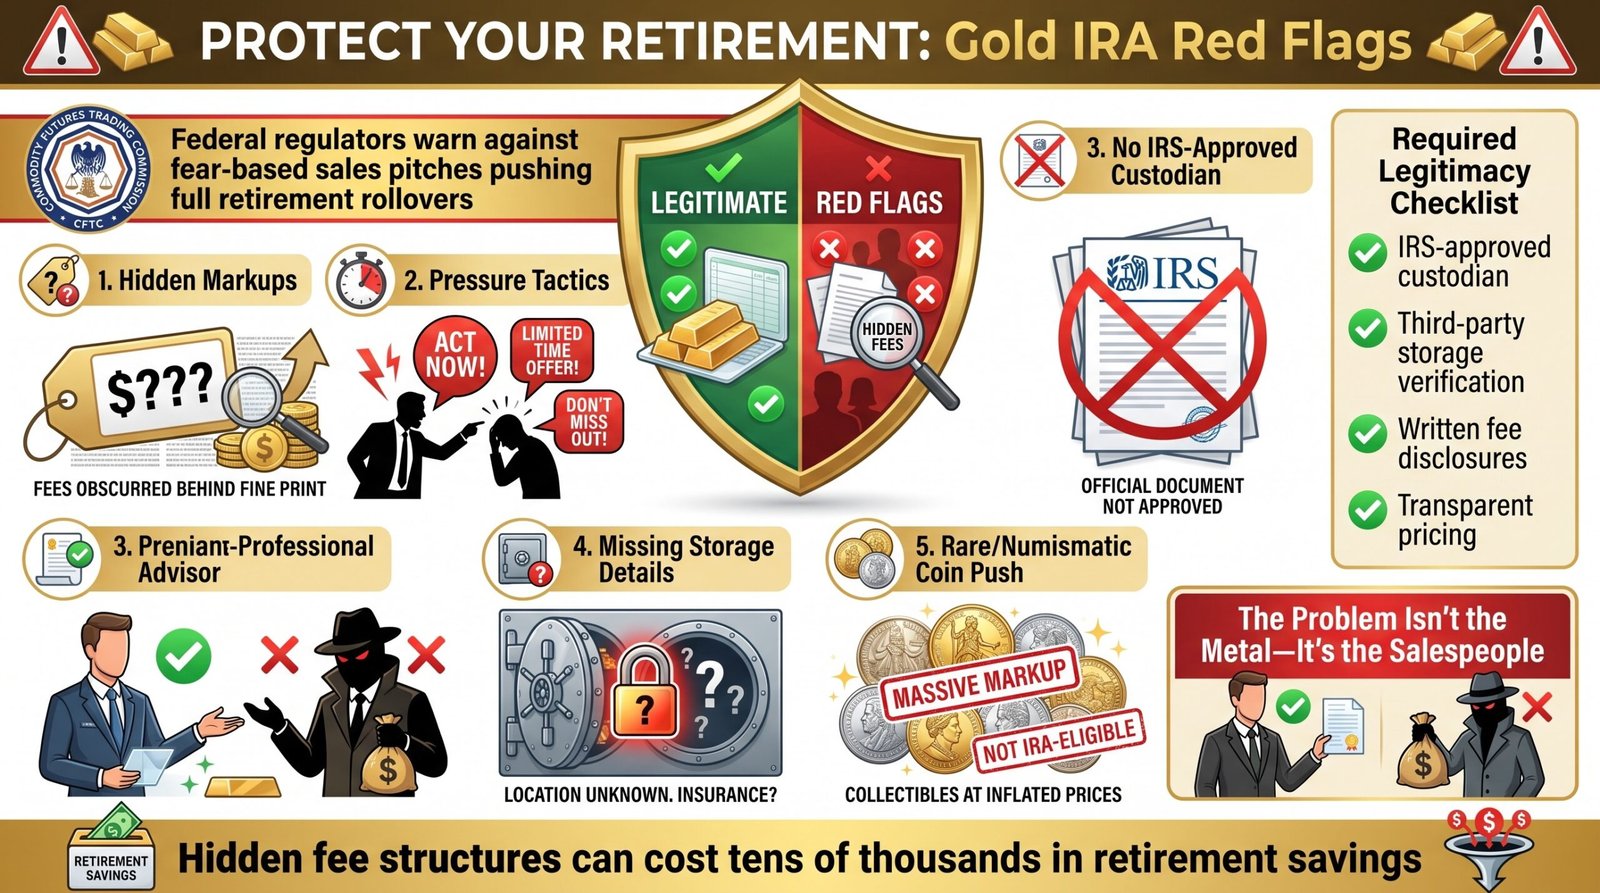
    Investment Minimums – Personal Considerations

    Certain IRA companies have higher investment minimums than others. If you are a serious investor with a minimum of $50,000, you can take advantage of Augusta Precious Metals’ higher competitive prices, lifelong customer service, and educational resources.

    If you require a lower barrier to entry, both National Gold Group and Birch Gold Group provide a $10,000 investment minimum.

    National Gold Group provides exceptional price transparency and reliable buyback commitment. Birch Gold Group is one of the most established and trusted gold IRA companies, spanning over 20 years, and provides some of the lowest fees in the industry.

    Decide which gold IRA company works for you by clicking the banners below and accessing their free gold IRA guide. Fill out their short contact form to get started.

    Birch Gold Group: Best Gold IRA for Established Trust & Low Fees

    National Gold Group Review

    National Gold Group: Best Gold IRA for Transparency & Buyback

    Start Your 403(b) Gold IRA Rollover with Confidence

    You’ve now got the full picture: eligibility requirements, direct vs. indirect rollover mechanics, tax implications, step-by-step instructions, and how to separate legitimate companies from fraudulent ones. The path forward is clear: choose a reputable gold IRA company, open a self-directed account with an IRS-approved custodian, initiate a direct rollover with your 403(b) plan administrator, and select your IRS-compliant precious metals. Done correctly, the entire transaction is tax-free, penalty-free, and one of the most effective ways to protect your retirement from inflation and market volatility.

    Augusta Precious Metals has helped thousands of teachers and nonprofit workers make this transition. Visit Augusta Precious Metals to learn more about your gold IRA rollover options and take the next step toward a more secure retirement.

    Read our full list of reviews of the best gold IRA companies that we have carefully researched and vetted here.

    Find out whether gold IRAs are a good choice for your retirement needs. Access our Gold IRA calculator. Bookmark this page and perform real-time calculations as you read our reviews.

    Click the image below to access these calculators and start protecting your wealth today.

    GOLD IRA CALCULATOR
    GOLD IRA CALCULATOR

    Frequently Asked Questions

    If you are still weighing whether a Gold IRA fits your retirement plan, these are the questions most beginners ask before taking the next step.

    Can I roll over a 403(b) into a gold IRA without paying taxes?

    Yes, a direct rollover from a traditional 403(b) into a traditional gold IRA is a completely tax-free transaction. Because the funds move directly from your plan administrator to your new gold IRA custodian without passing through your hands, the IRS does not classify it as a taxable distribution.

    The key is making sure your rollover is processed as a direct transfer and that you’re moving pre-tax funds into a traditional gold IRA, not a Roth account. If you have Roth contributions in your 403(b), those must roll into a Roth gold IRA to maintain their tax-free status. Mixing account types creates an immediate taxable event, so confirm the exact makeup of your 403(b) before initiating any transfer.

    What types of gold are allowed in a gold IRA?

    What gold coins and bars are IRS-approved for a Gold IRA?

    The IRS requires gold held in an IRA to meet a minimum purity standard of 99.5%. Approved products include the American Gold Eagle coin (which is an exception to the purity rule at 91.67% but is explicitly permitted by the IRS), the Canadian Gold Maple Leaf, the Australian Gold Kangaroo, the Austrian Gold Philharmonic, and gold bars or rounds produced by NYMEX- or COMEX-approved refiners.

    Collectible coins, rare coins, and gold jewelry do not qualify, regardless of their gold content or market value.

    Is a 403(b) to gold IRA rollover the same as a 401(k) rollover?

    The mechanics are very similar; both involve moving funds from an employer-sponsored retirement plan into a self-directed IRA, and both can be executed as direct rollovers to avoid taxes and penalties. The IRS treats qualified rollovers from 403(b) and 401(k) plans under the same general framework.

    The practical differences show up in the plan-level details. 403(b) plans are more commonly invested in annuity contracts, which can have surrender charges or restrictions that affect when and how much you can roll over. Some 403(b) plans also have more complex administrator requirements and longer processing timelines than typical 401(k) plans.

    If you’ve successfully rolled over a 401(k) before, the Gold IRA process will feel familiar, but it’s worth contacting your 403(b) administrator specifically to understand any plan-level restrictions that might not apply to a 401(k). Don’t assume the two processes are identical at the plan level, even though they’re governed by similar IRS rules.

    How long does a 403(b) to Gold IRA rollover take?

    The full process, from opening your gold IRA to having physical metals secured in an approved depository, typically takes several weeks to over a month. The biggest variable is your 403(b) plan administrator’s processing speed, which can range from a few business days to four weeks or more for large institutional plans.
    Breaking the timeline down by stage helps set realistic expectations:

    –Opening your gold IRA: 1 to 3 business days with most custodians
    -Submitting rollover paperwork to your 403(b) administrator: 1 to 5 business days to complete and submit
    -403(b) administrator processing the transfer: 5 to 20 business days depending on the plan
    -Funds arriving at your gold IRA custodian: 1 to 3 business days after the transfer is initiated
    -Purchasing metals and arranging depository storage: 1 to 5 business days after funding

    Following up proactively with your 403(b) administrator every few business days keeps the process moving. Keep written records of every interaction and confirm that your transfer has been submitted and is being processed; don’t assume silence means everything is on track.

    Do I need a financial advisor to roll over my 403(b) into a gold IRA?

    You are not legally required to work with a financial advisor to complete a 403(b) to gold IRA rollover. Many people complete the process successfully by working directly with a reputable gold IRA company and their 403(b) plan administrator. A quality gold IRA company will walk you through the paperwork, connect you with an IRS-approved custodian, and guide your metal selections, all without requiring a separate advisor.

    That said, if your financial situation is complex, meaning you have both traditional and Roth contributions, after-tax contributions, outstanding loans against your 403(b), or multiple retirement accounts, consulting a CPA or fee-only financial advisor before initiating the rollover is worth the cost. These variables can significantly affect how your rollover should be structured, and a professional can help you avoid mistakes that would be difficult and expensive to unwind.

    At minimum, consider a one-time consultation with a tax professional before you sign any paperwork. The cost of an hour of professional advice is negligible compared to the potential tax liability of a rollover that’s structured incorrectly, especially when your entire retirement account balance is on the line.

    If you are ready to explore how physical precious metals can strengthen your retirement strategy, Augusta Precious Metals offers a full range of IRS-approved gold and silver products along with expert guidance to help you build a Gold IRA that works for your long-term goals. Visit their official site by clicking the banner below.
    Sources:
    Gold IRA Rules and Regulations: LendEDU

    Gold IRA storage rules: IRS requirements for storing precious metals: Yahoo!Finance

    Investments in collectibles in individually directed qualified plan accounts: IRS.gov: Retirement plans FAQs regarding IRAs: IRS.gov